They thought I had come to watch my father close the biggest sale of his career. I sat quietly at the long conference table while he shook hands, laughed too loudly, and told everyone how proud he was to finally be “fixing the mistakes younger people make.” Then he glanced at me and added, “Some people build businesses. Others just play with spreadsheets.”
A few executives laughed politely. I didn’t. My father, Richard Hale, had spent twenty-eight years building a commercial equipment company outside Chicago. I had worked there after college, first in accounting, then restructuring. Three years earlier, I warned him that his expansion into five new states was being financed almost entirely with variable-rate debt.
He called me timid.
When I refused to sign off on another loan package, he removed me from the company. At Thanksgiving, he told relatives I had “walked away because pressure scared me.” I stopped correcting him. Instead, I started working for a distressed-investment firm downtown.
Now Hale Industrial owed nearly $18 million to three lenders.
The sale was supposed to save everything.
A regional competitor called Mercer Equipment had agreed to purchase two divisions and several warehouses. Dad believed the proceeds would eliminate most of the debt and leave him in control of the remaining business.
He had invited me because, as he put it, “You should see what confidence looks like.”
I came for a different reason.
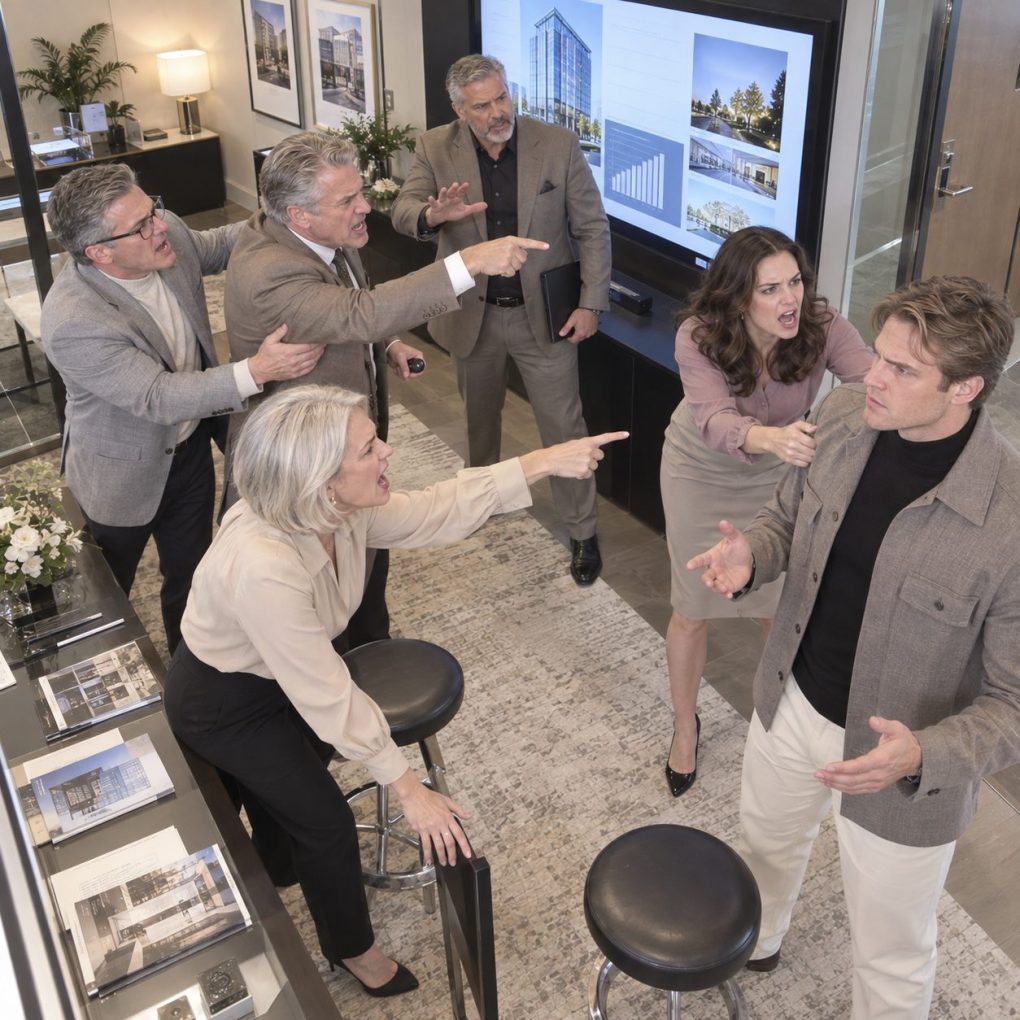
Across the table, Mercer’s attorney reviewed the final paperwork. Dad kept interrupting with jokes about retirement houses and boats. My younger brother Tyler whispered, “Bet you regret leaving now.”
Then Mercer’s CEO, Amanda Brooks, closed the folder.
“There is one matter we need to clarify before signatures.”
Dad leaned back. “Another warranty provision?”
“No.”
She looked toward me.
“Yesterday afternoon, the senior secured debt against Hale Industrial changed ownership.”
Dad’s smile disappeared.
Amanda continued. “Mercer is purchasing the operating assets. We are not acquiring the debt.”
Dad frowned. “First Continental holds the debt.”
“Not anymore.”
She slid a document across the table.
Dad read the first page, then looked up sharply.
Amanda said, “The debt was purchased through Northline Capital.”
My father looked at me.
Northline was my firm.
His mouth opened, but nothing came out.
I finally spoke.
Nobody moved for several seconds. Dad stared at me as if I had somehow broken into the room after sitting beside him for twenty minutes. Then he looked back at Amanda. “This is ridiculous. My son is an analyst.”
“Formerly,” I said.
Northline had promoted me eighteen months earlier. I now led a small restructuring team that specialized in troubled middle-market companies. When Hale Industrial’s loans appeared on the market at a discount, I disclosed my family connection immediately and removed myself from negotiations.
Northline’s investment committee made the decision independently.
They bought the debt because the collateral was worth more than the price the banks were willing to accept.
Dad pointed at me. “You bought my company.”
“No. Northline purchased debt owed by your company.”
“That’s the same thing.”
“It isn’t.”
Our attorney explained the distinction. Hale Industrial still belonged to Dad and his shareholders. But Northline now controlled the senior loan agreements, including rights connected to collateral, missed covenants, and the restructuring required after the Mercer sale.
Dad’s face turned red.
“You planned this.”
I shook my head. “You created this situation when you borrowed against almost every asset you owned.”
Tyler jumped in. “You’re enjoying this.”
I wasn’t.
That was the worst part.
I remembered Dad teaching me to use a socket wrench when I was nine. I remembered riding beside him on delivery runs before the company became successful. Watching him lose control of what he built did not feel like revenge.
But neither did I intend to pretend the numbers weren’t real.
Amanda brought the meeting back to the transaction. Mercer still wanted the divisions. The purchase price remained unchanged. But the proceeds would now go into a controlled account and be applied according to the loan agreement.
Dad slammed his hand against the table.
“That money belongs to Hale.”
Our attorney answered calmly. “Hale owes more than the sale produces.”
The room went silent again.
Dad turned toward me.
“How much?”
“After closing costs and taxes, the sale leaves roughly eleven million dollars available.”
“And the debt?”
“Seventeen-point-eight.”
For the first time all morning, Dad looked old.
Tyler whispered, “So what happens now?”
I explained that Northline was prepared to restructure the remaining balance rather than force liquidation.
Dad laughed bitterly.
“Let me guess. My son gets to decide whether I keep my company.”
“No.”
I slid another document toward him.
“You decide whether you keep it.”
The restructuring proposal gave Dad three choices.
He could reject it and risk foreclosure on the remaining collateral. He could sell the rest of the company immediately. Or he could accept a five-year plan that reduced his ownership, required outside financial oversight, and prohibited new borrowing without approval.
Dad hated every option.
He spent forty minutes arguing.
He accused Northline of exploiting him, Mercer of taking advantage of weakness, and me of humiliating him publicly. Eventually, Amanda said, “Richard, nobody in this room created your leverage.”
That ended the shouting.
The Mercer sale closed that afternoon.
Dad signed the restructuring agreement three days later.
For the first time in decades, Hale Industrial hired a real chief financial officer instead of letting Dad make every financial decision himself. Two unprofitable branches were closed. Executive bonuses were suspended. Tyler lost the company-paid truck he had been driving.
He blamed me for that too.
The business survived.
Six months later, cash flow was positive for the first time in nearly two years.
Dad and I barely spoke during that period.
Then one evening, he appeared at my apartment without calling.
He looked around my small living room and said, “I always assumed you were making more money than this.”
“I am.”
He frowned.
“Then why live here?”
“Because I don’t need a bigger place.”
He sat down.
For several minutes, neither of us said anything.
Then he admitted something I never expected.
“When you warned me about the debt, I knew you were probably right.”
I stared at him.
He continued. “But you were twenty-nine. I had built the company before you could drive. I couldn’t stand the idea that my kid understood something about my business better than I did.”
That confession mattered more than an apology.
Still, he gave me one.
“I made you the problem because I didn’t want the problem to be me.”
I accepted it.
I did not return to Hale Industrial.
Northline assigned another executive to oversee the investment because of my relationship with Dad, and I moved on to different deals.
Two years later, Hale paid down enough debt to refinance normally. Dad remained a minority owner instead of the unquestioned boss he had once been.
At the refinancing dinner, he introduced me to a banker.
“This is my son,” he said.
I waited for the usual joke.
It never came.
Instead, he added, “He saw the numbers before I did.”
I smiled.
That was all I had ever wanted him to understand.