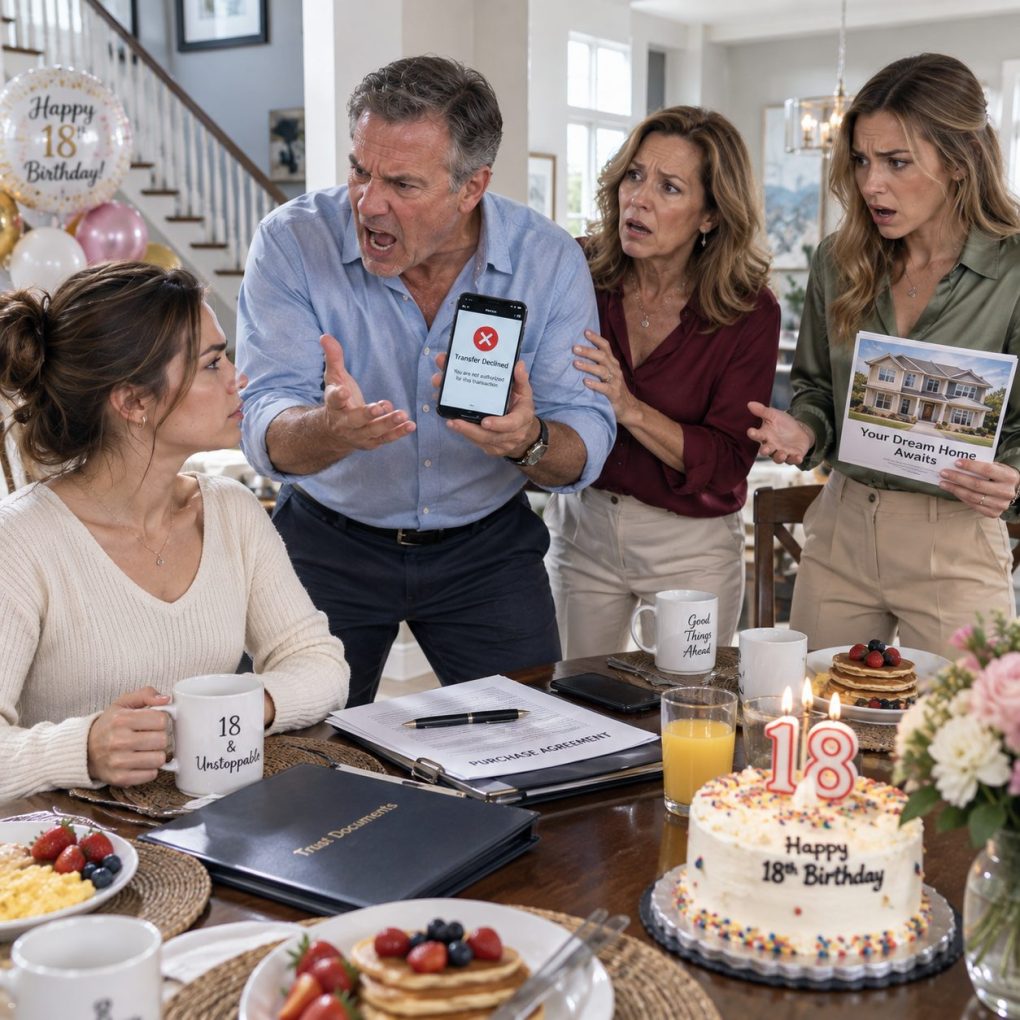
“Thank you for my house!” my sister, Brielle, squealed, wrapping both arms around me before I had even touched my pancakes. It was 8:06 a.m. on my eighteenth birthday in our house outside Denver, Colorado. I went still. “What house?”
Mom smiled over her coffee. “We wanted it to be a surprise.” Dad slid a glossy real-estate brochure across the table. On the cover was a four-bedroom house in Cherry Creek with a stone fireplace, rooftop deck, and a price circled in blue: $1,180,000.
Brielle bounced in her chair. “It has a dressing room. And Dad said the downstairs suite can be my studio.” She was twenty-four, recently engaged, and had spent the last year complaining that renting was “throwing money away.”
I looked at Dad. “Who’s paying for it?” He did not blink. “Your inheritance. Grandma left you more than enough. Family money should help the family.” Then he pushed a purchase agreement toward me. His signature was already on the buyer line.
For twelve years, the $3 million Grandma Ruth left me had been held by FrontRange Trust Company. My parents were never beneficiaries, but Dad had acted as family contact while I was a minor. Everyone assumed the money would be distributed directly to me when I turned eighteen.
Everyone except Grandma’s attorney, Celeste Ward. Three months before my birthday, she asked me one question: “Do you want access, or do you want protection?” She showed me emails Dad had sent the trust company asking how quickly the funds could be wired after midnight.
At 11:58 the night before, after weeks of meetings, I had signed instructions continuing the inheritance inside a new irrevocable beneficiary trust. I could receive education, housing, and reasonable distributions, but principal transfers over $25,000 required an independent trustee’s approval. Dad had no authority at all.
I took a sip of coffee. My hands were cold, but my voice came out steady. “You might want to call the realtor.”
Dad laughed once. “Cute.” Then his phone buzzed. He glanced down, and the color left his face. FrontRange had rejected a $240,000 earnest-money wire requested under his name and flagged the transaction for review.
Mom’s smile disappeared. Brielle stared at him. “Dad?” I folded the brochure closed. “The inheritance isn’t in my checking account. It never will be. And whatever you signed using my money, you signed without permission.” The kitchen went silent except for the refrigerator motor. For the first time that morning, nobody was celebrating.
Dad stood so fast his chair scraped the tile. “You had no right to change anything without us.” Celeste’s warning came back to me: People sometimes confuse access to your life with ownership of it. “I’m the beneficiary,” I said. “It was my decision.”
Mom’s face tightened. “You’re eighteen. You don’t understand money.” That would have landed harder if they had not just tried to spend more than a million dollars of mine before breakfast.
Dad called the realtor on speaker. The agent, sounding suddenly formal, explained that the contract named Dad as purchaser but required proof of funds within twenty-four hours. Without the promised wire, the seller could terminate and keep whatever valid deposit Dad had personally provided.
Brielle’s eyes snapped toward him. “You said it was already done.”
Dad muted the call. “It would have been, if she hadn’t pulled this stunt.”
That sentence broke something cleanly inside me. Not because he was angry, but because he still believed stopping an unauthorized transfer was the wrongdoing.
At 9:14, Celeste arrived with FrontRange’s trust officer, Martin Cho. I had asked them to come before breakfast because I suspected Dad might try something. Neither raised their voice. They simply placed copies of the trust amendment, wire rejection, and Dad’s emails on the table.
Martin explained that FrontRange had never authorized Dad to pledge, transfer, or promise my inheritance. Any representation otherwise was his responsibility. He also told Dad that the attempted wire had triggered an internal review because the request came from an old family-contact profile rather than an authorized trustee.
Mom sat down slowly. Brielle began crying—not about me, but about losing the house. “What am I supposed to tell Connor?”
I looked at her. “Tell him the truth. You were promised something that wasn’t yours.” Nobody answered. Outside, the birthday balloons Dad had tied to the mailbox kept knocking together in the wind.
The Cherry Creek deal collapsed that afternoon. Dad had paid a $10,000 deposit from his own savings, and because he could not produce the required proof of funds, the seller terminated under the contract terms. He blamed me for losing the deposit until Celeste asked one quiet question: “Who authorized you to spend her money?” He stopped answering.
FrontRange’s review found no missing funds. Dad had tried to move money he never controlled, relying on the assumption that once I turned eighteen, I would sign whatever he put in front of me. That mattered to me. The betrayal was not that he had stolen millions. It was that he had built a plan around my obedience.
I moved out two weeks later. The trust paid the security deposit and first year’s rent on a small apartment near the University of Colorado Denver, an expense Martin approved because I was starting college. I bought secondhand furniture myself. The first night, I ate pizza on the floor and listened to nobody tell me what my money was “for.”
Mom called almost every day at first. Her messages swung between anger, guilt, and warnings that I was “letting lawyers divide the family.” I finally told her I would talk when she could discuss what happened without pretending the problem was my trust. Three weeks passed before she called again.
Brielle surprised me. She showed up at my apartment without Connor and without asking for money. “I was awful,” she said before I could invite her in. She admitted Dad had spent months telling her Grandma’s inheritance was basically family property and that I had “more than I could ever need.” She had wanted to believe him because the house was beautiful.
I did not excuse her. “You thanked me for a million-dollar house before asking whether I wanted to give you one.” She stared at the carpet and nodded. “I know.” Then she handed me the glossy brochure from my birthday breakfast. Across the front, she had written in black marker: NOT MINE.
Dad took longer. Six months later, after Mom began seeing a counselor on her own, he asked to meet at a diner. He did not bring paperwork. He did not mention the deposit. He said, “I convinced myself Grandma trusted me to decide what was fair.” I reminded him Grandma had created a trust precisely so no one else could decide that for me.
For once, he did not argue. He apologized—not for “how things turned out,” but for treating my inheritance as leverage and my adulthood as a technicality. I told him forgiveness would not restore financial access. He said he understood. I believed him only after a year of watching his behavior match the sentence.
The trust remained in place. It paid tuition, health insurance, and eventually part of the down payment on a modest townhouse after I graduated. I never bought a sports car or a mansion. Martin taught me investing, taxes, insurance, and why wealth without boundaries can turn every relationship into a negotiation. Grandma’s gift became less exciting and far more useful.
Brielle and Connor eventually bought their own place—a two-bedroom fixer-upper forty minutes outside Denver. At their housewarming, she hugged me and whispered, “This one actually is mine.” I laughed. Dad carried in folding chairs. Mom brought pie. Nobody asked what my trust was worth. That was the real inheritance Grandma had protected: not three million dollars, but my right to decide what belonged to me, what I chose to share, and whether love could survive hearing the word no.