The bank called me at 8:12 on a Monday morning and asked when I planned to make the three overdue payments on my $529,000 mortgage. I actually laughed because I thought they had the wrong person. Then the collector read my full name, date of birth, and the address of a house in Scottsdale, Arizona, that I had never seen.
I lived in Denver and rented a two-bedroom apartment. I had never applied for a mortgage, never toured a house in Arizona, and certainly never borrowed half a million dollars. When I said that, the woman’s voice changed immediately. She transferred me to the bank’s fraud department.
By noon, I had a copy of the loan file. The mortgage listed me as a co-borrower with my younger sister, Kimberly. My income had been inflated by almost $40,000, and an electronic signature carrying my name appeared on documents dated seven months earlier.
Kimberly was thirty-one and had not held the same job for more than a year since college. Our parents had paid her rent, car insurance, credit cards, and even two previous apartment deposits. Whenever I questioned it, Mom said Kimberly simply “needed more support.”
I called my father first. He went silent for several seconds before saying, “Don’t panic. It’s just paperwork.” My stomach dropped because innocent people do not describe a fraudulent $529,000 mortgage as paperwork.
Then Mom took the phone. She admitted they had “helped Kimberly qualify” because the lender would not approve her income alone. She said they planned to make every payment until Kimberly’s finances improved, so I was never supposed to be affected.
“You put a mortgage in my name without asking me?” I said. Dad snapped that the house would eventually increase in value and told me I should be grateful they had included me in a family asset.
I immediately froze my credit with all three bureaus, filed an identity-theft report, and sent the lender a written fraud dispute. Then I called an attorney who specialized in mortgage and financial fraud. He told me not to sign, promise, or pay a single dollar.
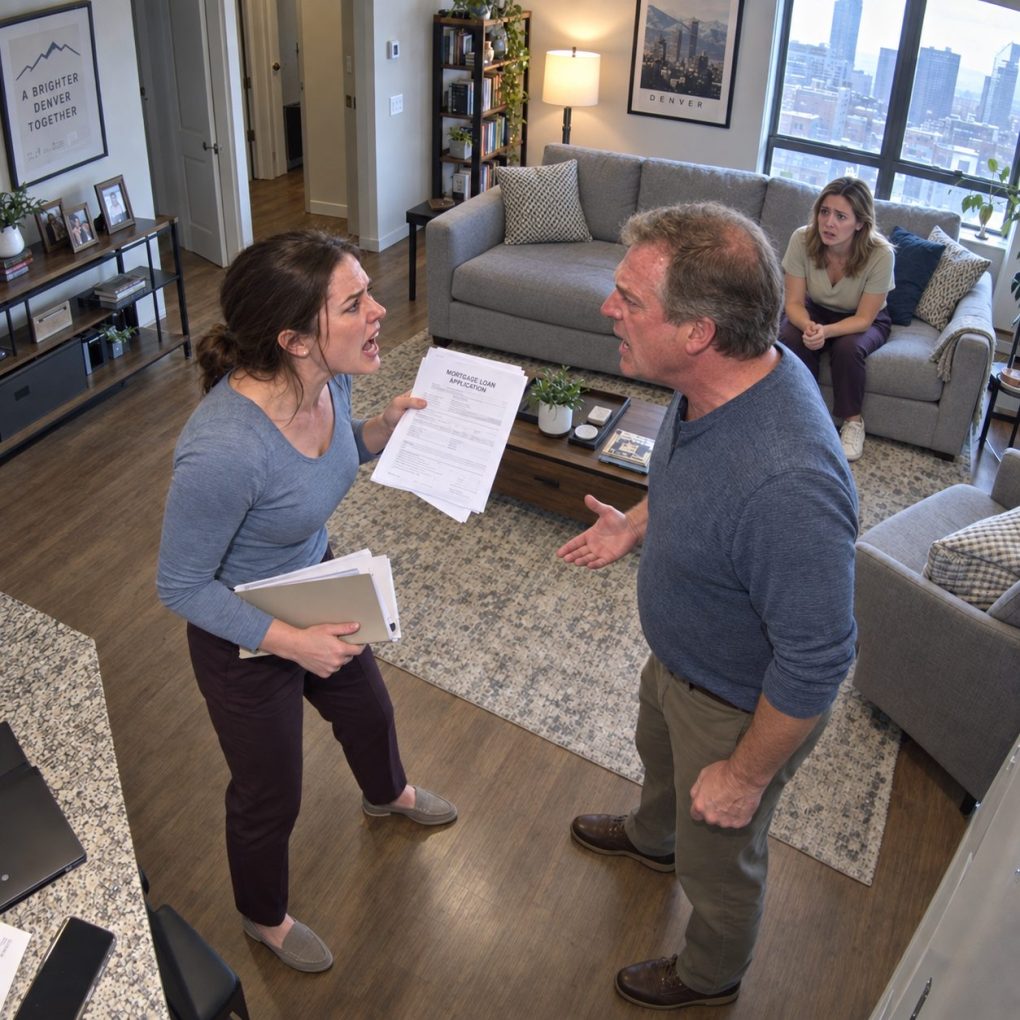
That evening, my parents and Kimberly showed up at my apartment. Kimberly cried that reporting the loan could make her lose the house. Mom begged me to withdraw the fraud claim before the bank “made this bigger than it needed to be.”
I placed a copy of the loan application on the table and said, “I already asked the bank to preserve the closing records, IP logs, and notary file.” Dad’s face went pale. Mom stopped crying, and Kimberly whispered, “What notary file?”
The answer arrived two days later. The closing had supposedly been completed remotely, with electronic signatures followed by a notarized identity verification. According to the file, I had joined a video session from my parents’ home in Colorado Springs at 3:46 on a Wednesday afternoon.
There was one problem. At 3:46 that afternoon, I had been giving a presentation at my company’s Denver office in front of fourteen people. My building-access logs showed me entering at 8:03 that morning and leaving after six. My employer also had the conference-room recording.
The lender’s fraud investigator asked whether anyone in my family had copies of my driver’s license or Social Security number. My parents had both. Years earlier, they had helped me complete financial-aid paperwork and kept copies in an old household file.
Then the investigator found something worse. The email used to create my mortgage portal differed from mine by one letter. The recovery phone number belonged to my mother, and several login attempts traced back to the internet connection at my parents’ house.
Kimberly called me crying that night. She admitted she knew my income had been added to the application, but claimed Dad told her I had agreed to co-sign. She said she never saw me sign anything and assumed our parents had handled it with me privately.
I asked whether she ever called to thank me for supposedly risking my credit on a $529,000 loan. She had no answer. Silence stretched between us until she finally whispered, “I guess I didn’t want to ask too many questions.”
The bank temporarily suspended collection against me while reviewing the fraud claim. It also stopped treating my disputed liability as an ordinary delinquency. My attorney warned me that removing my name permanently would require evidence, not just family accusations.
That evidence kept accumulating. The remote-notary provider preserved the video session. The person appearing on camera was not me; it was my father sitting beside a laptop while someone held my driver’s license toward the camera.
The notary had apparently failed several verification procedures. The lender referred the matter to its legal department and the notary company opened its own investigation. Suddenly, my parents stopped calling me.
A week later, Dad finally texted: “You didn’t need to destroy the family over this.” I replied with one sentence: “I didn’t put my child’s identity on a half-million-dollar loan.” He never answered.
The mortgage did not disappear overnight. For nearly four months, attorneys, the lender, title representatives, and investigators reviewed signatures, device records, identity documents, and the remote closing. I learned how slowly institutions move when the paperwork says one thing and the evidence says another.
Eventually, the lender formally concluded that I had not authorized the loan. My obligation was removed, the delinquency was corrected with the credit bureaus, and the bank pursued recovery through the parties actually involved in the transaction. My credit took time to normalize, but the $529,000 debt was no longer mine.
Kimberly could not afford the house without the fraudulent co-borrower income. After negotiations failed, she sold it before foreclosure became necessary. The sale covered most of the outstanding balance after costs, though she walked away with almost nothing.
She blamed our parents at first. Then, during one long conversation, I reminded her that she had accepted a house she knew she could not qualify for by herself. She eventually admitted she had chosen not to ask questions because the answer might have stopped her from getting what she wanted.
My parents faced consequences too. The lender referred the falsified documents and identity information to the appropriate authorities, and the remote-notary issue became part of the investigation. Their attorney advised them to stop contacting me about the case.
Mom wrote me a six-page letter. She described everything they had done as an attempt to give Kimberly “the same stability” I had built for myself. What she never explained was why giving my sister stability required putting mine at risk.
Dad’s apology was shorter. He said he had convinced himself that because I earned more and had good credit, I could absorb the risk if something went wrong. Reading that sentence clarified decades of family behavior in a way no argument ever had.
They had always treated Kimberly’s problems as emergencies and my competence as a resource. If she needed rent, I was expected to help. If she needed a house, apparently my identity itself became available.
I stopped speaking to my parents for almost a year. Kimberly and I eventually rebuilt limited contact after she found steady work and began managing her own finances. Trust returned slowly because apologies are easier than changed behavior.
The morning the bank called, I thought someone had made an administrative mistake. By the end, I understood the real mistake had been my parents believing that the responsible daughter would quietly carry one more burden. Their faces turned pale when they realized this time I had not carried it—I had documented it.