At 8:17 on the morning of my thirtieth birthday, my mother texted me to ask whether I could send my sister $12,000.
She didn’t say happy birthday.
Neither did my father.
And somehow, that wasn’t even the part that hurt most.
My name is Claire Bennett, and for most of my life, I had been the daughter my parents never worried about because I never gave them a reason to.
I paid my own way through college, built a career in corporate finance, rented a modest apartment in Columbus, Ohio, and rarely asked anyone for help.
My younger sister, Megan, lived very differently.
She changed majors three times, borrowed money constantly, and eventually opened a boutique fitness studio that my parents treated like a family achievement.
When Megan struggled, everyone gathered around her.
When I struggled, everyone assumed I would figure it out.
Birthdays had become a perfect example.
At twenty-eight, my parents forgot because Megan was moving apartments.
At twenty-nine, they remembered three days late because Megan had broken up with her boyfriend.
So when thirty arrived and my phone stayed silent, I told myself I wasn’t surprised.
That evening, I did something completely out of character.
I drove to the dealership where I had spent weeks negotiating on a metallic gray Audi A5 I could comfortably afford after years of saving.
The price was just under $58,000.
I took one picture beside it, smiling harder than I actually felt, and posted it on Facebook.
Happy Birthday To Me.
I expected a few coworkers to tease me and maybe some old college friends to leave comments.
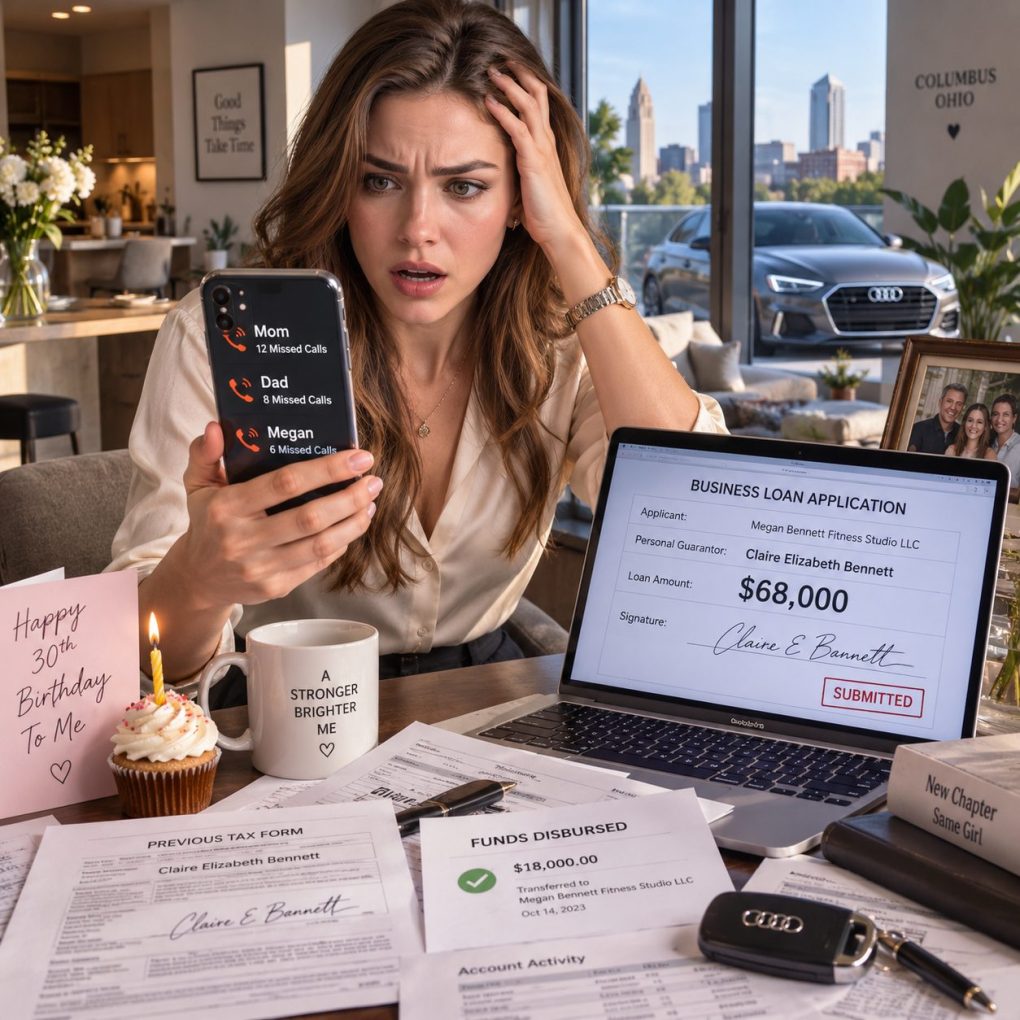
Instead, within fifteen minutes, my phone started vibrating almost continuously.
Mom called first.
Then Dad.
Then Megan.
Then Mom again.
For one ridiculous second, I thought they had finally noticed what day it was.
Mom destroyed that hope within ten seconds.
She wasn’t calling to apologize for forgetting my birthday.
She wanted to know whether I had really spent almost sixty thousand dollars on a car when Megan was “about to lose everything.”
Apparently Megan’s studio was behind on rent, payroll, equipment financing, and several vendor accounts.
The twelve thousand dollars Mom had casually requested that morning was only the beginning.
Megan needed closer to thirty-five thousand.
My parents had already given her almost everything they could spare.
Now they had discovered that their supposedly ordinary, struggling older daughter had money.
Dad joined the call and immediately began talking about family responsibility.
He reminded me of vacations they had paid for when I was a teenager, my first used car, and the semester they helped with my dorm fees.
It was like listening to someone turn my entire childhood into an invoice.
I stayed remarkably calm.
I told them the Audi had nothing to do with Megan, and I would not be financing a business I had never been consulted about.
That was when Dad said something strange.
“You’re acting like you haven’t already agreed to help her.”
I actually laughed.
Then my phone buzzed with an email from him.
Attached was a six-page loan document from a regional lender.
Megan’s company appeared at the top.
But halfway down the first page was another name.
Mine.
Claire Elizabeth Bennett.
Listed as personal guarantor.
My stomach turned cold.
The application showed my income, my employer, my Social Security number, and an address I hadn’t used in almost five years.
Then I reached the final page.
There was a signature beside my name.
Not something vaguely resembling mine.
Not an obvious fake.
It was my actual signature.
And I suddenly knew exactly where they had gotten it.
It had been copied from a tax document I had signed at my parents’ kitchen table years earlier.
I stared at the screen while Dad kept talking.
Then I noticed something that made everything worse.
The loan application had been submitted two days before my birthday.
My parents hadn’t simply forgotten me.
While they were forgetting my birthday, someone in my family had been using my identity.
And according to the document in front of me, the money had already started moving.
I thought the worst betrayal was seeing my forged signature on a loan I had never agreed to. I was wrong. By the next morning, I would learn who had submitted the application, where the first transfer had gone, and why my birthday had suddenly become very important to everyone in my family.
I barely slept.
By 7:30 the next morning, I had frozen my credit with all three bureaus and called the lender listed on the documents.
The representative transferred me to their fraud department almost immediately.
That was the first sign this was bigger than a desperate family argument.
The second came when the investigator told me the credit line wasn’t for $35,000.
It was for $68,000.
Someone had requested nearly twice what my parents had told me Megan needed.
Eighteen thousand dollars had already been transferred into Megan’s business account.
Another twenty-five thousand was scheduled for release that Friday.
I told the investigator I had never signed anything.
Her tone changed instantly.
She began asking questions about old addresses, email accounts, phone numbers, and whether my parents had ever possessed copies of my financial documents.
Unfortunately, they had.
For years, my parents had stored old tax returns, college paperwork, insurance records, and copies of family identification inside a filing cabinet at their house.
Then the investigator mentioned the email address used to verify the application.
I recognized it immediately.
It belonged to my mother.
That should have settled everything.
It didn’t.
Around noon, Megan arrived at my apartment crying so hard that my building manager almost refused to send her upstairs.
She insisted she had believed I knew about the loan.
Mom and Dad had told her I had privately agreed to become an investor because I was embarrassed about having more money than the family realized.
I wanted to believe Megan.
Then she admitted something else.
She had already spent part of the transferred money.
She had paid overdue rent and several employees.
But she swore she had never seen the actual loan application.
For the first time, Megan looked less like the favored daughter and more like someone who had finally realized how many lies had been built around her.
Then my phone rang.
It was the fraud investigator.
She had found evidence connected to the electronic application.
The loan had been submitted from an internet connection associated with my parents’ house.
The identity verification questions had also been answered correctly on the first attempt.
But there was something stranger.
The lender had required access to a bank account bearing my name to confirm ownership.
I told her I had never connected any account.
She gave me the last four digits.
I recognized them.
It was an old savings account my parents had opened for me when I was sixteen.
I had forgotten it existed.
Apparently, they hadn’t.
The account was still active.
And someone had been moving money through it for years.
The investigator could only tell me one additional fact before the case was formally escalated.
The deposits did not come from my salary.
They came from my parents.
And the withdrawals went somewhere I never expected.
Most of them were connected to Megan.
But one large transfer, made eighteen months earlier, had gone to an account bearing a completely different name.
When I read the name, I stopped breathing.
It belonged to my late grandmother.
She had been dead for almost three years.
My grandmother, Evelyn Bennett, had been the one person in my family who never treated independence like an excuse to ignore me.
She remembered every birthday.
She mailed handwritten cards even after I moved only twenty minutes away.
And when she died, my parents told Megan and me that she had left behind very little.
Her house had supposedly been sold to cover medical expenses.
Her remaining savings, according to Dad, had barely paid funeral costs.
I never questioned it.
Grief had made money seem unimportant.
Now I was staring at a bank transfer connected to her name eighteen months after her death.
Megan sat beside me on my couch while I called the bank that held my forgotten teenage savings account.
Because my father had originally been listed as joint custodian when I was a minor, untangling the account history took several calls.
Eventually, a fraud specialist confirmed what I feared.
My father’s access had never been removed.
For years, my parents had occasionally deposited money into the account and withdrawn it again.
The activity had kept the account alive.
More importantly, it had created something they could point to as evidence of an ongoing financial relationship with me.
That was how they had helped convince the lender that the loan application was legitimate.
But the transfer bearing Grandma’s name was different.
It wasn’t actually from an account she controlled after death.
The description had been manually entered.
The money had come from an estate account Dad had once administered.
I felt sick.
Megan went completely silent.
Until that moment, she had still been clinging to the possibility that our parents had made one terrible decision because her business was failing.
Now it looked planned.
And older than her studio.
That afternoon, I contacted an attorney named Rebecca Sloan, who specialized in consumer fraud and financial disputes.
She told me to stop arguing with my family immediately.
No more accusations.
No threats.
No emotional phone calls.
Save everything.
So I did.
I downloaded every text message from Mom and Dad.
I saved the email containing the loan documents.
I copied voicemail recordings.
I printed bank statements.
I pulled old tax filings and discovered exactly where my forged signature had originated.
The image matched a signature from my 2021 state tax authorization almost perfectly, including a small upward stroke I had stopped making years earlier.
Someone hadn’t imitated me.
They had copied me.
Rebecca helped me file an identity theft report and submit formal fraud disputes to the lender and credit bureaus.
The lender froze the remaining $50,000 immediately.
Megan’s studio account was temporarily restricted while investigators traced the first disbursement.
That was when my parents stopped pretending this was a misunderstanding.
Mom came to my apartment the next evening.
I watched her through the security camera without opening the door.
For nearly fifteen minutes she alternated between crying, apologizing, and insisting that involving investigators would “destroy the family.”
She never once said they hadn’t done it.
Dad took a different approach.
His voicemail was furious.
He said I was humiliating them over paperwork that could have been fixed privately.
Then he made the mistake that changed everything.
He said they had only used my information because they knew I would eventually agree.
Rebecca listened to that recording twice.
“Keep that,” she told me.
Three days later, Megan closed the studio temporarily.
She also gave investigators full access to the company’s bookkeeping.
That decision turned out to matter.
The records showed that Megan had been financially irresponsible, but she had not created the fraudulent loan application.
She had known my parents were trying to raise money.
She had even allowed herself to believe their story that I had quietly agreed to help.
But the emails told a darker story.
Mom had repeatedly told Megan not to contact me directly because I supposedly wanted the arrangement kept confidential.
Dad had written that I was “sensitive about money.”
They had built an entire fictional version of me to prevent Megan from asking the one question that would have exposed them.
When did Claire agree to this?
She never had.
Then investigators began reviewing the old estate account.
That was where the final secret came out.
Grandma had not died nearly broke.
She had created modest inheritances for both granddaughters.
Nothing life-changing.
But enough to matter.
Megan and I had each been meant to receive $24,000.
Dad had been responsible for distributing the funds after certain estate expenses were settled.
Megan had received hers indirectly.
She just hadn’t known it.
Over two years, our parents had used almost all of her inheritance to pay her rent, debts, car repairs, and eventually startup costs for the studio.
Every time Megan thought Mom and Dad were rescuing her with their own money, much of it had actually been hers.
Mine was worse.
My $24,000 had never reached me at all.
Most of it had remained in the estate account until Dad transferred it into the old savings account that carried my name.
Then, over time, my parents moved the money out.
Some covered Megan’s expenses.
Some covered their own.
That explained the mysterious transfer.
The money had been labeled with Grandma’s name because it was part of my inheritance.
The savings account had essentially become a laundering point inside the family.
Not laundering in the dramatic television sense.
Something quieter.
More ordinary.
And somehow more painful.
My parents had convinced themselves that because they controlled the accounts, they controlled the money.
When Rebecca presented the evidence to their attorney, the tone of every conversation changed.
Suddenly nobody was talking about family loyalty.
They were talking about repayment.
Documentation.
Liability.
Settlement.
The lender ultimately removed me from responsibility for the fraudulent credit line after completing its investigation.
The initial $18,000 disbursement became part of a separate recovery process involving Megan’s business and my parents.
My credit report was corrected.
The fraudulent inquiry disappeared.
But the inheritance issue remained.
My parents eventually agreed to repay the $24,000 that should have gone to me, plus legal expenses tied directly to recovering it.
They did not have the cash readily available.
Dad sold the fishing boat he had bought the previous summer.
Mom cashed out a certificate of deposit.
They also refinanced part of their debt.
For years, they had told me money was tight whenever I needed anything.
Watching them suddenly find resources when lawyers became involved taught me something I probably should have learned much earlier.
People reveal priorities differently when consequences arrive.
Megan’s studio never fully recovered.
She eventually shut it down.
For the first time in her adult life, my parents couldn’t rescue her.
And surprisingly, that became the beginning of something healthier for her.
She took a management job at a wellness center outside Columbus and started paying off the legitimate debts in her own name.
She also began therapy.
Months later, she asked to meet me for coffee.
I almost said no.
Then I remembered that she had cooperated when cooperation actually cost her something.
So I went.
Megan apologized without defending herself.
She admitted she had enjoyed being the daughter everyone rushed to save.
She admitted she had rarely questioned where the money came from because questioning it might have meant losing it.
That confession hurt.
But it was also the first truthful thing either of us had ever said about our family dynamic.
I told her forgiveness was not the same as returning to the old relationship.
She understood.
We started slowly.
Birthday messages.
Occasional lunches.
No loans.
No shared accounts.
No secrets involving money.
My relationship with my parents was different.
I stopped speaking to them for almost a year.
There was no dramatic declaration.
I simply stopped participating in the cycle.
When Mom sent guilt-filled messages about holidays, I didn’t argue.
When Dad complained that strangers now knew “private family business,” I didn’t defend myself.
Their embarrassment was not my emergency.
On my thirty-first birthday, I woke up expecting the day to feel strange.
Instead, it felt quiet.
Megan sent me a card and a small plant.
A few friends took me to dinner.
My coworkers surprised me with cupcakes.
Nothing extravagant happened.
And I loved every minute of it.
That evening, I drove home in the same Audi that had accidentally exposed everything.
For months, I had considered selling it.
The car reminded me of the Facebook post, the phone calls, the forged signature, and the ugliest year my family had ever experienced.
But eventually I realized the car hadn’t caused any of it.
It had simply revealed what was already there.
My parents had spent years believing that because I didn’t ask for help, I didn’t need consideration.
Because I earned my own money, mine was available whenever someone they worried about more needed rescuing.
Because I rarely complained, my boundaries seemed optional.
Turning thirty changed that.
Not because I bought an expensive car.
Not because lawyers got involved.
Not even because I recovered the money Grandma intended for me.
It changed because I finally stopped measuring love by how much disrespect I could tolerate without leaving.
A week after my thirty-first birthday, a Facebook memory appeared on my phone.
It was that photograph of me beside the Audi.
Happy Birthday To Me.
I stared at it for several seconds.
Then I noticed something I hadn’t remembered.
In the picture, I looked genuinely happy.
Before the calls.
Before the fraud.
Before I knew anything.
For years, I had assumed that photo captured the last peaceful moment before my family fell apart.
Now I saw it differently.
It was the first picture of the version of me who had finally built a life that belonged entirely to herself.
So I didn’t delete it.
I changed the privacy setting to public.
And underneath my old caption, I added one sentence.
Best birthday gift I ever gave myself: learning that “family” is not permission to use me.