“My Son Slammed the Door in My Face When I Begged for Shelter — Then the Bank Manager’s Chair Fell Backward.”
The door slammed shut inches from my wheelchair.
“Mom, I can’t do this,” my son, Ethan, said through the locked door. “You need somewhere else to go.”
“I only need a few nights,” I pleaded. “I have nowhere left.”
His wife, Melissa, appeared behind the glass, arms crossed.
“We have two kids, Ethan has work, and this house isn’t a shelter.”
I stared at them through the window, trying not to cry. My hands were shaking so badly that I nearly dropped my overnight bag.
Three months earlier, my husband, Robert, had died unexpectedly. I had been recovering from surgery ever since, and the apartment we rented became impossible to manage on my disability check.
Ethan knew all of that.
Still, he turned away.
“Call a facility,” he said.
Then the curtains closed.
I spent that night in a cheap motel, staring at the ceiling and wondering how my own son could leave me outside like a stranger.
The next morning, while sorting through Robert’s old belongings, I found something tucked inside the lining of his worn leather wallet.
An old black bank card.
The name on it was Robert’s.
I almost threw it away.
Instead, something made me take it to the bank.
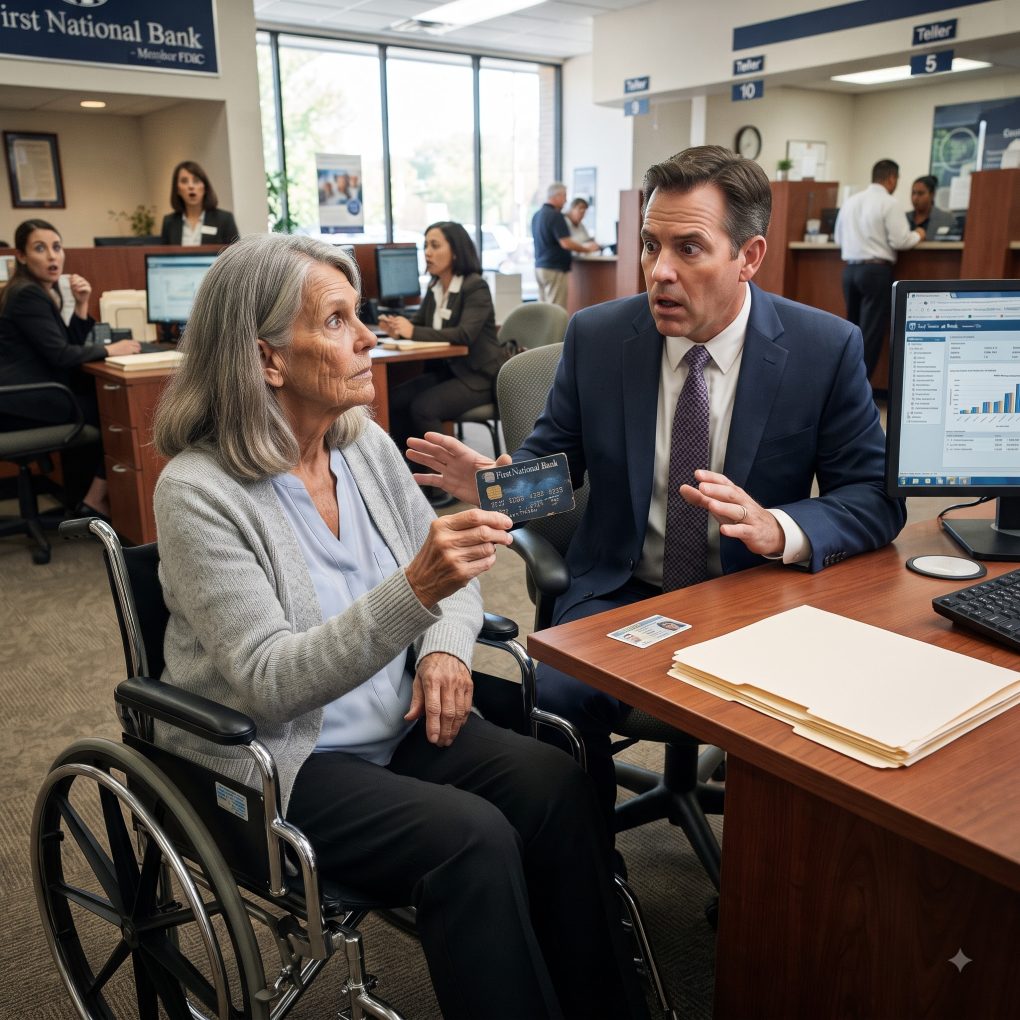
At the downtown branch, I handed the card to the manager, a gray-haired man named Mr. Collins.
He examined it.
Then he looked at me.
Then at the computer.
His expression changed completely.
“Ma’am,” he whispered.
He stood so quickly that his chair crashed backward.
“I need you to come into my office. Right now.”
I followed him slowly in my wheelchair.
He locked the door behind us.
Then he pulled a thick file from a cabinet and placed it on the desk.
“You said your husband died three months ago?”
“Yes.”
Mr. Collins opened the file.
“Then there’s something Robert never told you.”
He turned the first page toward me.
My breath caught when I saw the amount printed beside Robert’s name.
But the money wasn’t the only thing that shocked me.
At the bottom of the page was Ethan’s signature.
And beside it were three words that made my hands go cold—
“Beneficiary transfer approved.”
Teaser
I thought the bank had discovered money my husband had hidden from me. I was wrong. What Robert had left behind connected directly to the son who had just closed his door in my face—and the next document would force me to question everything I thought I knew about my husband’s final months.
I stared at Ethan’s signature until the letters blurred.
“That isn’t possible,” I whispered.
Mr. Collins sat across from me.
“I’m afraid it is.”
He turned another page.
The account had been opened fourteen years earlier under Robert’s name. It wasn’t a normal checking account. It was a protected investment account connected to a family trust.
The balance was just over $1.8 million.
I gripped the arms of my wheelchair.
“Robert never told me we had this.”
“He wasn’t required to,” Mr. Collins said carefully. “But after his death, ownership and beneficiary instructions became important.”
I pointed at Ethan’s signature.
“What did my son sign?”
Mr. Collins hesitated.
“Four months before your husband died, someone submitted paperwork requesting that the account’s beneficiary designation be changed.”
“To Ethan?”
“No.”
My stomach tightened.
“To Melissa?”
He nodded.
I felt like the room had tilted.
“Why would Robert leave nearly two million dollars to my daughter-in-law?”
Mr. Collins slid another document toward me.
“He didn’t.”
The beneficiary change had been rejected.
The signature on the form looked similar to Robert’s, but the bank’s verification system had flagged it.
Then came the part that made my hands tremble.
Someone had tried again two weeks later.
This time, the paperwork included Ethan’s signature as a witness.
“What happened?”
“We froze the account.”
“Why?”
“Because Robert had previously placed a restriction on withdrawals unless you personally appeared with identification.”
I stared at him.
“Me?”
“Yes.”
Mr. Collins opened a second file.
Inside was a handwritten note from Robert.
If Margaret ever comes to this bank alone, do not discuss this account over the phone. Show her everything.
My eyes filled with tears.
Robert had known something might happen.
Then Mr. Collins showed me the final document.
It was dated six weeks before Robert died.
It stated that if he became incapacitated or died, the $1.8 million would be transferred into a trust controlled by me.
But there was one condition.
I had to personally authorize the transfer.
“I don’t understand,” I said. “Why would Robert make it so complicated?”
Mr. Collins looked uncomfortable.
“Because someone had already attempted to take control of the account.”
“Who?”
He pushed forward a photocopy.
At the bottom was the name of a law office.
And beneath it was an appointment record.
Ethan had met that attorney three days before Robert’s death.
My heart sank.
“Does my son know about this account?”
Mr. Collins didn’t answer immediately.
Instead, he pointed toward the glass doors of the bank.
A man was standing outside.
Ethan.
He was staring directly at me.
And beside him was Melissa.
My son raised his phone.
Then my phone buzzed.
One message appeared:
Mom, leave the bank. We need to talk before you do something you’ll regret.
Mr. Collins quietly locked the office door again.
“Ma’am,” he said, “whatever you do, do not leave with them.”
Then he opened Robert’s final envelope.
Inside was a photograph.
And on the back, Robert had written a sentence that changed everything:
If Ethan comes looking for this money, ask him what happened the night I went to the hospital.
I read Robert’s handwriting three times.
If Ethan comes looking for this money, ask him what happened the night I went to the hospital.
My chest tightened.
For weeks after Robert died, I had tried not to question anything.
The doctors had said his heart condition had suddenly worsened. Ethan had handled most of the arrangements because I was recovering from surgery and could barely move without assistance.
I trusted my son.
Now I wasn’t sure what I had trusted.
Mr. Collins pulled the photograph from the envelope.
It showed Robert sitting at a kitchen table with two folders in front of him.
The date printed in the corner was six weeks before his death.
“Your husband gave this to the bank,” Mr. Collins explained. “He also gave us instructions that we were not to open the sealed envelope unless you appeared in person.”
“Why?”
“Because he believed someone close to him was trying to gain access to his finances.”
I looked toward the glass doors.
Ethan and Melissa were still waiting.
My son had always been the person I called when something went wrong.
Now he was standing outside the bank, waiting for me to surrender something I hadn’t even known existed.
“Can I call the police?” I asked.
“You can,” Mr. Collins said. “But first, I recommend you hear the entire record.”
He placed another folder on the desk.
Inside were transaction histories.
For nearly eighteen months, Robert had been moving money from his business account into the protected trust.
The deposits totaled more than $1.8 million.
But there was another pattern.
Several large withdrawals had been attempted from his regular accounts.
Most had been declined.
One had succeeded.
The amount was $47,500.
The recipient was a company called EM Property Solutions LLC.
I recognized the name.
“That’s Ethan’s company.”
Mr. Collins nodded.
The room went silent.
“I never authorized that.”
“I know.”
He showed me the transaction authorization.
Robert’s signature was on it.
But beneath it was a handwritten notation from a bank employee:
Customer contacted bank afterward. Claims signature unauthorized.
I stared at the page.
“When did that happen?”
“Four weeks before Robert died.”
My stomach dropped.
“Did he report Ethan?”
“No. He simply asked us to secure the remaining assets.”
That sounded exactly like Robert.
He had always hated family conflict.
He would rather quietly protect everyone than accuse someone he loved.
But now the evidence was piling up.
Ethan had accessed money.
Someone had tried to change the trust.
Someone had used questionable signatures.
And Robert had left instructions specifically mentioning Ethan.
Mr. Collins finally opened the last sealed envelope.
Inside was a letter.
I recognized Robert’s handwriting immediately.
Margaret,
If you’re reading this, I couldn’t explain everything to you myself. I’m sorry.
My eyes filled with tears.
Ethan asked me for money several times. He said his business was failing. I helped him because he’s our son. But eventually, he stopped asking and started taking.
I covered my mouth.
The letter continued.
I discovered he and Melissa had been discussing your future without you. They believe that after I die, you will eventually have to sell the house and use the money for your care. They want control of the process.
I couldn’t breathe.
My house.
The small home Robert and I had paid off after thirty years.
The house Ethan had told me was “too much work” for me.
The house he had recently suggested I sell and move into assisted living.
Robert had known.
Then came the final paragraph.
I created the trust because I want you to have choices. Not because I don’t trust you. Because I know how easily people can make decisions for someone who is vulnerable.
Below that was one final sentence.
Do not give Ethan the account information. Not until you have an attorney of your own.
I lowered the letter.
“He knew.”
Mr. Collins nodded.
“He knew enough to protect you.”
A knock came against the office door.
Ethan’s voice followed.
“Mom? Open the door.”
I froze.
Mr. Collins stood beside me.
“Don’t answer.”
Another knock.
“Mom, this is ridiculous. You don’t understand what’s happening.”
Melissa spoke from the hallway.
“You’re being manipulated.”
I looked at Mr. Collins.
“By whom?”
He didn’t answer.
Then Ethan’s voice changed.
“If you don’t come out, I’m calling Adult Protective Services and telling them you’re being financially exploited.”
That sentence hit me harder than anything else.
He was threatening to accuse me of being incapable of handling my own money.
I suddenly understood why Robert had insisted on documentation.
This wasn’t just about money.
It was about control.
Mr. Collins called the bank’s security officer.
Ten minutes later, Ethan and Melissa were asked to leave.
Before Ethan walked away, he looked through the glass directly at me.
His expression wasn’t angry anymore.
It was frightened.
That was when I knew there was something else.
And I was determined to find it.
The next afternoon, I met with an attorney recommended by Mr. Collins.
Her name was Sarah Whitmore.
She reviewed the trust, the attempted beneficiary changes, the $47,500 transfer, and Robert’s letter.
Then she asked me a question.
“Did your husband have life insurance?”
“Yes.”
“Who received it?”
“I thought Ethan did.”
Sarah stopped reading.
“You thought?”
I nodded.
Robert had told me years earlier that Ethan would receive a modest life-insurance policy because he had children.
I had never seen the paperwork.
Sarah searched the database.
Then she looked up.
“Margaret, Ethan wasn’t the beneficiary.”
“Who was?”
She turned the screen toward me.
The beneficiary was me.
The entire $600,000 policy had been assigned to a trust for my benefit.
I stared at the screen.
Robert hadn’t simply left me money.
He had built layers of protection around me.
Sarah explained that Robert had apparently anticipated a period when I would be physically vulnerable and dependent on others.
The trust gave me control over the protected funds while limiting anyone else’s ability to access them.
But then Sarah found something else.
A notarized document had been submitted after Robert’s death.
It claimed that I had voluntarily given Ethan authority to manage my finances.
My signature appeared at the bottom.
I had never signed it.
Sarah immediately requested the notary record.
Two days later, the notary confirmed something important.
The signature had been notarized at an address I had never visited.
The witness listed on the document was Melissa’s brother.
That was the major break in the case.
The forged document wasn’t merely suspicious.
It was independently disproved.
Sarah reported the matter to the appropriate authorities and notified the bank to preserve every record.
Then Ethan finally came to my house.
He didn’t come alone.
He brought Melissa and a lawyer.
I was sitting in the living room when they entered.
Ethan looked exhausted.
“Mom, we need to talk.”
Sarah was already sitting beside me.
Ethan stopped when he saw her.
His lawyer glanced at the documents on the table.
“You hired counsel?”
“Yes,” I said.
Ethan’s face fell.
“I wasn’t trying to steal from you.”
Sarah didn’t respond.
I looked at my son.
“Then tell me why you tried to change your father’s trust.”
Silence.
“Tell me why $47,500 went from his account to your company.”
More silence.
“Tell me why someone forged my signature.”
Melissa suddenly began crying.
Ethan looked at her.
And that was when the truth finally came out.
Ethan admitted his business had been failing.
He had debts.
Payroll problems.
Creditors calling.
He said Robert had refused to give him more money after discovering the $47,500 transfer.
Melissa had convinced him that if I eventually sold the house and moved somewhere cheaper, they could help manage the remaining money.
They had planned to present themselves as my financial helpers.
Then Robert became suspicious.
Everything changed after that.
“I never meant for Dad to die,” Ethan said.
I stared at him.
“I know.”
He began crying.
“But you still made choices that put me at risk.”
He nodded.
“I know.”
For the first time since Robert died, I allowed myself to say what I had been too afraid to say.
“You closed the door on me when I needed my son.”
Ethan lowered his head.
“I was scared.”
“So was I.”
That silence hurt more than shouting ever could.
Eventually, the legal process continued.
The bank recovered the remaining funds.
The attempted transfers were blocked.
The forged authorization was removed from my records.
Ethan’s company was required to address the unauthorized transfer separately, and he had to cooperate with the investigation into the fraudulent documents.
I did not give him access to my finances.
But I also didn’t destroy the relationship immediately.
Forgiveness, I learned, wasn’t the same thing as trust.
Trust had to be rebuilt.
Months later, I moved into a smaller accessible home closer to the bank and my doctor’s office.
I hired a caregiver twice a week.
I set up my own accounts.
And I kept Robert’s old black card in a small wooden box beside his photograph.
Ethan eventually began visiting.
At first, he came for twenty minutes.
Then an hour.
He brought groceries.
He repaired a loose railing.
He never asked about money.
That mattered.
One afternoon, he sat beside me and said quietly, “Dad protected you better than I did.”
I looked at him.
“He protected me because he knew love wasn’t enough. People need boundaries, too.”
Ethan nodded.
“I wish I’d understood that sooner.”
“So do I.”
We sat quietly.
There was no magical reconciliation.
No instant repair.
Just two people finally facing the truth.
Robert’s money gave me security.
His documents gave me protection.
But his final lesson was worth more than either.
When someone is vulnerable, the people around them can easily start making decisions for them.
Even family.
Especially family.
And sometimes the most important thing a person can leave behind isn’t an inheritance.
It’s the ability to stand on your own when everyone else assumes you can’t.