My mother-in-law served everyone steak and seafood, then left my plate empty and said they had run out of food for me. My husband stayed silent. That night, I stopped paying their bills. Two days later, a bank folder exposed a $684,000 secret carrying my forged signature.
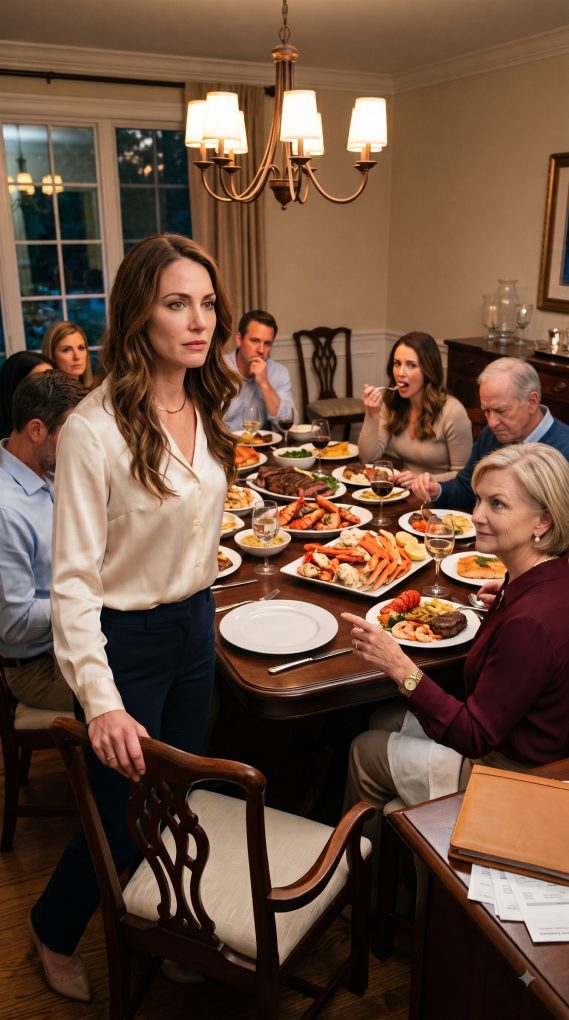
My mother-in-law looked directly at my empty plate, then at the trays of steak, crab legs, shrimp, and ribs covering the table.
“We’ve run out of food for you, Claire.”
Nobody laughed.
There was enough food to feed another ten people.
My husband, Ryan, stared at his plate and kept eating.
I waited for him to say something.
Anything.
Instead, Diane pushed the basket of garlic bread toward Ryan’s brother and said, “Some people should learn not to expect everyone else to provide for them.”
That nearly made me laugh.
For three years, I had paid the mortgage on Diane’s house whenever she was “short.” I covered her electric bill, internet, property insurance, and even the monthly payment on the SUV parked outside.
Ryan always called it temporary.
I looked at him.
“You’re really going to sit there?”
He lowered his voice.
“Claire, don’t start drama at Mom’s dinner.”
That was the moment something inside me went completely quiet.
I stood up, picked up my purse, and walked out.
Nobody followed me.
At home, I opened our banking app.
Mortgage autopay for Diane’s house.
Cancelled.
Electricity.
Removed my card.
Internet, insurance, SUV payment, family phone plan.
One by one, I stopped every payment that wasn’t legally mine.
Ryan came home after midnight.
“You embarrassed my mother.”
I closed my laptop.
“No. I stopped financing people who embarrass me.”
He stared at me like I had slapped him.
Forty-eight hours later, Diane called screaming.
But before I answered, an overnight envelope arrived from the bank.
Inside was a thick folder.
The first page contained my signature.
Except I had never signed it.
And beside my name was a loan balance of $684,000.
I thought walking away from that dinner had ended the humiliation. Instead, it exposed something far worse. Ryan had been strangely quiet for two days, Diane sounded terrified, and the bank folder contained documents I had never seen before. Then I turned to the second page. The rest of what happened is in the comments.I finished the story in the comments.Next part is under this post..
The second page listed the borrower.
Mercer Hospitality Group LLC.
I read the name three times.
I had never heard of it.
Ryan walked into the kitchen while I was still holding the folder.
His face changed immediately.
“Where did you get that?”
Not What is that?
Where did you get that?
My stomach tightened.
“Apparently the bank thinks I guaranteed a $684,000 loan.”
Ryan reached for the folder.
I pulled it away.
“Did you sign my name?”
“No.”
The answer came too quickly.
Then Diane called again.
Ryan looked at my phone.
“Don’t answer her.”
I did.
“Claire!” Diane shouted. “What did you do? The mortgage payment didn’t go through. The electric company emailed me. The insurance company called.”
“You told me there wasn’t enough food for me.”
“That was dinner. This is our home!”
“No, Diane. It’s your home.”
Her voice suddenly dropped.
“You don’t understand what you’re doing.”
I looked at Ryan.
“I’m beginning to.”
There was silence.
Then I heard Diane whisper to someone beside her.
“She has the papers.”
Ryan grabbed the phone and ended the call.
That frightened me more than the yelling.
I opened the folder again.
Mercer Hospitality Group had been formed eleven months earlier.
Ryan owned 55 percent.
Diane owned 20 percent.
His brother, Kyle, owned the rest.
The company had purchased a failing restaurant outside Columbus, renovated it with borrowed money, and opened another location that closed after four months.
There were unpaid vendors.
Credit cards.
Payroll taxes.
A commercial lease guarantee.
The total exposure was over $1.1 million.
Then I found my name again.
Claire Bennett Mercer.
Guarantor.
My signature appeared on six separate documents.
Every one was fake.
“You used me as collateral.”
Ryan shook his head.
“It wasn’t supposed to get this bad.”
That was not a denial.
I immediately called Rebecca Sloan, the attorney who had handled my father’s estate.
She told me not to sign anything, not to transfer money, and to photograph every page.
Then she asked one question.
“Claire, whose name is on Diane’s house?”
“Diane’s.”
Ryan suddenly looked away.
I stopped.
“At least I thought it was.”
Rebecca checked county records while we stayed on the phone.
Thirty seconds later, her voice changed.
“The house was transferred eight months ago.”
“To whom?”
“Mercer Hospitality Group.”
I stared at Ryan.
Diane hadn’t merely accepted my mortgage payments.
The family had transferred her house into their failing company and apparently continued letting me pay the debt tied to it.
But Rebecca wasn’t finished.
“There’s another filing.”
My hands went cold.
“What filing?”
“A home-equity line for $310,000.”
Ryan closed his eyes.
Rebecca continued.
“It lists you as co-borrower.”
I whispered, “I never signed that.”
“I know.”
Then she said the name of the notary.
Diane Mercer.
My mother-in-law had notarized my forged signature.
And according to the final page in the folder, almost the entire $310,000 had disappeared within six weeks.
What do you think will happen next? I’d love to hear your honest guess or reaction “I’d love to hear your opinions – your comments really make me happy and inspire me to keep writing.”
I looked at Ryan across the kitchen.
“Where did the $310,000 go?”
He didn’t answer.
Rebecca was still on speakerphone.
“Ryan,” she said calmly, “I suggest you think very carefully before you say anything.”
He stared at the floor.
“It went into the business.”
Rebecca replied, “That isn’t what the bank records show.”
Ryan’s head snapped up.
Apparently, the folder the bank sent me had been triggered by a compliance review after several payments suddenly stopped. Because my name appeared on multiple guarantees, the bank had mailed duplicate documentation to our home address.
Rebecca asked me to turn to the transaction summary near the back.
I found it.
The home-equity line had been drawn down in four large transfers.
$85,000.
$70,000.
$92,000.
$58,000.
Only $5,000 remained untouched.
Two transfers had gone to Mercer Hospitality Group.
The others had gone somewhere else.
Carter Development Services LLC.
“Who is Carter?” I asked.
Ryan said nothing.
Rebecca searched the state business database.
“Registered agent is Vanessa Carter.”
The name meant nothing to me.
Then Ryan sat down.
That told me everything before he spoke.
“Claire, this isn’t what you think.”
I actually laughed.
“You forged my signature, borrowed against your mother’s house, let me keep paying the mortgage, and sent money to a woman named Vanessa. Tell me which part I’m misunderstanding.”
“She was helping with the restaurants.”
Rebecca interrupted.
“Vanessa Carter is not listed as an employee, consultant, contractor, or investor.”
Ryan’s face went pale.
I turned to him.
“Who is she?”
Before he answered, someone started pounding on our front door.
It was Diane.
She stormed inside without waiting to be invited.
“You need to fix this immediately.”
I held up the folder.
“You notarized forged documents.”
Her expression changed.
“Ryan said you agreed.”
“Did you see me sign them?”
She hesitated.
That was enough.
“No.”
The room went silent.
Diane turned on Ryan.
“You told me Claire had already approved everything.”
Ryan stood.
“Mom, stop talking.”
Rebecca heard every word.
“Claire,” she said, “keep the documents somewhere safe. I’m coming over.”
Diane suddenly began crying.
Not angry crying.
Terrified crying.
She sat at my kitchen table and pressed both hands over her face.
“The restaurant was supposed to save us.”
“Save you from what?”
She looked at Ryan.
He shook his head.
I slammed the folder onto the table.
“From what?”
Diane finally answered.
“Debt.”
For years, Ryan had told me his mother occasionally needed help because her late husband had left her with unexpected expenses.
That story was only partly true.
Diane had already been carrying nearly $190,000 in credit-card debt and personal loans when Ryan convinced her that buying a restaurant could generate enough income to eliminate it.
Ryan had no restaurant experience.
Neither did Kyle.
But Vanessa Carter did.
She had worked with Ryan years earlier.
Together they created projections showing enormous profits within eighteen months.
The first restaurant lost money immediately.
Instead of admitting failure, Ryan borrowed more.
Then more.
When lenders stopped approving unsecured credit, they transferred Diane’s house into Mercer Hospitality Group so it could be used as collateral.
“And my signature?” I asked.
Diane started sobbing harder.
“Ryan said the bank needed it because you had the strongest credit.”
I looked at my husband.
“You did all of this because my credit score was better?”
“It was temporary.”
That word again.
Temporary.
The same word he had used every time he asked me to cover his mother’s bills.
Then Rebecca arrived.
She brought another surprise.
While driving over, she had pulled the public filings on Carter Development Services.
Vanessa Carter was not just a restaurant consultant.
She owned a separate property-management company.
And three months earlier, Carter Development had purchased a condominium in downtown Columbus for $287,000.
The down payment had been made during the same week one of the $92,000 transfers left the home-equity account.
Diane stared at Ryan.
“You said that money paid contractors.”
Ryan’s voice cracked.
“It was an investment property.”
“In whose name?”
Rebecca already knew.
“Vanessa Carter’s.”
Diane stood so fast her chair tipped backward.
“You used my house to buy that woman a condo?”
Ryan yelled, “It wasn’t for her!”
Rebecca laid another printout on the table.
The condo mailing address listed Ryan as an authorized contact.
That was when my marriage stopped being the biggest shock in the room.
Diane looked physically ill.
For the first time, she wasn’t glaring at me.
She was staring at her son like she had never seen him before.
Ryan finally admitted that he and Vanessa had planned to operate short-term rentals together. He insisted they were business partners.
I didn’t care whether he had slept with her.
By then, the financial betrayal was enough.
Rebecca helped me freeze our joint credit line that night.
The next morning, I filed formal fraud disputes with both lenders and provided handwriting samples showing I had not signed the guarantees.
Rebecca also advised Diane to obtain her own attorney because notarizing a signature she had not witnessed could expose her to serious consequences.
For once, Diane listened.
Ryan didn’t.
He spent the next week sending me messages.
We can fix this.
Don’t destroy the family.
Think about Mom.
You’re overreacting.
Then the bank’s fraud department found something that made his excuses collapse completely.
The electronic loan application had been submitted from Ryan’s personal laptop.
Attached to it was a scanned copy of my driver’s license.
The image came from a folder in our home computer containing documents I had uploaded years earlier for a mortgage refinance.
He had taken my identification from our own files.
There was no misunderstanding left.
The forged guarantees were removed from my credit profile while the investigation continued. Rebecca separated my finances from Ryan’s and began divorce proceedings.
Mercer Hospitality Group eventually defaulted.
Because Diane had voluntarily transferred her property into the company, her position was complicated. She had to sell several assets and negotiate with creditors to keep from losing everything.
The restaurant closed.
Kyle walked away from the company after investigators determined Ryan had hidden several transfers from him as well.
Vanessa returned part of the money after attorneys challenged the condominium transaction, though the details were eventually handled through civil settlements I was not part of.
Ryan moved into a rented apartment.
Three months after that dinner, Diane asked to meet me.
I almost refused.
We met at a coffee shop.
She looked smaller than I remembered.
“I blamed you for years,” she said.
“For what?”
“For having money when we didn’t.”
I stared at her.
“You had a house, Diane. You had retirement savings. You had help.”
“I know.”
She looked down.
“Ryan kept telling me we were one investment away from fixing everything. Whenever something went wrong, he said you could cover us until the next deal worked.”
That explained the resentment.
In their minds, my income had stopped being mine.
It had become their emergency fund.
Their backup plan.
Their permission to keep making reckless decisions.
Diane swallowed.
“That dinner was cruel.”
“Yes.”
“I wanted you to feel like an outsider.”
“You succeeded.”
Her eyes filled with tears.
I didn’t comfort her.
Some apologies deserve to be heard without immediately being rewarded.
She apologized anyway.
I accepted the apology.
I did not restore the relationship.
Six months later, my divorce was finalized.
I kept my savings, my retirement accounts, and the home I had purchased before marrying Ryan.
The fraudulent debts remained separated from me.
Ryan was left dealing with the consequences of the businesses and loans he had created.
The strangest part was how often people later asked whether I regretted cancelling those payments after one humiliating dinner.
I always gave the same answer.
The empty plate wasn’t really about food.
It showed me exactly where I stood in that family.
They expected me to pay for the table.
Pay for the house.
Pay for the cars.
Pay for their mistakes.
And then sit quietly while they told me there was nothing left for me.
Walking away from dinner didn’t destroy that family.
It simply stopped me from financing the damage they were already doing to themselves.