I found out I was not even mentioned in my parents’ will on a Tuesday afternoon, after spending seven years paying their electric bill, property taxes, supplemental insurance, and almost every emergency expense they called me about. My younger sister, Melissa, was getting the house, the savings account, Dad’s truck, Mom’s jewelry, and everything else, while I was apparently getting the privilege of keeping the lights on until they died.
My name is Claire Bennett, I was forty-one, and I lived outside Philadelphia with my husband, Mark, while my parents still occupied the four-bedroom suburban house where Melissa and I grew up. Dad had retired early after a back injury, Mom had never returned to full-time work after raising us, and because I earned more than my sister, I gradually became the person they called whenever something “unexpected” happened.
At first, I was happy to help.
Then helping became automatic.
I paid the $430 electric bill one summer when their air conditioner ran nonstop, then the insurance premium, then a plumbing repair, then several property-tax installments when Dad said their savings had taken a hit. By the previous year, I was sending between $1,200 and $1,800 almost every month, while Melissa contributed birthday flowers, occasional groceries, and long explanations about why life was harder for her.
I discovered the will because Dad asked me to print a medical power-of-attorney form from a folder on his laptop, and an attorney’s PDF labeled “Executed Estate Plan” sat directly beside it. I should have closed the folder.
I didn’t.
The document left everything to Melissa.
There was one sentence explaining why: Our daughter Claire is financially secure and has no need of an inheritance.
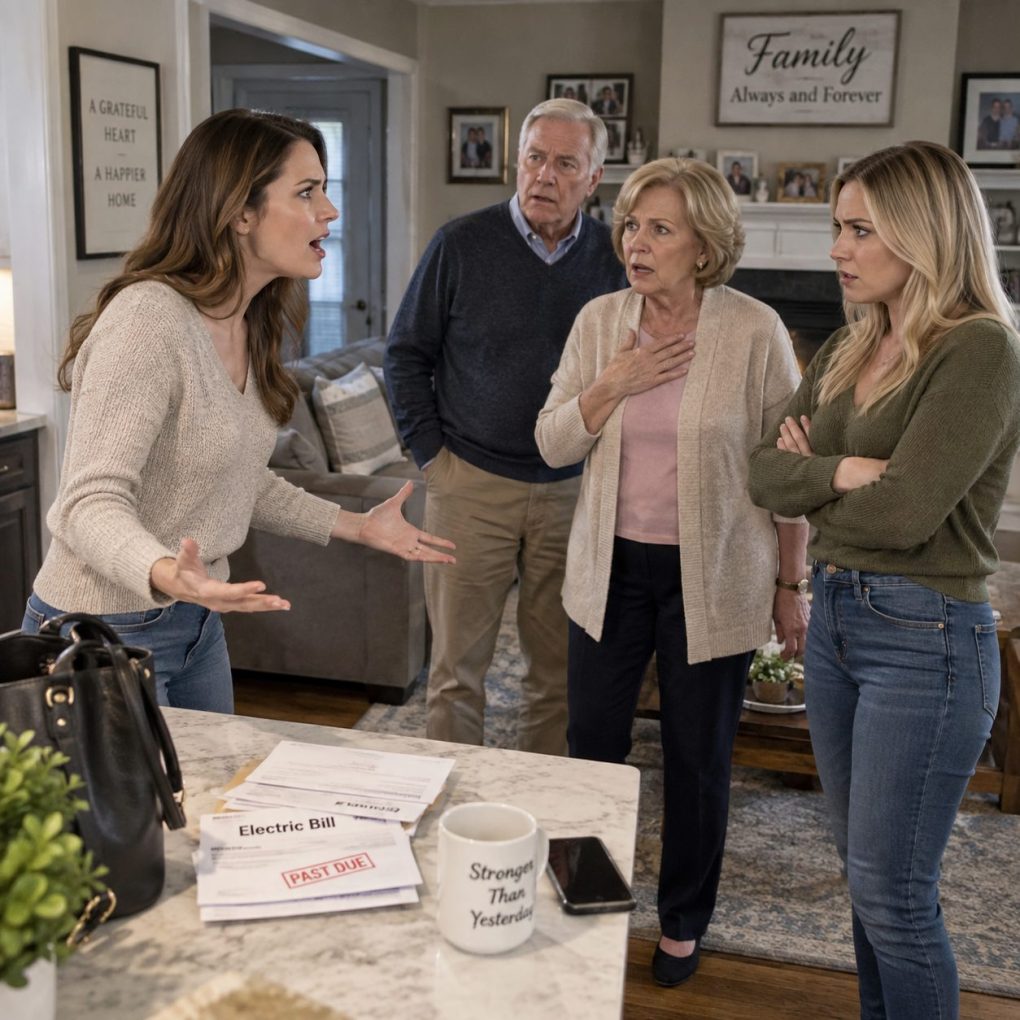
When I confronted my parents, Mom barely looked embarrassed.
“Melissa needs the house more than you do,” she said. “You have Mark, your career, retirement accounts. She has two children and an unstable ex-husband.”
I looked at Dad.
“So I’m responsible enough to fund your life, but too successful to be considered part of your estate?”
Dad sighed. “That’s not what this is.”
It was exactly what it was.
I did not scream, demand half the house, or threaten them.
I went home, canceled every automatic payment connected to their accounts, and transferred responsibility for their utilities back to them.
Thirty-two days later, Mom texted me.
POWER’S ABOUT TO GET SHUT OFF.
No hello.
No question.
Just an emergency she assumed still belonged to me.
I stared at the screen for nearly a minute.
Then I replied with two words.
Ask Melissa.
Mom called six times after I sent that message, Dad called twice, and by evening Melissa was leaving angry voicemails accusing me of “punishing elderly people over money I don’t even need.” I listened once, saved them, and called Melissa the next morning.
“How much are you paying toward Mom and Dad every month?” I asked.
Silence.
Then she said, “That’s not the point.”
It was the entire point.
Melissa had known about the will for almost a year, and she had also known I was covering bills while our parents preserved the house for her. She argued that the arrangement was fair because I had a stable career in healthcare administration, while she was raising two children on a teacher’s salary after a difficult divorce.
I understood why my parents wanted to protect her.
What I did not understand was why protecting Melissa required quietly using my income to protect the asset she would inherit.
The power was not disconnected because Dad paid the overdue balance from a small brokerage account he had been reluctant to touch. Then the property-tax bill arrived, followed by a roof repair estimate, and suddenly the larger problem became impossible to ignore.
My parents owned a house worth nearly $600,000 with no mortgage.
They were not poor.
They were cash-strapped because they refused to sell or borrow against the house, partly because they wanted Melissa to inherit it intact.
When Dad mentioned a reverse mortgage, Melissa objected immediately.
“You can’t do that. That house is supposed to stay in the family.”
I looked at her.
“You mean stay with you.”
Mom told me not to be cruel.
I asked one question.
“If the house is Melissa’s future security, why am I responsible for financing its present?”
No one answered.
Dad finally admitted that he had always assumed I would keep helping because “it didn’t hurt me financially.”
That sentence was worse than the will.
“You never asked whether it hurt me,” I said. “You only decided I could afford it.”
Mom started crying, and Melissa said I was turning love into an accounting exercise.
I stood up.
“No. You did that when you decided one daughter’s money was available and the other daughter’s inheritance was protected.”
Then Dad said quietly, “Maybe we should sell the house.”
Melissa immediately answered, “Absolutely not.”
Dad stared at her for a long time.
For the first time, I think he understood exactly what I had been trying to say.
My parents did not sell the house immediately, and I did not suddenly become the daughter who refused every phone call, because real families rarely resolve years of resentment in one dramatic afternoon. What changed first was simpler: I stopped being their financial plan.
Dad met with a fee-only financial planner and learned that between Social Security, his pension, and the equity in the house, they could support themselves comfortably if they downsized. Three months later, my parents listed the property, bought a smaller condo with lower taxes and maintenance costs, and kept enough from the sale to create an emergency fund that did not depend on either daughter.
Melissa was furious.
She accused me of forcing them to “liquidate the family home,” even though the decision was theirs and the house had become too expensive to maintain. During one ugly phone call, she said, “You got what you wanted. Now there’s less for everyone.”
I paused.
“Everyone?” I asked. “Or you?”
She hung up.
The will changed too, although not because I demanded it.
Dad and Mom met with their attorney and replaced the old plan with one that divided whatever remained equally between Melissa and me. When Mom told me, she seemed to expect relief.
Instead, I said, “I needed fairness while you were alive more than I needed money after you died.”
She cried.
This time, I sat beside her.
I told my parents I did not regret helping when they genuinely needed help, and I would still show up for medical appointments, emergencies, holidays, and ordinary family life. What I would no longer do was subsidize decisions designed to preserve someone else’s inheritance.
Dad apologized without explaining himself.
Mom took longer.
She admitted that because I had always been capable, she had treated my strength like an unlimited resource, while treating Melissa’s struggles like a permanent exemption from responsibility.
That sentence stayed with me.
Melissa and I barely spoke for months, but eventually even she adjusted to the new reality. Without a future house to organize her expectations around, she began focusing on her own finances, though our relationship never returned to what it had been.
A year after the original argument, Mom texted me a photo of her electric bill.
For half a second, my stomach tightened.
Then I read the message underneath.
Paid it myself. Look at me being an adult.
I laughed harder than I expected.
The strangest part was that I never wanted my parents’ house.
I wanted them to notice the contradiction in expecting one daughter to keep sacrificing because she was successful while rewarding the other because she struggled.
Money did not break our family.
The assumptions attached to it almost did.
I still help my parents sometimes.
Now they ask.
And now I am allowed to say no.