My wife, Brianna, stood in our bedroom doorway Saturday morning holding my wallet and said, “I’m taking your credit card for shopping with the girls—you owe me.” She had already pulled out the black card I used for business travel. I looked at it, then at her, and said, “Take it.”
She smiled like she had won something. For months, every argument about money ended the same way: Brianna insisted my higher salary meant I should finance whatever she wanted. When I questioned a purchase, she called me controlling and reminded me that her friends’ husbands “didn’t make them ask permission.”
What she ignored was that those cards were mine, not joint cards. I had given her permission to use one for household emergencies, but she had recently started taking others from my wallet without asking. The week before, I discovered $3,800 in designer purchases she had promised to return.
The moment her SUV left our driveway in Charlotte, North Carolina, I opened my banking app. Then I called the bank’s fraud department and reported every card she had taken without my permission as stolen. The representative canceled them immediately and ordered replacements.
Forty-six minutes later, my phone rang. I was standing in the kitchen making coffee when Brianna’s name appeared. I let it ring once, then answered.
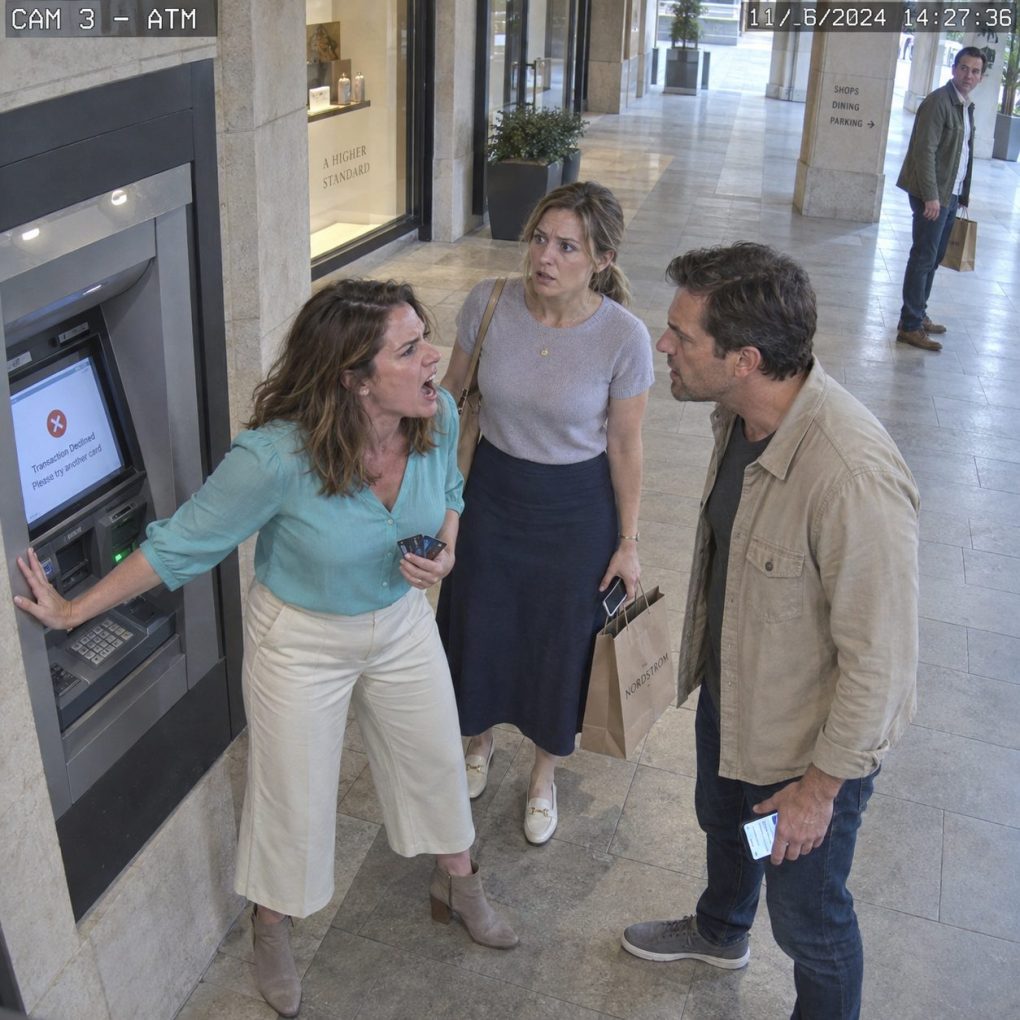
“What did you do?” she screamed. Behind her I could hear the faint electronic beep of a checkout terminal. She was at SouthPark Mall with three friends, standing at a luxury department-store register with almost $6,000 worth of clothes and cosmetics spread across the counter.
“I secured my cards,” I said. Brianna lowered her voice and hissed that everyone was staring. Apparently, she had tried the first card twice, then another, then a third while the cashier politely repeated, “Declined.”
One of her friends asked whether everything was okay. Brianna snapped at her to stop talking, then told me to reactivate the cards immediately. I said no.
“You embarrassed me on purpose,” she shouted. I stared at the empty space in my wallet and replied, “You took cards that weren’t yours after I told you months ago to stop. The embarrassment came after the decision.”
There was silence for two seconds. Then she said, “Fine. When I get home, you’re going to regret this.” I looked toward the folder on the kitchen counter containing six months of statements, unauthorized purchases, and screenshots. She had no idea the declined cards were the smallest problem waiting for her.
I had started collecting those records three weeks earlier. At first, I thought Brianna was simply overspending, something we could solve with a budget. Then I noticed purchases on accounts she had never been authorized to use.
There were hotel charges, designer bags, expensive dinners, and nearly $11,000 in online purchases spread across four months. Some had been returned for store credit instead of refunds, meaning the money never came back to the original accounts. The pattern was too deliberate to dismiss as carelessness.
I had also discovered she knew passwords I had never given her. A security alert showed one of my banking accounts had been accessed from her tablet while I was traveling in Dallas. I changed every password that night and scheduled an appointment with a financial adviser.
Brianna came home from the mall at 2:16 p.m. She slammed the front door so hard the framed photograph beside it shook. Her three friends were gone, but humiliation had followed her home.
“You made me look like a thief,” she said. I placed the statements on the kitchen island and answered, “Then explain these.” Her expression changed before she even touched the first page.
She tried anger first. Then she said married people didn’t need permission to spend each other’s money. I reminded her we maintained separate personal accounts by mutual agreement and that she had repeatedly used mine after I explicitly told her not to.
The next excuse was that I owed her because she had “sacrificed” for my career. Brianna had left a marketing job two years earlier, but not at my request. She had wanted to start an online fashion business, which I had helped fund with $24,000 from my savings.
That business had quietly stopped operating eight months earlier. What I had not known was that Brianna had continued telling her friends it was successful. Several of the mall purchases were apparently intended for photographs and social media posts meant to maintain that image.
Then I showed her something else: a bank notice about an attempted credit-limit increase made from her tablet. She went completely still. The request had failed because additional identity verification was required.
I told her I was freezing my credit and separating every account immediately. If we were going to stay married, there would be complete financial disclosure and counseling. Brianna looked at the paperwork, then at me, and whispered, “You’ve been planning this.” I answered, “No. I’ve been discovering it.”
Brianna slept in the guest room that night. By morning, her anger had turned into bargaining. She promised to return everything, restart her business, and never touch another card without permission.
But returning merchandise did not explain the hidden debt. When we pulled her credit report together, I learned she had opened three store cards and two personal lines of credit in her own name. Altogether, she owed almost $43,000.
That was the first moment she stopped defending herself. She sat on the sofa staring at the total while her breathing became shallow. Then she admitted she had been spending for almost two years to keep up with a group of friends who believed she was doing far better financially than she was.
I didn’t feel victorious. Watching someone you married realize they had built an entire social identity around debt was mostly sad. But sympathy did not mean restoring access to my accounts.
We met with a marriage counselor and, separately, a financial counselor. Brianna agreed to close unnecessary accounts, sell several expensive items, and create a repayment plan using money from a new job she found with a local advertising agency. Every step was documented because trust no longer worked on promises.
Her friendships changed too. Two women from the mall stopped calling when Brianna admitted she could no longer afford weekly shopping trips and expensive dinners. Another, Melissa, surprised both of us by telling her, “I thought you liked spending that much. I never knew you were drowning.”
That sentence stayed with Brianna. She had spent years blaming her friends for expectations they had never actually imposed. The pressure had mostly come from the life she wanted them to believe she had.
Our marriage did not magically recover. For almost a year, I kept separate finances and checked every shared expense. Brianna hated that at first, but eventually admitted that the restrictions made it impossible for her to hide from the numbers.
Eighteen months after the mall incident, she had paid off more than half her consumer debt. We were still in counseling, still arguing sometimes, but the arguments had changed. She no longer called access to my money proof of love, and I no longer ignored uncomfortable questions just to keep the peace.
She once asked whether I regretted letting her take the card that morning. I told her no. Watching three cards decline in front of her friends was humiliating, but it exposed a problem neither of us could keep pretending was small. The real turning point wasn’t the cashier saying “declined.” It was the day I finally stopped confusing financial boundaries with cruelty.