The emergency room doctor looked me in the eye and said, “If you keep living like this, your body is going to shut down.”
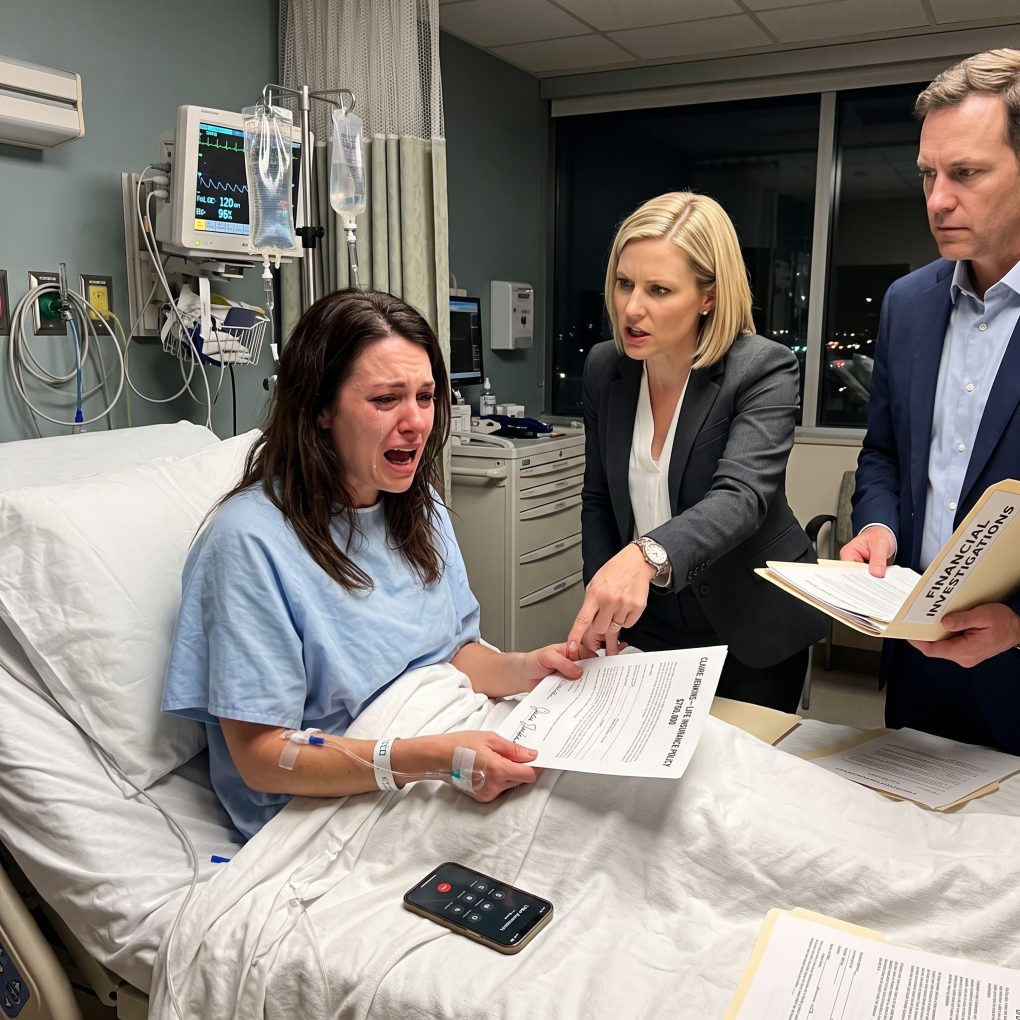
I was thirty-four, hooked to an IV in a hospital outside Columbus, Ohio, after collapsing at work. My heart was racing, my hands shook, and I hadn’t slept properly in months. The diagnosis was severe exhaustion and dehydration.
I texted our family group chat: I’m in the hospital. Please call me.
Six hours passed. No one came. No one called.
Then my brother, Ryan, finally texted.
Hey, can you still cover my car payment Friday?
I stared at the message. Ryan was twenty-nine and employed. But for years, I had covered his car, Dad’s property taxes, Mom’s prescriptions, and every “temporary emergency” that became my responsibility.
I replied, No. I’m hospitalized.
Three dots appeared.
So is that a no for the whole payment or just today?
Something inside me went still.
I opened my banking app and canceled every automatic transfer to my family. Then I emailed my attorney, Rachel Kim, and asked her to revoke the financial authorization I had signed for Dad two years earlier. He had said he needed it to speak with the bank while I was traveling.
Rachel called immediately.
“Claire, this doesn’t only let your father discuss accounts,” she said. “It gives him limited power to move funds.”
My stomach tightened. “From checking?”
“Possibly more. Don’t call him yet. I’m contacting the bank.”
At 11:18 p.m., an investigator called my hospital room.
“Ms. Bennett, your father attempted a transfer forty minutes ago. We blocked it because your attorney placed an alert.”
“How much?”
“Eighty-six thousand dollars.”
“I don’t have that much in checking.”
“No. It came from an investment account opened in your name.”
I had never opened one.
Then he asked a question that made the monitor beside me beep faster:
“Do you know anything about a company called Bennett Family Holdings?”
I thought canceling a few payments would finally force my family to respect my boundaries. Instead, it exposed an account I had never opened, a company I had never heard of, and a secret my father was desperate to protect. But the next document brought to my hospital room was far more terrifying.
“No,” I whispered. “I’ve never heard that name.”
The investigator, Mr. Lawson, told me the account had been opened fourteen months earlier using my Social Security number, a scanned driver’s license, and the financial authorization bearing my signature. More than $112,000 had moved through it. The blocked $86,000 transfer was headed to a business account controlled by my father.
Rachel told me not to answer any family calls. By morning, the hospital moved me to a quieter room because my blood pressure kept spiking. That was when Dad finally called—not to ask if I was alive. “What did you do to the bank?” he snapped. “They froze everything.” I recorded the call on speaker after confirming Ohio law with Rachel. “I canceled access to my money,” I said. “Our money,” Dad corrected. “That company supports the whole family.” I felt cold. “What company?”
Silence. Then Mom grabbed the phone. Her voice turned sugary. “Claire, honey, you’re exhausted. Let your father handle this. Just tell the bank it was a misunderstanding.” Behind her, Ryan shouted, “My payment is due today!” I ended the call.
Mr. Lawson arrived with two fraud investigators and a folder of transactions. My salary deposits had not gone directly into the hidden account, but Dad had used the authorization to borrow against an investment portfolio created with money transferred from my savings over time. The records showed payments for Ryan’s SUV, my parents’ mortgage, vacations, and something labeled “consulting fees.”
Then we found twelve monthly deposits of $4,000 from Bennett Family Holdings into an account ending in 7712. “That isn’t mine,” I said. Rachel leaned closer. “Whose is it?” I recognized the number. It belonged to my mother. She had once sent me a screenshot while asking for grocery money.
Before I could process that, a hospital administrator entered with a security officer. A man claiming to be my father had called twice, asking staff to declare me mentally incapable of managing my finances. He had also tried to obtain my room number.
My phone rang again. Dad. Rachel nodded for me to answer. His voice was no longer angry. It was terrified. “Claire, listen to me. The bank thinks you’re accusing us of fraud. If you don’t fix this today, we could lose the house.”
“You used my identity.”
“We were protecting what you built,” he insisted. “And you signed the papers.”
“I signed permission for you to speak to the bank.” Dad went silent.
Then Mr. Lawson slid one final document across my blanket. It was a life insurance policy for $750,000, opened six months earlier. The insured person was me. The beneficiary was Bennett Family Holdings. And at the bottom, beside a signature that looked almost exactly like mine, was the name of the insurance agent who had verified my identity: Ryan Bennett—my brother.
Rachel photographed the policy and told Mr. Lawson to preserve every record connected to it. The hospital hid my room information from callers. For the first time in years, protecting myself felt more important than protecting my family from consequences. Ryan called eleven times before leaving a message. “Claire, Dad made me do it. Call me before the police get involved.” The police were already involved.
Detective Elena Morales from the financial crimes unit arrived that afternoon. The bank had reported suspected identity theft, forged documents, and the attempted transfer. The insurance company had frozen the policy. I gave her my messages, records, original authorization, and Dad’s recorded call. Morales focused on one sentence: “And you signed the papers.” She looked at me carefully. “He knows there were other papers. Now we determine who prepared them.”
The next morning, I was discharged with orders to rest. I stayed in Rachel’s guest room because my parents had a key to my apartment. We froze my credit, changed my passwords, replaced my identification, and removed Dad as my emergency contact. Three days after my hospitalization, Dad called from an unfamiliar number. The bank had frozen Bennett Family Holdings, their mortgage payment had bounced, and Ryan’s car payment had failed. Dad demanded that I tell investigators the company was a family arrangement.
“What arrangement?” He claimed he created it to manage the money I sent them. But incorporation records showed Dad owned forty percent, Mom owned forty percent, and Ryan owned twenty percent. My name appeared nowhere—except on the debt. Then Dad made his mistake. “If you cooperate, we’ll cancel the second policy too.” Rachel, listening beside me, wrote SECOND POLICY on a legal pad. Dad stopped talking.
Detective Morales obtained an emergency preservation order. The second policy was worth $250,000 and had been opened nine days earlier, with Mom as beneficiary. It was pending because the insurer requested a medical interview. The contact number belonged to a prepaid phone later found in Ryan’s apartment. Ryan was an administrative assistant at an insurance brokerage. He was not a licensed agent, but he had access to application templates. The agent name on my first policy belonged to his supervisor, who was on maternity leave when it was submitted. Ryan had used her login and copied her electronic signature.
The next break came from Mom. She asked to meet privately at Rachel’s office and arrived with envelopes stuffed with bank statements, company records, and emails. For one hopeful second, I thought she had come to apologize. Instead, she said, “Your father controlled everything.” The records proved Dad planned the hidden account. They also proved Mom had received $48,000 in “consulting fees” and suggested the second policy after learning the first might lapse.
“You weren’t trapped,” I said. “You were paid.” Her face crumpled. “He said you had plenty. You don’t have children. We thought eventually it would come back to family.” I stared at her. “I am family.” Mom looked down. That silence hurt more than any insult. They had never seen me as a daughter who needed care. I was an income stream with a familiar face.
Mom turned over the documents because Dad threatened to blame her. She wanted immunity. Detective Morales promised nothing, but the evidence secured search warrants. Police recovered copies of my identification, insurance forms, and a notebook tracking every payment I had made since 2021. Beside several entries, Dad had written “increase pressure” and “mention Mom’s medication.” They had studied which emergencies made me pay fastest.
Investigators also learned why Dad attempted the $86,000 transfer while I was hospitalized. Ryan told him I might stop working for weeks. Without my deposits, their accounts would collapse, so Dad tried to move the remaining funds before I reviewed them. The truth about my exhaustion was brutal but simple. Nobody had caused my collapse directly. I had worked extra shifts and bookkeeping jobs because my family constantly manufactured crises. They knew I was exhausted. They believed I would keep paying anyway.
Within two weeks, Dad and Ryan were arrested. Dad was charged with identity theft, forgery, theft, and attempted unlawful transfer. Ryan faced charges related to the forged policies and unauthorized system access. Mom was later charged for her role in the company and second application. Their attorneys fought nearly everything, but the documents were overwhelming. The bank blocked the transfer and closed the fraudulent account. Much of the $112,000 was already gone, so I did not recover every dollar. Restitution came from selling Ryan’s SUV and placing a lien on my parents’ house. Both insurers canceled the policies and confirmed I owed nothing. Ryan’s employer fired him and cooperated with police.
Some relatives called me cruel for “putting my parents through this.” I sent each of them the notebook page saying “mention Mom’s medication,” then blocked them. My cousin Natalie was the only relative who asked if I was safe. She brought groceries and sat beside me during my first therapy appointment. Six months later, Dad accepted a plea agreement involving prison time, probation, and restitution. Ryan pleaded guilty to multiple charges and lost any chance of returning to insurance. Mom received a shorter sentence after testifying, but the judge rejected her claim that she was merely obedient. The $48,000 told a different story.
I moved into a townhouse across town. Nobody in my family had the address. I reduced my workload and learned that resting was not laziness. At first, silence frightened me. Eventually, it felt like peace. On the anniversary of my collapse, I found Ryan’s original text in an archived screenshot: Can you still cover my car payment? I remembered lying beneath hospital lights, waiting for someone to care whether I was breathing. That message had felt like proof that I had no family.
Now I understood it differently. It was the moment they finally told me what I meant to them—and the moment I believed them. I did not destroy my family by stopping the payments. I stopped financing people willing to steal my identity, insure my life, and call it love. I deleted the screenshot, turned off my phone, and joined Natalie and two close friends for dinner. When I entered the restaurant, they hugged me and asked the question my parents never had: “Are you okay?” This time, I answered honestly. “Yes,” I said. “I finally am.”