Mom decided she controlled my salary: 60% for my sister, 25% for expenses, and only 15% for me. I agreed without arguing. Four days later, she walked into my kitchen, saw one document on the counter, and screamed so loudly my neighbors came outside.
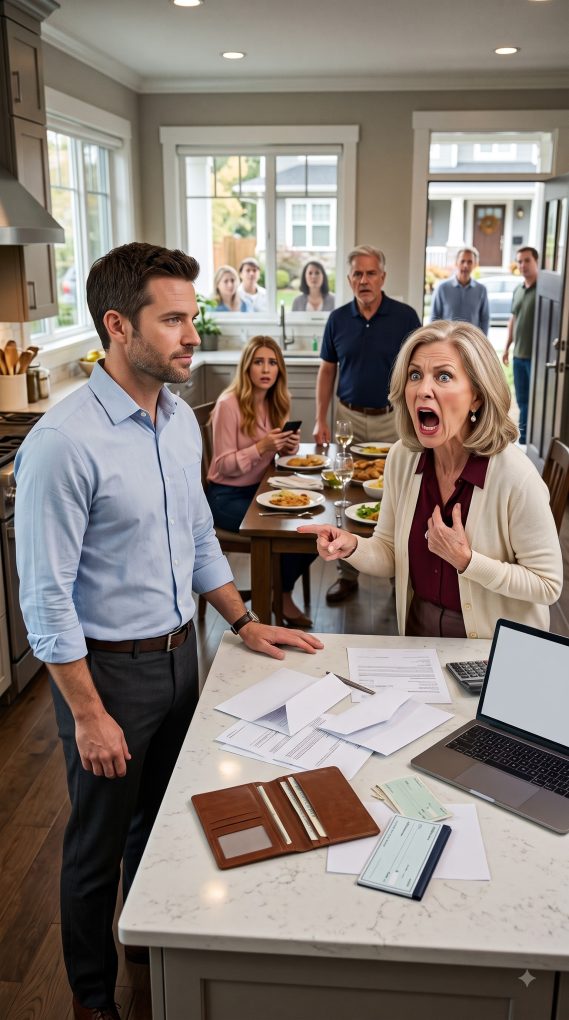
My mother’s scream was so loud that my next-door neighbor came running across the lawn before I even reached the kitchen.
“You sold my house?”
Mom stood beside my kitchen island, shaking, staring at the real-estate folder I had deliberately left open.
My sister Madison rushed in behind her. “What house?”
Mom spun toward me.
“Claire, tell me this is some sick joke.”
It wasn’t.
Four days earlier, Mom had gathered us around the dining table and announced her newest family rule.
“Your salary goes through me now. I’ll distribute it fairly.”
I was thirty-five years old.
I asked her what “fairly” meant.
She had already written the percentages down.
Sixty percent to Madison.
Twenty-five percent for expenses.
Fifteen percent to me.
Madison actually smiled.
Dad stared at the table.
I earned $184,000 a year as a corporate compliance director. Madison had closed her boutique six months earlier and somehow decided my paycheck was now the family recovery fund.
“You’re serious?” I asked.
Mom folded her arms.
“Family takes care of family.”
“And the twenty-five percent covers all expenses?”
“Obviously.”
I looked directly at her.
“All of them?”
She rolled her eyes. “Yes, Claire.”
So I smiled.
“Fine. Put it in writing.”
That made Dad look up.
Mom didn’t notice.
By Friday, my first redirected paycheck hit the account she controlled.
By Saturday, Madison had already received her sixty percent.
Then came Sunday lunch.
Mom walked into my kitchen expecting roast chicken.
Instead, she found a property valuation, a signed listing agreement, and a photograph of the four-bedroom house she had lived in for eleven years.
Across the top was one sentence.
OWNER AUTHORIZATION TO SELL.
Mom slammed both hands on the counter.
“You can’t sell my house!”
I quietly answered.
“It was never your house.”
Mom thought the worst thing in that kitchen was the listing agreement. Then my phone rang, and my attorney told me someone had tried to borrow money against that same property using my signature. The rest of what happened is in the comments.
Mom stared at me as if I had suddenly started speaking another language.
“What do you mean it was never my house?”
Dad entered the kitchen slowly.
His face had already changed.
He knew.
Seven years earlier, my parents had nearly lost the property after Dad’s business collapsed. There were unpaid taxes, a second mortgage, and more than $90,000 in debt attached to the house.
I paid everything.
The attorney handling the settlement recommended transferring ownership to me because the lender would not refinance my parents.
Mom signed the papers.
Apparently, she had convinced herself those papers stopped mattering once the crisis passed.
“You said we could live there,” she snapped.
“I did. Rent-free.”
Madison stepped forward. “So you’re throwing Mom and Dad into the street because she asked you to share?”
“No.”
I pulled out the spreadsheet I had prepared.
“I’m following Mom’s percentages.”
Their property taxes, insurance, utilities, repairs, Mom’s SUV payment, and the monthly amount I had been quietly covering on Madison’s health insurance totaled more than $6,100 a month.
Twenty-five percent of my take-home pay didn’t come close.
Mom grabbed the paper.
“You make enough.”
“That isn’t the system you created.”
Madison’s face reddened.
“Then use your fifteen percent.”
I almost laughed.
“My fifteen percent belongs to me. Remember?”
Dad sat down.
For the first time, Mom looked uncertain.
Then my phone rang.
Rebecca Sloan, my attorney.
I put her on speaker.
“Claire, the title company called me back. We have a bigger problem.”
Everyone went silent.
Rebecca explained that a lender had requested verification of ownership three days earlier.
Someone was applying for a $310,000 home-equity loan against my parents’ house.
My name appeared on the application.
So did a signature claiming to be mine.
I had signed nothing.
Dad whispered, “Linda?”
Mom’s face drained.
Madison reached for her purse.
“Where are you going?” I asked.
“Home.”
“Sit down.”
She froze.
Rebecca continued.
The loan file contained another document.
A so-called Family Income Support Agreement stating that I had permanently committed sixty percent of my salary to Madison.
Exactly the percentage Mom had demanded.
The agreement had supposedly been signed six weeks earlier.
Six weeks before Mom ever announced her brilliant new arrangement.
My stomach turned cold.
This had never been about fairness.
They needed deposits from my paycheck to make the forged agreement look real.
“Madison,” Dad said slowly. “What were you buying?”
She said nothing.
Rebecca answered for her.
“The lender paperwork references a $465,000 condo.”
Dad stood so quickly his chair fell backward.
Mom finally spoke.
“It wasn’t supposed to hurt anyone.”
I stared at her.
Then Rebecca sent me one final page from the loan package.
The proposed cash-out instructions showed that not all $310,000 was going toward Madison’s condo.
Almost $84,000 was scheduled to be wired somewhere else.
To an account ending in four digits I recognized immediately.
Mom’s personal account.
And beneath the transfer instructions was another forged version of my signature.
Mom looked at the screen.
Then at me.
“You were never supposed to see that.”
What do you think will happen next? I’d love to hear your honest guess or reaction “I’d love to hear your opinions – your comments really make me happy and inspire me to keep writing.”
Dad looked at Mom like he had never seen her before.
“Eighty-four thousand dollars?”
Mom immediately turned defensive.
“Robert, don’t start.”
“Start what? Asking why my wife was secretly taking eighty-four thousand dollars from a loan against a house she doesn’t even own?”
“It wasn’t stealing.”
Rebecca was still on speaker.
She interrupted calmly.
“Mrs. Bennett, I strongly recommend that you stop explaining this while I’m on the phone.”
Mom’s mouth snapped shut.
Madison suddenly lunged for my phone.
I stepped backward.
“Don’t.”
“I just want to talk to her.”
“You can call your own attorney.”
That sentence changed the room.
Until then, Madison still seemed to believe this was another family argument that would end with me giving in.
It always had before.
When her boutique missed rent, I covered it.
When Mom’s transmission died, I paid for the replacement.
When Dad needed dental surgery, I handled the bill before anyone asked.
I had spent years confusing generosity with obligation.
Mom had apparently made the same mistake.
She just believed the obligation was permanent.
Dad picked up the fallen chair.
“Tell me everything,” he said.
Mom shook her head.
“Not here.”
“Here.”
Madison started crying.
That was when the entire plan finally came out.
After her boutique failed, she had fallen behind on nearly $38,000 in credit-card debt.
She was also being forced out of her apartment when the owner decided to sell.
Mom decided Madison needed “stability.”
Stability apparently meant buying her a luxury condo.
Madison couldn’t qualify for the mortgage.
Her income was inconsistent, her credit score had collapsed, and the lender wanted proof that the large monthly deposits appearing in her account would continue.
So Mom invented a solution.
Me.
The forged Family Income Support Agreement claimed I had voluntarily promised Madison sixty percent of my net employment income for five years.
But paperwork alone wasn’t enough.
The lender wanted to see actual transfers.
That explained Mom’s sudden family meeting.
She needed me to begin sending exactly sixty percent voluntarily so the bank records would match the fake agreement.
I almost admired the nerve of it.
Almost.
“And the home-equity loan?” Dad asked.
Mom looked away.
Madison answered.
“The down payment wasn’t enough.”
Dad stared at her.
“So you used Claire’s house.”
“Mom said Claire wouldn’t care once everything settled down.”
I laughed once.
Not because anything was funny.
Because there are moments when anger becomes so enormous that your body doesn’t know what else to do.
Then I pointed toward Mom.
“And your eighty-four thousand?”
Mom finally admitted she had accumulated debts of her own.
Credit cards.
A personal loan.
Money she had borrowed to help Madison keep the boutique alive.
She said she planned to repay everything once Madison “got back on her feet.”
“Using my money,” I said.
Mom’s eyes filled.
“We’re your family.”
There it was again.
The sentence that had cost me more money than I wanted to calculate.
Dad rubbed both hands over his face.
“Did you forge my name too?”
Mom hesitated.
That was his answer.
He walked out of the kitchen.
She followed him.
“Robert.”
He turned around in the hallway.
“No.”
I had never heard Dad speak to her like that.
“You told me Claire volunteered to help Madison. You told me the papers I signed were only proof that we lived at the property.”
Mom said she had been trying to keep the family together.
Dad answered, “By stealing from one daughter to finance the other?”
Madison shouted that everyone was attacking her.
I corrected her.
“No. Everyone is finally making you responsible for yourself.”
She grabbed her purse.
Before leaving, she looked at me and said, “You really care more about money than your own sister?”
That accusation used to work.
This time it didn’t.
“If I cared more about money, Madison, I would’ve stopped paying your bills years ago.”
She left without answering.
Rebecca advised me to contact the lender’s fraud department immediately.
I did.
Because the loan had not funded yet, the lender froze the application while the signatures were reviewed.
Rebecca also filed a written fraud notice with the title company so no lien, refinance, or transfer involving my property could proceed without direct verification from me.
Then I canceled the salary arrangement.
Mom exploded.
“You agreed!”
“I agreed to your budget. I did not agree to fraud.”
“You can’t just change your mind because you’re angry.”
“My employer absolutely can change my direct deposit because it’s my paycheck.”
The first transfer was gone.
Madison had already received most of it.
I decided not to fight over that single paycheck.
I considered it the most expensive lesson I had ever purchased.
The house was different.
Mom assumed the listing agreement had been prepared merely to frighten her.
It hadn’t.
For years, keeping that property had cost me thousands of dollars annually.
I had tolerated it because Dad had worked his entire life and because I wanted my parents to feel secure.
But after someone tried to borrow $310,000 against it using my forged signature, the arrangement was over.
I gave my parents ninety days.
Dad understood immediately.
Mom did not.
She called relatives.
She told them I was evicting my elderly parents after becoming obsessed with money.
Aunt Carol called me furious.
Then I emailed her the monthly expenses I had been paying.
She never called back.
Uncle Raymond did.
He apologized.
Apparently, Mom had been telling the family for years that Dad paid me rent.
He never had.
Two weeks later, Madison called.
Not to apologize.
She wanted to know whether I would co-sign a smaller condo.
I hung up.
That was the moment I finally understood something important.
People who benefit from your lack of boundaries often experience your first boundary as cruelty.
The lender eventually confirmed that the signatures on both documents were disputed and closed the application.
Rebecca helped me submit affidavits documenting that I had not authorized the loan or the income agreement.
Mom and Madison hired their own attorney.
I won’t pretend the months afterward were peaceful.
They weren’t.
There were interviews, document requests, angry messages, and a lot of uncomfortable conversations.
But no money was ever taken from the property.
No lien was recorded.
Madison never got the condo.
Three months later, the house sold.
Dad moved into a two-bedroom apartment ten minutes from my place.
Mom went with him because, despite everything, Dad wasn’t ready to end forty years of marriage.
But he made one change.
Their finances were separated.
Completely.
He opened his own checking account for the first time in decades.
Madison moved into a small rental and took an office-manager job.
I stopped paying her insurance, credit cards, phone bill, and emergencies that somehow appeared every month.
For almost six months, Mom barely spoke to me.
Then one Sunday she called.
For half a second, I thought she might apologize.
Instead she said, “Your father says we need to pay our own car insurance now.”
“Yes.”
A long silence followed.
Then she quietly asked, “Was it really this expensive every month?”
I looked at the old spreadsheet still saved on my laptop.
“Yes.”
Another silence.
“I didn’t know.”
“You never asked.”
That was the closest thing to an apology I received.
Maybe someday there will be a better one.
Maybe not.
But I no longer need it.
The strange part is that I actually followed Mom’s rule.
She wanted sixty percent devoted to Madison.
Twenty-five percent to expenses.
Fifteen percent for me.
For one paycheck, that was exactly what happened.
Then I stopped paying for everyone else’s lives.
And the moment they had to survive on the system they designed for me, they suddenly discovered how unfair it was.