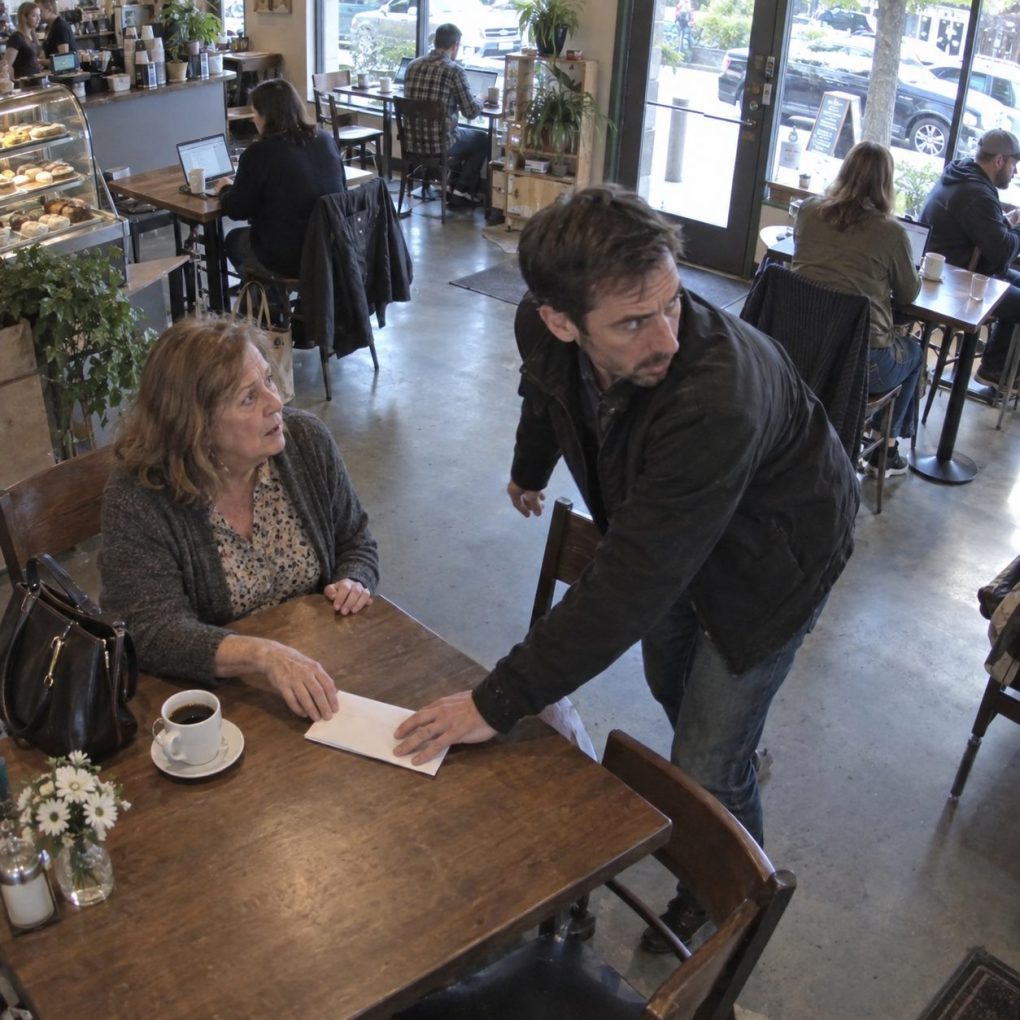
“Keep this hidden, and read it tonight,” the stranger whispered as he slid a thick white envelope across my table at a crowded café in Portland, Oregon. Before I could ask his name, he glanced toward the entrance, pulled his baseball cap lower, and walked out, leaving me with cold coffee, shaking hands, and the uncomfortable feeling that someone had just mistaken me for somebody else.
My son, Ryan, and his wife, Melissa, were in Seattle for the weekend, supposedly meeting friends. They had insisted I spend Saturday downtown rather than alone in the house, and Ryan had even chosen the café for me, saying I needed “a little normal life” after my husband, Thomas, died eight months earlier.
I nearly threw the envelope away.
Instead, I slipped it into my purse.
That night, sitting at my kitchen table, I finally opened it.
Inside were photocopies of bank statements, emails, and a document bearing my name.
At first, nothing made sense. Then I saw a transfer for $48,000 from my retirement account into an investment company called Westbridge Capital, followed by another for $72,000 three weeks later.
I had never heard of Westbridge Capital.
My stomach tightened when I found the authorization page.
The signature at the bottom looked exactly like mine.
It was not.
I turned to the emails.
One message was from Melissa to a man named Caleb Morris: “She still trusts Ryan completely. Once the house paperwork is done, we can move the rest without triggering questions.”
Another message from Ryan said, “Mom thinks I’m just helping simplify things after Dad. Keep everything under the threshold we discussed.”
I read that sentence five times.
For months, Ryan had been handling bills because grief made paperwork feel impossible. He changed my online banking password “for security,” organized insurance documents, and persuaded me to give him limited financial power of attorney in case I became ill.
I had thanked him for it.
Near the bottom of the envelope was a photograph of the stranger from the café standing beside Ryan outside an office building.
On the back, someone had written:
My name is Daniel Morris. Caleb is my brother. Your son and his wife are using him to move your money. I tried to stop them. They know I have copies.
My phone rang.
Ryan’s name appeared on the screen.
I stared at it until the call stopped.
Then a text arrived.
Mom, we’re coming home early. Don’t sign or open anything until we get there.
That was when I realized the envelope had never been delivered to me by accident.
And somehow, Ryan already knew I had it.
I locked every door before calling Daniel from the number written inside the envelope. He answered on the first ring and told me not to mention his name to Ryan, because Caleb had already warned him that my son was “cleaning up loose ends.”
Daniel explained that his brother worked as a financial consultant but had recently begun moving client money through private investment accounts that offered almost no transparency. Months earlier, Caleb bragged that Ryan had found “the perfect family account” because the owner was grieving, trusted him completely, and rarely checked statements.
That owner was me.
Daniel had secretly copied the records after realizing the transfers were not legitimate investments but temporary holding accounts used to move money elsewhere. He said he contacted me only after learning Ryan planned to refinance my house and use part of the proceeds to cover what had already disappeared.
I felt sick.
The refinancing paperwork was sitting in my study.
Ryan had told me signing it would reduce my monthly costs.
I drove to my bank the moment it opened Sunday morning and asked for a manager. By noon, my online access had been reset, outgoing transfers were restricted, and the bank’s fraud department had copies of Daniel’s documents.
Then came the part I was almost afraid to ask.
“How much is gone?”
The manager hesitated.
Approximately $136,000 had already left accounts in my name.
More requests were pending.
I called an attorney named Susan Adler, who had handled a friend’s estate dispute, and she advised me not to confront Ryan yet. She also reviewed the power-of-attorney document and found that the version on file granted Ryan broader authority than the one I remembered signing.
That evening, Ryan and Melissa arrived.
I watched them through the window before opening the door.
Melissa was carrying a leather folder.
Ryan hugged me too tightly.
“We came back because we were worried about you,” he said.
For the first time in forty-two years of being his mother, I wondered whether every expression on his face could be trusted.
I smiled and said I was tired.
They stayed for dinner.
Ryan talked about refinancing the house.
Melissa asked twice whether I had received any “strange mail.”
I lied and said no.
After they left, I sat alone beneath the kitchen light holding the photograph Daniel had given me. There are moments when betrayal hurts not because you suddenly stop loving someone, but because you realize love has been used as the lock on the door they were quietly opening behind your back; I had spent my entire life believing trust inside a family was something sacred, and now I understood that trust without questions could become permission for the wrong person to decide what you deserved to know.
Then Susan called.
Her voice was urgent.
“Margaret, don’t go to sleep yet.”
She had just checked the county property records.
Someone had filed paperwork that afternoon attempting to place my house into a newly created family trust.
The trustee was Ryan.
Part 3 — What My Son Thought I Would Never Question
Word Count: 589
The attempted transfer had not been completed, but Susan told me it was enough to stop pretending this was simply a misunderstanding. She contacted the title company first thing Monday morning, disputed the filing, and advised me to revoke Ryan’s power of attorney immediately.
I signed the revocation in her office.
That signature felt different from every one I had made during the previous year.
This time, I knew exactly what it meant.
The bank’s investigation moved quickly after Daniel provided original emails and internal account records. Several transfers had been initiated using credentials connected to Ryan’s devices, while the falsified authorization documents appeared to have been assembled from legitimate paperwork I had signed after Thomas died.
Caleb had created Westbridge Capital.
It was not a normal investment firm.
Money moved through it into accounts connected to Caleb, Ryan, and a property company Melissa had registered under her maiden name.
Susan warned me that discovering the transfers did not automatically determine criminal responsibility, so we let the records speak for themselves. I provided investigators every document I possessed and answered only what I knew.
Ryan called constantly.
At first, he sounded concerned.
Then angry.
Finally frightened.
“Mom, you’re making this look criminal when it isn’t,” he said during our last direct conversation.
I asked one question.
“Did you take my money without telling me?”
He hesitated.
That hesitation was my answer.
Weeks later, investigators determined that Ryan and Caleb had used the power of attorney to move money beyond the authority I had intended to grant, while Melissa helped create paperwork designed to make some transfers appear connected to legitimate property planning.
Caleb was charged first.
Ryan and Melissa were charged later in connection with the financial scheme, though their cases developed separately. Faced with bank records, emails, device logs, and Daniel’s cooperation, Ryan eventually entered a plea agreement requiring restitution and carrying penalties related to the unauthorized transfers.
Melissa’s case also ended in a negotiated resolution.
I recovered most of the money through frozen accounts, insurance coverage, and restitution, although legal fees consumed part of what remained.
The house stayed mine.
That mattered less than I expected.
What mattered was learning how close I had come to losing the right to make decisions about my own life while believing my son was protecting me.
Ryan wrote me a letter before sentencing.
He said he had never planned to steal from me forever. He claimed Caleb convinced him the money would be replaced after a real-estate deal succeeded, and once the first transfer disappeared, every new lie became necessary to protect the one before it.
At the end, he wrote, “I know you probably hate me.”
I did not.
That was the hardest part.
I still remembered the little boy who used to climb into my bed during thunderstorms and the teenager who cried when his father taught him to drive. Loving those memories did not require me to pretend the man he became had not betrayed me.
Daniel came to see me once after everything ended.
He apologized for frightening me in the café.
I told him the envelope frightened me far less than living another year without knowing the truth would have.
Months later, I changed the locks, hired my own financial adviser, and learned every password to every account myself.
I stopped apologizing when I asked questions.
People sometimes mistake independence for loneliness, especially when you are an older woman whose family used to handle everything for you. I learned the opposite: there was extraordinary peace in knowing that nobody could move my money, sign my name, or decide my future simply because I trusted them.
The envelope Daniel slid across that café table did not destroy my family.
The deception had already done that.
The envelope simply gave me the chance to save what was still mine.