My boss’s daughter stole the multi-million-dollar pitch I had spent months building, presented it to six wealthy investors as if it were hers, and then told them they no longer needed me. I didn’t argue or expose her in the room; I simply walked away and let them discover what the idea was worth without the person who actually knew how to make it work.

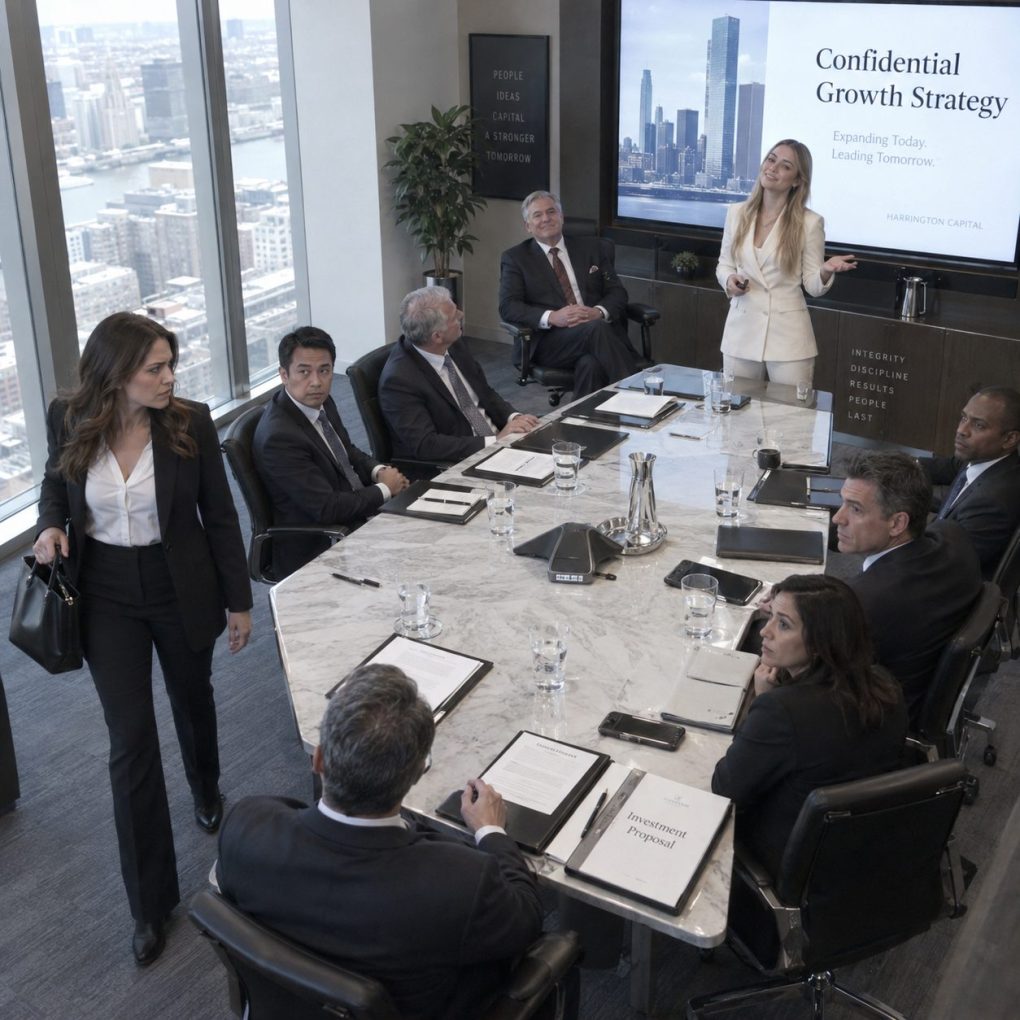
When Victoria Langford stepped in front of six investors at the Four Seasons in Manhattan and began presenting the expansion strategy I had spent eleven months building, I knew within thirty seconds that she had stolen everything. The financial model, the acquisition sequence, the supplier restructuring plan, even the phrase I used to describe our customer-retention problem appeared on her slides, while my name had been removed so completely that anyone in the room would have assumed the CEO’s twenty-seven-year-old daughter had created the entire proposal herself.

Her father, Charles Langford, sat at the end of the table smiling as though he had been waiting for exactly this moment. I was supposed to deliver the presentation because I had spent seven years running strategic development for Langford Home Group, but two minutes before the meeting Charles quietly told me, “Victoria needs visibility, Claire, so let her take this one.”

I thought she would introduce me and present alongside me.

Instead, she presented my work as hers.

One of the investors, Martin Reeves, asked how the company planned to reduce distribution costs without destroying service levels, and Victoria gave him an answer so vague that I immediately understood she had memorized my slides without understanding the operational model behind them. When Martin turned toward me and asked whether I wanted to add anything, Victoria smiled before I could speak and said, “Honestly, Claire’s team has already given us everything useful, so you really don’t need her ideas beyond what you’ve seen here.”

The room became painfully quiet.

Charles laughed.

“Victoria has a point. Strategy only matters when leadership knows how to execute it.”

I looked at both of them, then at the six people considering an investment worth nearly forty million dollars, and suddenly realized that defending myself would only help the people who had just publicly erased me. My model depended on supplier agreements I had personally negotiated, executives I had recruited, and a phased restructuring plan that could not be understood by reading twenty-three slides.

So I closed my laptop.

Charles frowned. “Where are you going?”

“You said you have everything useful.”

Victoria crossed her arms and smiled.

“We do.”

I nodded once, picked up my bag, and walked out of the room without arguing.

At 6:14 that evening, I sent Charles my resignation.

At 6:27, he replied that I was being emotional and reminded me that senior employees were replaceable.

I did not answer.

Three days later, Martin Reeves called my personal number and asked one question.

“Claire, did Victoria actually build that plan?”

I paused before answering.

“No.”

Then he asked something far more dangerous for Langford Home Group.

“Can they execute it without you?”

This time, I did not need to pause.

“No.”
I did not take company files when I left, contact Langford clients, or attempt to sabotage anything Charles and Victoria were trying to build, because after fifteen years in corporate strategy I knew revenge was usually less effective than letting incompetent people become responsible for the promises they had made. My attorney reviewed my employment agreement, confirmed that I could discuss my own professional history without disclosing confidential information, and advised me to keep every resignation email, performance review, and dated draft showing how the investment strategy had actually been developed.

For the first two weeks, Langford appeared perfectly fine.

Victoria posted photographs from investor dinners, Charles announced that she had been promoted to Senior Vice President of Growth, and an internal memo described my departure as part of “a planned leadership transition.” Former colleagues texted me privately, but I refused to ask for information because I wanted absolutely no suggestion that I was collecting intelligence from inside the company.

Then Martin called again.

His investment group had begun formal due diligence, and the process was not going well.

Victoria could repeat revenue targets, but she could not explain why my model required closing two underperforming distribution centers before acquiring a regional competitor. Charles insisted that those details were “implementation matters,” yet the investors wanted to know why projected margins depended on supplier concessions that had not been signed.

Those concessions existed only as preliminary negotiations.

I had spent months building trust with the suppliers involved, and every draft made clear that nothing became binding until final pricing and volume commitments were approved. Victoria apparently saw projected savings in my spreadsheet and assumed those numbers were guaranteed.

They were not.

A week later, Langford announced the acquisition anyway.

Charles used expensive bridge financing to purchase a struggling furniture chain in Pennsylvania before the investor money had officially closed, apparently believing the investment group would fund the deal once the transaction created momentum. Instead, Martin and the other investors delayed their commitment because due diligence had uncovered gaps between Victoria’s presentation and what the company could actually prove.

That delay immediately created pressure.

Langford now owned additional stores, leases, employees, inventory, and debt without the capital that was supposed to support the integration.

Charles finally called me.

“Claire, we need you for a short consulting engagement.”

I was sitting in my kitchen in Brooklyn when he said it, and for a moment I remembered every night I had stayed at the office until midnight building the plan he had handed to his daughter.

“What would I be doing?”

“Helping Victoria understand the implementation.”

“So I would teach her the strategy she told six investors she created?”

He became quiet.

“That is not a productive way to frame this.”

“It is an accurate way.”

Charles offered me twice my previous monthly salary for ninety days, but I declined because money had never been the reason I resigned. If I returned quietly, Victoria could continue taking credit while using me as invisible support whenever someone asked a question she could not answer.

Three days later, the investment group withdrew.

The company’s lenders reacted almost immediately.

Langford’s credit agreement contained leverage requirements that became difficult to satisfy after the acquisition, and the bank demanded a restructuring plan. Vendors shortened payment terms, two landlords asked for additional guarantees on newly acquired stores, and senior executives who had privately questioned Victoria’s expansion began leaving.

The collapse was not caused by one stolen presentation.

It was caused by leadership treating a complicated strategy like a set of decorative slides.

Two months after I left, Victoria called me herself.

Her voice sounded nothing like the woman who had told investors they did not need my ideas.

“Claire, I need the supplier model.”

“You already presented it.”

“I need the actual logic behind it.”

I looked out my apartment window.

“That was the part you told them they didn’t need.”

She started crying.

For a second, I almost felt sorry for her.

Then she said, “If this company fails, people will lose their jobs.”

She was right.

And that was exactly why she never should have stolen work she did not understand.

Langford Home Group did not vanish in some dramatic explosion, because billion-dollar companies usually die through paperwork, debt covenants, lost confidence, and a thousand meetings where people slowly realize the numbers no longer support the story. Over the next seven months, the company closed thirty-one stores, sold two warehouses, laid off hundreds of employees, and eventually entered a court-supervised restructuring that transferred control to its lenders.

Charles blamed interest rates.

Victoria blamed the investors.

Several business articles blamed the acquisition.

All of those things mattered, but the independent restructuring report later described the deeper problem more clearly: Langford had committed to an aggressive expansion without the operational leadership, supplier commitments, financing certainty, or internal controls required to execute it.

My departure was mentioned only briefly.

That was exactly how it should have been.

I had not destroyed their company.

I had simply stopped protecting it from people who believed reading my work was the same thing as understanding it.

Meanwhile, I spent several months deciding what I actually wanted to do next.

Martin Reeves eventually invited me to join one of his portfolio companies as chief strategy officer, but before accepting, I made one condition very clear: I would not discuss confidential Langford information, recruit their employees improperly, or use their crisis as a shortcut to build my reputation.

Martin smiled.

“That’s one of the reasons we want you.”

I accepted.

Nine months after the Four Seasons meeting, I attended an industry conference in Chicago where Charles was scheduled to speak on a panel about restructuring distressed retail businesses. He had lost control of Langford Home Group by then, although he remained on the board temporarily while lenders prepared a sale.

We saw each other outside the ballroom.

He looked tired.

“Claire.”

“Charles.”

For several seconds, neither of us said anything.

Then he surprised me.

“I should never have let Victoria present your work.”

“No.”

“I thought putting her in front of investors would prove she was ready.”

“It proved something.”

His expression tightened, but he nodded.

“She wasn’t.”

That was the first honest thing I had heard him say about the situation.

Victoria left the company shortly afterward.

According to a mutual acquaintance, she enrolled in an executive program and later joined a smaller real-estate firm where she held no senior title and actually worked beneath an experienced operating team. I never spoke to her again, and I did not need to, because whether she learned anything from the collapse was no longer my responsibility.

The old Langford headquarters in Manhattan was eventually sold as part of the restructuring.

A year after my resignation, I walked past the building on my way to another investor meeting and noticed workers removing the silver company letters from above the entrance. For a moment I remembered sitting in that conference room while Victoria clicked through my slides and confidently told six powerful investors that they no longer needed my ideas.

She had misunderstood what she stole.

The presentation was never worth millions by itself.

The value was in the relationships behind it, the assumptions I had tested, the negotiations that were unfinished, the people who knew how to execute each phase, and the judgment required to know when the plan should change.

Charles and Victoria believed ownership of the PowerPoint meant ownership of the strategy.

By the time they discovered the difference, the investors were gone, the debt was real, and the people capable of correcting the course had already walked away.

I never celebrated the layoffs or the losses suffered by employees who had done nothing wrong, because watching a company collapse is far uglier than corporate revenge stories make it sound.

But I never regretted leaving either.

The day Victoria stole my pitch, Charles expected me to stay in the room and help her succeed with it.

Instead, I quietly closed my laptop and walked out.

Their empire did not burn because I set it on fire.

It burned because the people holding the matches were convinced they did not need the woman who had spent years showing them where the fuel was.