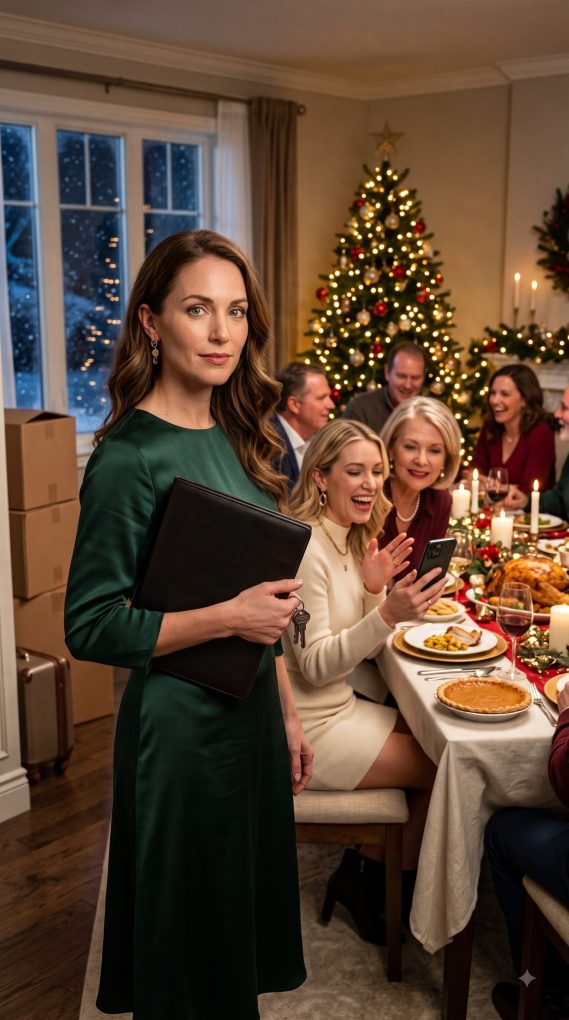
I overheard my mother telling the family that my $350,000 condo now belonged to my sister rent-free and that I could simply move into an apartment. I said nothing, served Christmas dessert, and let my sister celebrate online for three weeks. Then I quietly accepted a cash offer, sold the condo, and disappeared.
I was carrying a pecan pie into Christmas dinner when I heard my mother laughing behind the dining-room door.
“Claire won’t mind moving into an apartment. Her three-hundred-and-fifty-thousand-dollar condo belongs to Megan’s family now. Rent-free.”
I stopped so suddenly the serving knife slid across the plate.
My sister Megan laughed. “Jason already measured the second bedroom for Noah. I posted that we’re finally getting our forever home.”
Dad lowered his voice. “And Claire agreed to this?”
Mom snorted. “She doesn’t need that much space. She’s single. Megan has a husband and a child. Family comes first.”
My hands were shaking, but I walked into the room smiling.
“Dessert?”
Megan looked up from her phone. “Perfect timing.”
I served everyone pie.
Nobody mentioned my condo.
Neither did I.
For the next three weeks, Megan posted constantly. Photos of new furniture. Paint samples. A caption announcing that her “amazing parents” had given her family a mortgage-free home for the new year.
Mom even texted me asking when I planned to start packing.
I replied, Soon.
What she didn’t know was that the condo had always been solely in my name. No family trust. No shared ownership. No loan from my parents.
And two days after Christmas, I had called a realtor.
A cash buyer offered $342,000, waived inspection, and wanted a fast closing.
I accepted.
On January 16, I signed the deed, handed over every key I had, loaded my last suitcase into my car, and drove away.
At 9:12 the next morning, my phone exploded with calls.
Mom.
Dad.
Megan.
Jason.
Then Megan sent one message that made me pull over.
“You sold OUR house? Claire, you have no idea what Mom already signed.”
I stared at those words for a long time, because suddenly this wasn’t just about entitlement anymore.
Someone had put my name on something.
And I had never signed it.
For three weeks, I thought my family was simply planning to bully me out of my own home. Megan’s final message told me they had gone much further. I called the title company before I called anyone in my family back. The rest of what happened is in the comments.
I called the attorney who had handled my closing.
Rebecca Sloan answered on the second ring.
“Do you still have every document from the title search?” I asked.
“Yes. Why?”
“My sister says my mother signed something involving my condo.”
Rebecca went silent.
“Do not call your family yet.”
Twenty minutes later, she called back.
“Claire, the title was clean when you sold. Nothing transferring ownership was recorded.”
I exhaled.
Then she added, “But I found something else.”
Three weeks earlier, Megan and her husband, Jason, had applied for a $78,000 home-improvement loan through a local credit union.
The property listed as their residence was my condo.
Attached to the application was a document titled Family Occupancy and Future Conveyance Agreement.
It claimed I had agreed to let Megan’s family occupy the condo rent-free for five years and transfer ownership to her for one dollar at the end of that period.
At the bottom was my name.
Claire Bennett.
Signed in handwriting that almost looked like mine.
Almost.
“Who witnessed it?” I whispered.
Rebecca hesitated.
“Your father.”
I felt sick.
My phone rang again.
Mom.
This time I answered.
She didn’t say hello.
“You need to undo that sale immediately.”
“I can’t.”
“You can and you will. Megan has already ordered furniture.”
“That isn’t my problem.”
Mom’s voice dropped.
“We have an agreement.”
“You have a forged signature.”
Silence.
Then Dad came onto the phone.
“Watch what you accuse people of.”
“Did you witness my signature?”
“You gave your mother permission.”
“When?”
Another silence.
That was my answer.
Then someone began pounding on my old condo door while Megan screamed in the background.
I heard a man say, “Ma’am, I purchased this property yesterday.”
The buyer.
Megan had arrived with movers.
Mom shouted that he was trespassing.
He called the police.
By noon, two officers were standing in the hallway while Megan waved the fake agreement in front of them.
The buyer produced his recorded deed.
The officers told Megan she could not enter.
That should have ended it.
It didn’t.
Because while Rebecca was examining the loan paperwork, she found an attachment I hadn’t known existed.
A notarized statement claiming I had received $45,000 from my parents years earlier as part of the condo purchase and had promised them “equitable family rights” in return.
The notary stamp belonged to a man named Thomas Keller.
My mother’s cousin.
And the document wasn’t created three weeks ago.
It was dated four years earlier.
The month I bought the condo.
Rebecca sounded different when she called me that afternoon.
“Claire, I think this was planned long before Christmas.”
“How long?”
“Possibly from the day you bought the property.”
Then she said something that made my stomach turn.
“The credit union has another application connected to your name.”
I gripped my phone.
“For what?”
“A $126,000 line of credit.”
“Against what?”
Rebecca paused.
“Against the condo you just sold.”
And according to the application, I had personally authorized it.
What do you think will happen next? I’d love to hear your honest guess or reaction “I’d love to hear your opinions – your comments really make me happy and inspire me to keep writing.”
“I never applied for any line of credit,” I said.
“I know,” Rebecca replied. “But whoever submitted this had your Social Security number, a copy of your driver’s license, your previous tax return, and the closing statement from when you purchased the condo.”
I knew immediately where those documents had been.
Two years earlier, after I had surgery, Mom had spent a week at my condo helping me recover. My home-office filing cabinet contained copies of everything.
She had even joked that I was paranoid for keeping it locked.
Apparently, at some point, I had forgotten to lock it.
Rebecca told me to freeze my credit and file an identity-theft report immediately.
Then she contacted the credit union’s fraud department.
The $126,000 application had not funded yet.
That was the first good news.
The second was even better.
The application included an email account the person submitting it believed was mine.
It wasn’t.
It belonged to my mother.
She had used her own recovery phone number.
By six that evening, Mom had stopped calling me.
Dad had too.
Megan had not.
She sent twenty-three messages.
At first, she was furious.
You stole Noah’s home.
You embarrassed us in front of the movers.
You’re destroying this family over money.
Then the tone changed.
Please call me.
I didn’t know about the loan.
Mom told me you signed everything.
Finally:
Claire, I swear she told me you agreed.
I believed that part.
Megan was selfish, but she wasn’t careful enough to create four-year-old documents or complete a fraudulent loan application.
Mom was.
The next morning, I met Rebecca at her office.
She spread the paperwork across a conference table.
The original $45,000 statement had one enormous problem.
My bank records showed exactly where my condo down payment had come from: the sale of stock I had received through my employer.
My parents had contributed nothing.
Not one dollar.
Even worse for them, the alleged document said I signed it on March 8 four years earlier.
On March 8, I had been in Seattle attending a three-day corporate conference.
Hotel receipts, airline records, badge-access logs, and photos from the event placed me more than two thousand miles away.
Thomas Keller’s notarization claimed he watched me sign it in Columbus, Ohio.
“He could lose his commission over this,” Rebecca said.
“Is that all?”
“No.”
She turned over another page.
The handwriting expert retained by the title insurer had compared the signature with documents from my real closing.
The fake agreement appeared to be traced.
But Rebecca had found something even more damaging.
Metadata from the PDF showed that the supposedly four-year-old document had actually been created eleven days before Christmas.
My mother hadn’t planned the fraud when I bought the condo.
She had manufactured an old history to make the lie believable.
That afternoon, Detective Marcus Reed from the financial-crimes unit called me.
He asked only factual questions.
Who had access to my records?
Had I authorized Megan to live there?
Had I ever promised to transfer the property?
Had I signed either document?
“No,” I answered every time.
Then he asked whether I had given my mother permission to apply for credit in my name.
“Absolutely not.”
Three days later, the entire story finally surfaced.
Megan called me crying.
Mom had promised her the condo in October.
Megan and Jason had been struggling financially after Jason lost several months of work. Their lease was expiring in January.
Instead of telling them the truth, Mom had said I had already agreed to give up the condo.
“Why would you believe that?” I asked.
“Because she said you felt guilty.”
“For what?”
“For having more than me.”
I actually laughed.
Not because it was funny.
Because it explained thirty years of my mother’s thinking in one sentence.
Whenever I achieved something, Mom treated it like a family resource.
My college savings helped Megan after she dropped out.
My vacation days became emergency babysitting.
My guest room became free storage.
Now my home had become Megan’s reward for needing it more.
But Megan had another confession.
The home-improvement loan had been Mom’s idea too.
She had told Megan that because the condo would eventually belong to her, they should renovate before moving in.
Jason had questioned why my signature was required.
Mom told them I had already signed electronically.
Megan admitted she never saw me sign anything.
Then I asked about the $126,000 credit line.
She went completely quiet.
“I didn’t know the amount,” she whispered.
“The amount?”
“Mom said she was taking a small loan to help Dad.”
“For what?”
That was the real twist.
Dad had lost nearly $90,000 in a failed business investment and another $28,000 on credit cards he had hidden from everyone.
My parents were drowning.
The plan had never been only to give Megan my condo.
Mom intended to use my equity to rescue herself first.
She needed Megan’s family occupying the property because it helped create the appearance of a long-standing family arrangement if I objected later.
Christmas dinner hadn’t been the beginning.
It had been the announcement of a plan she believed was already finished.
The problem was that I sold before the loan funded.
The title company recorded my buyer’s deed before my mother could get anything else recorded.
Her entire scheme collapsed in less than twenty-four hours.
The credit union denied both applications and referred the files for investigation.
Thomas Keller admitted he had notarized the statement without seeing me sign it. According to his attorney, Mom told him it was “just paperwork between family members.”
That explanation did not help him much.
My parents hired attorneys.
Megan and Jason cooperated with investigators and turned over texts from Mom.
One message from December 11 said:
Claire will complain, but once you’re living there she won’t throw Noah out.
Another said:
We just need everything completed before she realizes what we’ve arranged.
I read those messages once.
Then I stopped.
I didn’t need more proof of how they saw me.
Months later, the criminal case was still moving through the system, but the financial damage had been contained. No money was ever taken against my condo. My credit reports were corrected. The buyer kept the property without any ownership dispute.
Megan eventually apologized.
A real apology.
No excuses.
I told her I accepted the apology but wasn’t ready to rebuild the relationship.
She cried.
I didn’t change my answer.
Mom sent me a four-page letter about forgiveness, family, grandchildren, mistakes, and how “one bad decision” shouldn’t erase a lifetime.
I mailed it back unopened.
Because it hadn’t been one decision.
It had been dozens.
Copying my documents.
Forging my signature.
Recruiting a relative to notarize it.
Promising my home to someone else.
Applying for credit in my name.
Sitting across from me at Christmas dinner while discussing where I would live after they took it.
That required planning.
I used part of the money from the sale as a down payment on a townhouse forty minutes away.
Only three people know my exact address.
None of them are related to me.
The first Christmas there, I invited two close friends and Rebecca.
We ate dinner around a table that was technically too large for the room.
Rebecca brought pecan pie.
When she carried it into the dining room, she smiled.
“You’re not going to make me serve this while someone secretly gives away your house, are you?”
I laughed harder than I had in months.
“No. I checked the deed this morning.”
And for the first time in years, Christmas felt peaceful.
I had spent most of my life believing that keeping the peace meant staying quiet while people crossed my boundaries.
I finally learned the difference.
Silence can be surrender.
But sometimes silence is simply what happens while you’re signing the paperwork.