My father’s text arrived while I was helping my twelve-year-old son, Noah, fill out a science program application. “We are taking back your kids’ college funds. We are bankrupt.” I read it twice. My parents, Richard and Diane Mercer, had spent years telling everyone they had set aside $80,000 for Noah and my nine-year-old daughter, Lily. It was supposedly untouchable money, a gift for their grandchildren’s future.
I called Dad immediately. He didn’t answer. Mom texted instead. “Please don’t make this harder. We’re in a terrible financial situation.”
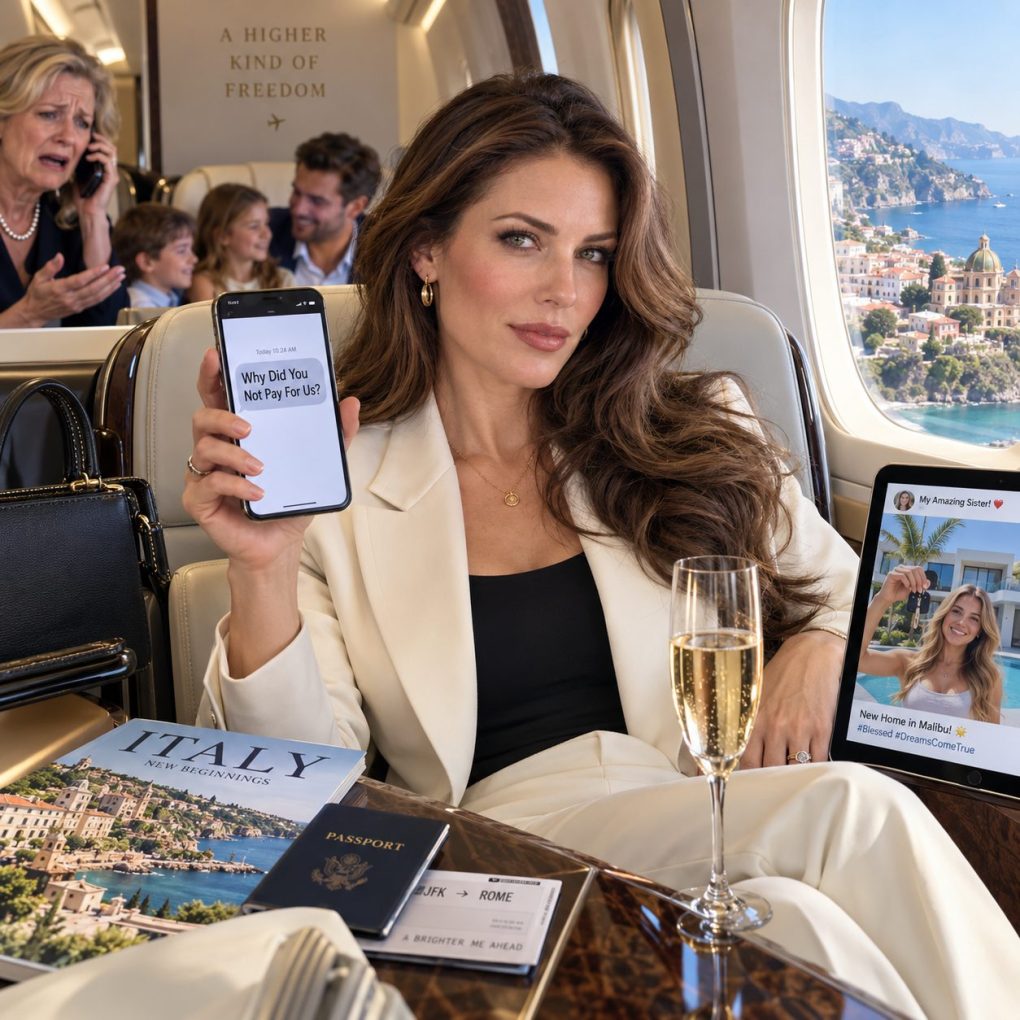
That might have scared me if I hadn’t opened Instagram thirty seconds later and seen my younger sister, Brooke, standing on a sunlit balcony in Malibu, holding keys beneath the caption: “Officially ours. Thanks, Mom and Dad, for making this dream possible.” I stared at the photo until my coffee went cold.
Brooke was thirty-two, married to a real estate agent named Trevor, and had never paid her own phone bill for more than six months at a time. Yet there she was in front of an ocean-view house recently listed for just under $1.4 million.
When Dad finally called, I asked one question. “Are you bankrupt, or did you buy Brooke a house?” He exhaled like I was the unreasonable one. “It’s complicated. Brooke needed stability. You and Daniel are doing well.”
Daniel, my husband, was a commercial electrician. I worked as an operations manager for a medical supply company. We did fine because we budgeted, skipped luxury cars, and spent ten years paying down our mortgage. Apparently, responsibility meant we needed less.
Then Dad said the part that changed everything. “The college accounts were always in our names. Legally, they’re ours.” I felt something inside me go quiet.
For years, my parents had treated us like a financial safety net. I covered Mom’s emergency dental bill. Daniel repaired their basement after a flood for free. We paid for rental cars, holiday groceries, and Brooke’s bridal shower because my parents were “temporarily stretched.” Now I understood where their money had been going.
I didn’t argue. I simply said, “Okay. If you’re bankrupt, you should probably stop spending.”
Three weeks later, Daniel and I boarded a first-class flight to Paris with Noah and Lily. We paid for it ourselves from a travel account we’d been building for four years. We spent ten days in Paris, Florence, and Rome, and for once I posted every beautiful photo.
The first message came from Brooke before we landed in Florence. “Wait. You went to Europe? Why didn’t you pay for us to come?” I typed back, “We are bankrupt.”
An hour later, Mom called crying. “How could you be so selfish? Your sister is devastated.”
Then she said something that made me stop walking in the middle of Piazza della Signoria. “You have no idea what your father had to do to get Brooke that house.”
For the first time, Mom didn’t sound angry. She sounded frightened. And when I asked what Dad had done, she went silent long enough for me to hear her breathing shake. Then she whispered a name I hadn’t heard in nearly eight years.
The name was Elaine Porter, my grandmother’s estate attorney. Grandma Ruth had died eight years earlier, leaving a small family trust from the sale of her house and investments. Dad was trustee. I had never paid much attention because he always said the money was “for later,” mostly for education and emergencies.
“What does Elaine have to do with Malibu?” I asked. Mom’s voice dropped. “Your father used money from the trust. He said he was allowed to. Elaine says he wasn’t.”
I stepped away from Daniel and the kids. The square around me suddenly felt too bright, too loud. “How much?” Mom began crying again. “I don’t know exactly. Richard said he could replace it after selling investments. Then Trevor’s financing fell apart, and they needed the closing money immediately.”
Before I could answer, another call came through from a California number. I almost ignored it, but the voicemail appeared seconds later: “Emily, this is Elaine Porter. Please call me before speaking to your father about the Ruth Mercer Family Trust.”
That night, from our hotel room in Florence, I called her. Elaine said Dad had requested a $310,000 distribution claiming it was for “beneficiary housing needs.” The trust allowed limited distributions for health, education, maintenance, and support, but Brooke’s luxury vacation property did not clearly qualify.
Worse, Dad had represented that both beneficiaries agreed. “I never agreed to anything,” I said. Elaine paused. “I know. That is why I’m calling.”
Then came the twist that turned my anger into fear. Elaine had a document in her file bearing my electronic signature. It stated that I consented to the distribution.
I sat on the edge of the bed while Daniel watched my face. I told Elaine I had never seen the document. She asked me to forward examples of my signature and warned me not to confront anyone until she reviewed the authentication records.
Five minutes after we hung up, Dad texted: “Call me now. We need to fix this as a family before outsiders make it ugly.” Then Brooke messaged: “Whatever that lawyer tells you, remember Dad did this for all of us.”
For all of us? The next morning, Elaine emailed one additional page. At the bottom was a handwritten note from Dad to the trust administrator: “Emily will be reimbursed through the Malibu property after transfer.”
But according to the county record Elaine attached, the property had already been transferred. The owners listed were Brooke Mercer Hale and Trevor Hale.
My name was nowhere on the deed.
And attached to the transfer file was a second document with my forged signature—this one giving up any future claim to the property.
I didn’t answer Brooke. I forwarded both documents to Elaine, put my phone facedown, and took my children to breakfast. For the first time in years, I understood that “keeping the peace” in my family mostly meant staying quiet while someone else decided what I could afford to lose.
By the time we landed back in Los Angeles, Elaine had spoken with counsel for the trust administrator. The trust was temporarily frozen, and Dad had been ordered to provide records for every distribution he had authorized during the previous three years. He called nineteen times before we reached baggage claim.
I finally answered once. “Dad, I’m not discussing the trust directly with you. Elaine has my attorney’s information.” His voice hardened. “Attorney? Emily, nobody stole from you.” I said, “You submitted my signature on documents I never signed.” After a long silence, he replied, “I was trying to protect the family.”
That sentence told me almost everything.
The records filled in the rest. Grandma Ruth’s trust required written consent from both adult beneficiaries for principal distributions above $100,000. Dad had copied my signature from an old estate-planning form and uploaded it to the consent page. Electronic records showed the document had been created on his home computer and submitted from his internet connection.
The $310,000 trust withdrawal was only part of it. Dad had also taken roughly $80,000 from the 529 accounts he controlled for Noah and Lily. Then he and Mom opened a $170,000 home-equity line against their Pasadena house. Together, that money gave Brooke and Trevor enough cash to close after ordinary financing collapsed.
The rest of the $1.4 million purchase price came from an expensive private loan Trevor found through an investor. Interest, taxes, insurance, and maintenance pushed the house above $11,000 a month. Brooke’s glamorous “gift” was a financial fire burning behind an ocean view.
My parents were not bankrupt when Dad sent that text. They were overextended and desperate to keep the Malibu deal alive. Calling themselves bankrupt gave Dad an excuse to empty the college accounts before I could object.
Then Mom admitted the part that hurt more than the money. They had expected Daniel and me to rescue them once the payments became impossible. At a meeting in Elaine’s office, she whispered, “We thought you’d understand. You’re the stable one.”
I looked straight at her. “So because I’m stable, my children were supposed to lose their college money?” Brooke interrupted, “Nobody said they’d lose it forever. Dad was going to put it back.” I asked, “With what money?” Nobody answered.
Trevor finally admitted he had told Dad the Malibu property would appreciate fast enough to refinance within a year. He also claimed luxury short-term rentals would cover most of the payments. But local restrictions, insurance requirements, and the lender’s terms made that plan far less profitable than he had promised.
Brooke turned toward him. “You told me the rental income was basically guaranteed.” Trevor stared at the table. That was the second secret: Brooke knew our parents were helping and knew the college accounts had been touched, but Dad had called it a temporary bridge. She had not known he forged my consent or used trust money without authority.
That did not make her innocent. She had still posted the house like a trophy, then asked why I had not paid for her European vacation. But it changed what I wanted. I wanted the money returned, the documents corrected, and the pattern to end.
My attorney proposed a settlement before anyone filed suit. Dad would resign permanently as trustee. An independent corporate trustee would take over. Brooke and Trevor would list the Malibu house immediately. From the proceeds, the trust would be reimbursed first, then Noah and Lily’s college accounts would be restored, including estimated taxes and penalties.
Dad resisted until Elaine explained the alternative: a court petition to remove him, a formal accounting, personal liability for trust losses, and a separate civil claim over the forged consent. I did not threaten him. The records were enough.
The Malibu house sold four months later for less than Brooke and Trevor had paid. After commissions, interest, and closing costs, there was not enough equity to repair everything. My parents used part of their brokerage account to cover the trust shortfall. They sold the Pasadena house, paid off the home-equity line, and moved into a smaller condo.
Noah and Lily’s college accounts were restored to the balances they would have had before Dad’s withdrawal. Daniel and I moved the money into accounts my parents could never control again. We also stopped treating promised family money as part of our children’s future.
Brooke and Trevor separated before the Malibu sale closed. She rented a two-bedroom apartment in Ventura and took a full-time job with a property management company. For the first time since college, she paid every bill herself. She did not change overnight, but something shifted when the luxury photos disappeared and the invoices became real.
Six months later, she asked me to meet for coffee. She did not ask for money or defend Dad. She simply showed me that she had deleted the Malibu post. “I thought that house proved they loved me more,” she said. “I didn’t realize what it cost everyone else.”
I told her, “The house wasn’t the worst part. The worst part was everyone deciding my family could absorb the damage because we usually survive it.” She nodded. For once, she did not argue.
My relationship with my parents never returned to what it had been. Dad sent long apologies. Mom kept asking when things would feel normal again. I told her I was not interested in normal if normal meant guilt, secrecy, and treating boundaries like betrayal. We still saw them sometimes, but there were no loans, joint accounts, or vague financial promises.
The strangest part was that the Europe trip—the thing Mom had called selfish—became one of our happiest memories. Lily still talks about the tiny gelato shop near the Arno. Noah keeps a photo of Daniel pretending to understand a French train map. Every dollar of that trip came from money we had saved ourselves.
A year after Dad’s first message, another text appeared. “I finally understand why you said we were bankrupt.” I replied, “You weren’t bankrupt, Dad. You were spending things that didn’t belong to you.” He answered, “I know.”
That was the closest thing to closure I ever got, and it was enough. The inheritance I wanted to give my children was never an account balance controlled by someone else. It was the certainty that their future would not be traded away to keep another adult comfortable.
We paid for our own trip. We protected our children’s future. And for the first time in my life, I stopped confusing generosity with permission to be used.