For years, my mother-in-law treated my credit card like a family inheritance.
Vacations.
Restaurants.
Designer clothes.
Spa weekends.
Even the $4,800 sofa sitting in her living room.
Every charge landed on an account connected to mine.
My ex-husband, Ryan, always had an explanation.
“She’ll pay us back.”
“She’s having a rough month.”
“She’s family, Claire.”
After twelve years of marriage, I had heard those words enough times to know what they really meant.
You will pay because saying no is inconvenient for me.
So when the judge finalized our divorce at 10:14 on a Monday morning, I walked out of the courthouse, sat inside my car, and called the bank.
The authorized-user card belonging to Patricia Bennett was canceled immediately.
No warning.
No discussion.
No final courtesy call.
I drove back to my apartment, made coffee, and slept better than I had in months.
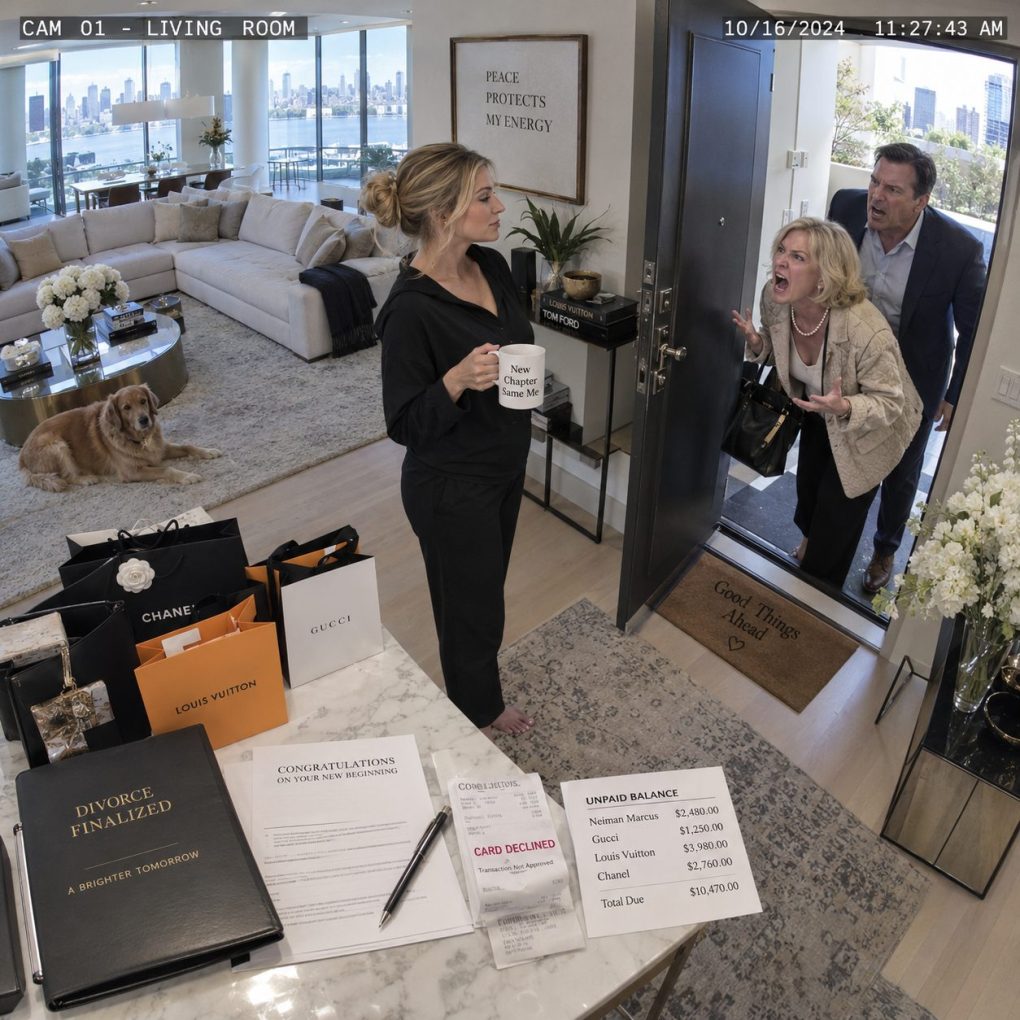
At 10:31 that night, someone started pounding on my door.
Patricia.
Ryan stood behind her.
She was still wearing a restaurant coat and looked furious.
“You canceled my card!”
I took another sip of coffee.
“Yes.”
“You embarrassed me in front of twelve people! The waiter said it was declined.”
Ryan stepped forward.
“Claire, just turn it back on tonight. We’ll sort this out tomorrow.”
I almost laughed.
The marriage was over, and he was still asking me to finance his mother.
“Why would I finance a family I’m no longer part of?”
Patricia’s face reddened.
“That card was part of our arrangement.”
“No. It was part of my account.”
“You gave it to me.”
“I made you an authorized user. I didn’t promise lifetime sponsorship.”
Ryan lowered his voice.
“Mom depends on that card.”
That sentence interested me.
“How much does she depend on it?”
Neither answered.
I already knew.
Three weeks before the divorce hearing, my accountant had reviewed five years of statements because our attorneys were separating marital expenses.
Patricia had charged more than $96,000.
Ryan knew.
What he apparently did not know was that I had discovered something else.
Several payments Patricia claimed were ordinary purchases had been refunded.
But the refunds never returned to my account.
They went somewhere else.
A digital wallet.
Then into a bank account ending in 7719.
An account I had never seen before.
I set my coffee down.
“Ryan, ask your mother about account 7719.”
Patricia stopped breathing.
Ryan turned toward her.
“What account?”
She recovered quickly.
“I have no idea what she’s talking about.”
I opened my phone.
“Really?”
Then I showed Ryan the transfer history.
More than $38,000 in refunds had been redirected over eighteen months.
His expression changed.
“Mom?”
Patricia looked toward the elevator.
That was when I realized she had not come to my apartment because she was embarrassed at dinner.
She had come because canceling the card had shut down something far more profitable.
Ryan asked Patricia again about account 7719. This time she snapped that it was “personal” and none of his business. I almost admired the answer. For years, everything I earned had apparently been family business, but the account receiving money from my card was private.
I told them both to leave. Patricia refused until I mentioned building security. Ryan finally pulled her toward the elevator, promising he would call me the next morning. “Don’t,” I said. “Have your attorney call mine.”
My accountant, Melissa Grant, already had most of the records. The pattern was surprisingly simple. Patricia would buy expensive items using my card, return some of them later, and request that refunds be issued through alternate payment methods or store credits whenever merchants permitted it.
She then converted gift balances, resold merchandise, or routed refunds through accounts she controlled. Not every transaction worked that way, but enough did that the total became significant.
Ryan claimed he knew nothing.
At first, I believed him.
Then Melissa found payments from account 7719 into another account jointly held by Ryan and Patricia.
That account had been opened four years earlier.
My divorce disclosures had never listed it.
Suddenly, this was no longer about an overindulged mother-in-law.
My attorney requested additional financial discovery.
Ryan called me that evening.
“Claire, you’re blowing this out of proportion.”
“You had an undisclosed account with your mother.”
“It wasn’t mine. My name was there for emergencies.”
“Then producing the statements should be easy.”
Silence.
The next week, they arrived.
Ryan had used money from that account too.
Golf trips.
Sports tickets.
A down payment on a vintage motorcycle he told me a friend had loaned him.
More than once, he had complained that I was “too controlling about money” while quietly benefiting from funds his mother extracted from my card.
My anger changed after that.
It became clarity.
During our marriage, I was the higher earner. I owned a commercial interior-design firm and handled most household expenses. Ryan worked in sales and earned a respectable salary, but he loved appearing wealthier than he was.
Patricia loved it even more.
My income had become the machinery behind their image.
Their attorney tried to characterize the hidden account as informal family bookkeeping.
Mine asked why it had been omitted from sworn disclosures.
That question ended the argument quickly.
The divorce decree had already been entered, but our settlement contained provisions requiring disclosure of concealed marital assets and allowing the court to revisit specific financial divisions if either party had intentionally hidden them.
Ryan suddenly wanted to negotiate.
He offered to repay half the disputed money if I agreed not to return to court.
I refused.
Not because I wanted revenge.
Because I wanted a complete accounting.
Then Melissa found the oldest transfer.
It dated back almost five years.
Two days later, she called me.
“Claire, there’s something you should see.”
She sent one document.
It was the application used to open account 7719.
Patricia was the primary holder.
Ryan was secondary.
And the initial deposit—$25,000—had come directly from our joint savings account.
The authorization carried my electronic signature.
I had never signed it.
The forged authorization changed everything. My attorney immediately notified Ryan’s counsel and requested that the original banking records be preserved. Ryan insisted Patricia had handled the paperwork and told him I had approved the transfer.
Patricia blamed Ryan.
For the first time in twelve years, mother and son stopped protecting each other.
A forensic review showed that Patricia had initiated the original transfer using credentials available from a household computer. Ryan had later discovered the account but continued using money from it instead of telling me.
That distinction mattered legally.
It mattered to me too.
Ryan had not created the deception, but once he found it, he chose to benefit from it.
We returned to court.
The judge did not reopen our entire divorce. Instead, the concealed funds and disputed transactions were addressed under the disclosure provisions already built into our settlement.
Patricia was required to repay a substantial amount connected to unauthorized use and diverted refunds. Separate allegations involving the false authorization were referred for further investigation.
Ryan forfeited part of the property settlement he would otherwise have received because the court found that he had failed to disclose an account containing marital funds.
He was furious.
Outside the courthouse, he said, “Was destroying my relationship with my mother worth it?”
I stared at him.
“I didn’t create the account.”
He looked away.
That was the last serious conversation we had.
Patricia eventually entered a repayment agreement and faced consequences related to the unauthorized financial activity. The case never became the dramatic prison story she told relatives I was trying to manufacture.
Reality was less theatrical.
She sold the BMW she could no longer afford.
Canceled two vacations.
Moved from her oversized townhouse into a condo.
For the first time in years, she lived on money that actually belonged to her.
Ryan struggled too.
Without my income subsidizing his lifestyle, he downsized quickly.
He sold the motorcycle.
Left the private golf club.
Started paying his own credit-card balances.
None of those things made me happy.
But they made something clear.
For years, I had mistaken financial dependence for generosity.
Generosity is freely chosen.
What they had built around me was expectation.
Six months later, Patricia mailed me a handwritten letter.
Most of it explained why she had believed the arrangement was fair.
Near the end, however, she wrote one honest sentence:
I became accustomed to spending your money because nobody ever made me stop.
I kept that sentence.
Not because I wanted to punish her.
Because it reminded me of my own responsibility.
Boundaries do not become unnecessary simply because people dislike them.
The following Christmas, I traveled alone to Santa Fe.
I booked a beautiful hotel.
Ordered room service.
Bought myself a ridiculous cashmere coat.
And paid the bill with the same account Patricia once treated as hers.
When the charge notification appeared on my phone, I smiled.
For twelve years, I had been told that family meant sharing everything.
The divorce taught me something better.
Family can receive generosity.
Family can ask for help.
But nobody earns permanent access to another person’s money simply by becoming accustomed to it.
Canceling that card took less than two minutes.
Learning why I should have done it years earlier took much longer.