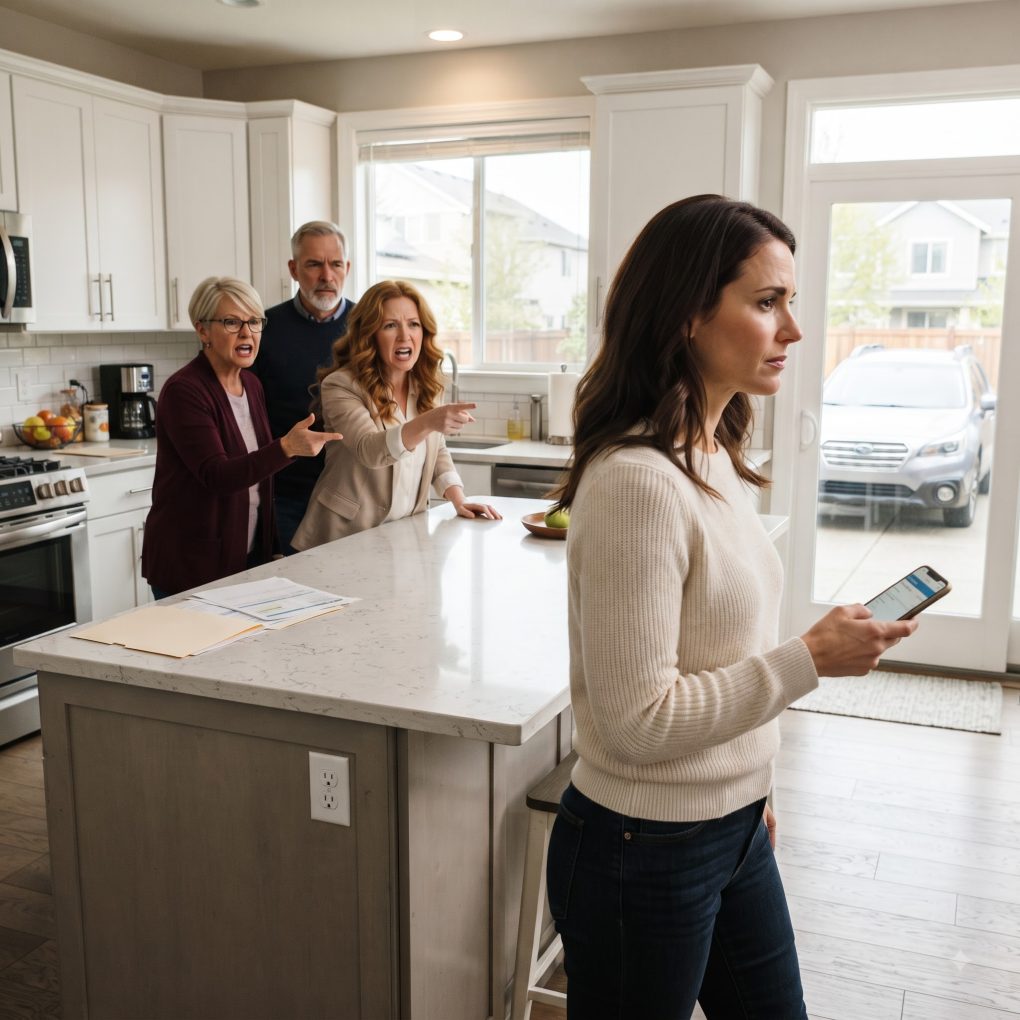
“They screamed at me for refusing to empty my savings for my sister’s startup. I stayed silent, walked away, and let them find out the harsh truth this morning.”
“HOW DARE YOU REFUSE TO HELP YOUR SISTER?”
My mother’s voice shook the kitchen as she slammed her hand against the table.
My sister, Madison, sat beside her with tears in her eyes.
“It’s only $180,000,” she said. “You have more than enough.”
I stared at them.
My father leaned forward. “Your savings are just sitting there. Madison has a real business. She needs one chance.”
“I’m not emptying my savings for her.”
The room went silent.
Madison’s face hardened. “You’ve always been selfish.”
That hurt more than I expected.
For years, I had quietly saved every dollar after working two jobs and living below my means. I had never told my family exactly how much I had.
They assumed I was comfortable.
They had no idea what those savings were actually for.
Mom stood up. “Family helps family.”
“Then help her yourselves.”
Dad’s face turned red.
“You ungrateful—”
I picked up my coat.
Madison suddenly shouted, “If you walk out, don’t ever call yourself my sister again!”
I stopped at the door.
Then I turned around.
“I won’t.”
And I walked away.
I expected angry texts.
Instead, my phone stayed completely silent.
Until 7:42 the next morning.
A bank officer called.
“Ms. Harper, I need to confirm something immediately. Did you authorize your sister to submit your financial documents for a business loan?”
My stomach dropped.
“What documents?”
There was a pause.
“Your savings statements. Your tax records. And a signed authorization giving her access to your account.”
“I never signed anything.”
The officer lowered his voice.
“Then you need to contact your attorney today.”
I froze.
Because suddenly, my sister’s demand for $180,000 didn’t sound like desperation anymore.
It sounded like a plan.
And when I opened the email attachment the bank had sent me, I saw the signature Madison had submitted.
It looked exactly like mine.
Except for one tiny detail.
The date beside it was from a day when I had been—
Teaser
I thought my family was simply angry because I refused to fund Madison’s dream. I was wrong. The bank had uncovered something much bigger, and the document they sent me was only the beginning. By the time I learned where the money was really going, someone had already made a move that could cost me everything.
Except for one tiny detail.
The date beside it was from a day when I had been out of state.
I was in Portland for a work conference.
There was no way I had signed anything in Ohio that afternoon.
I immediately called my attorney, Rebecca Mills, and sent her the document.
She called back twenty minutes later.
“Don’t contact your sister yet.”
“Why?”
“Because this authorization gives Madison permission to access more than your savings.”
My chest tightened.
“What else?”
“Your investment accounts. Your brokerage statements. And apparently, information connected to a property you own.”
I sat down.
“What property?”
Rebecca went quiet.
“The house you inherited from your grandmother.”
My pulse jumped.
That house was supposed to remain untouched. I had planned to sell it later and use the proceeds for my retirement.
Madison had never even asked about it.
At least, not directly.
Then Rebecca said something that made my blood run cold.
“Someone has already submitted paperwork connected to that property.”
“What kind of paperwork?”
“A preliminary loan application.”
“For how much?”
“Four hundred and fifty thousand dollars.”
I couldn’t speak.
Madison wasn’t trying to borrow my savings.
She was trying to use my assets to secure a much larger loan.
I called my parents.
Dad answered.
“What now?”
“Did Madison tell you she submitted my financial information to a bank?”
Silence.
Then Mom said, “She said you agreed to help.”
“I never agreed.”
“She was desperate!”
“Mom, she forged my signature.”
Dad suddenly became defensive.
“You don’t know that.”
“I have proof.”
Another silence.
Then my father said something that made my hands go cold.
“Maybe you should have helped her when she asked.”
I hung up.
Rebecca advised me to freeze my accounts and place a fraud alert on my credit.
I did exactly that.
Then, around noon, Madison called.
Her voice was strangely calm.
“You really went to a lawyer?”
“Yes.”
“You could have just helped me.”
“You forged my signature.”
“I didn’t forge anything.”
“Then explain the document.”
She hesitated.
“I was told you had already approved it.”
“Who told you?”
Another pause.
Then she whispered, “Dad.”
My heart sank.
“What?”
“I thought he had spoken to you.”
Before I could respond, she added, “You don’t understand what happens if this loan falls apart.”
“What happens?”
She started crying.
“Dad already used part of your financial information to secure the investors.”
I stared at the phone.
Investors?
This wasn’t just Madison’s startup.
There were other people involved.
Then I heard a man’s voice in the background.
“Madison, stop talking to her.”
She immediately hung up.
Rebecca arrived at my house less than an hour later.
She placed a folder on my table.
Inside was a copy of the loan application.
And beneath Madison’s name was another signature.
My father’s.
But this one wasn’t connected to a loan.
It was attached to a document transferring control of my grandmother’s property.
Rebecca looked at me.
“There’s something else you need to know.”
She turned the page.
“The transfer was filed three weeks ago.”
My blood ran cold.
Three weeks ago was before Madison ever asked me for the $180,000.
Which meant this had never been about her startup.
It had been about getting control of my property first.
I stared at the document until the words blurred.
Three weeks.
That was the part I couldn’t get past.
Madison had sat across from me at my parents’ kitchen table and called me selfish because I wouldn’t hand over $180,000.
But apparently, the plan had started weeks earlier.
Rebecca pulled the folder closer.
“Don’t panic. The filing doesn’t automatically mean they’ve taken ownership.”
“Then what does it mean?”
“It means someone attempted to create a legal transfer.”
“Using my father’s signature?”
“Possibly. We need to verify everything.”
I remembered my grandmother’s house.
It wasn’t a mansion.
It was an ordinary two-story home outside Columbus, Ohio, with an old porch, a narrow driveway, and a kitchen where my grandmother used to make pancakes every Sunday.
After she died, she left it to me.
My parents had always said the house was worth more than I realized.
I had never cared much about the money.
To me, it was the last physical thing I had that belonged to her.
Rebecca explained that the document appeared to give my father limited authority over the property.
But the signature and notarization were questionable.
“There was no valid power of attorney on file,” she said.
“So how did this get recorded?”
“That is what we’re going to find out.”
She contacted the county recorder’s office.
The answer came later that afternoon.
The paperwork had been submitted electronically by a title company.
And the title company had been instructed by a private lender.
The same lender connected to Madison’s startup.
That changed everything.
My sister hadn’t simply tried to get money from me.
Someone had apparently built a financing structure around assets she didn’t own.
And my parents were involved.
At least, that’s what it looked like.
That evening, my mother called.
Her voice was trembling.
“Please come over.”
“No.”
“Please. You need to hear this from us.”
“Did Dad sign that document?”
“I don’t know.”
“Mom.”
She started crying.
“I thought your father was only helping Madison.”
I closed my eyes.
“Helping her do what?”
There was a long silence.
“Keep her company alive.”
That was the first time my mother admitted there was a problem.
Madison’s startup had been struggling for months.
She had raised some money from friends and small investors, but her expenses had grown quickly.
Payroll.
Rent.
Equipment.
Marketing.
Then one major investor pulled out.
Madison needed immediate funding.
The lender had offered a large business loan, but only if she could provide substantial collateral.
She couldn’t.
So someone suggested using my grandmother’s property.
My mother insisted she never understood the legal details.
My father, however, had apparently told everyone that I would eventually cooperate.
“He said you wouldn’t let your sister fail,” Mom whispered.
I felt something inside me break.
“So he decided for me.”
Mom didn’t answer.
The next morning, Rebecca and I met with the title company.
The paperwork was worse than we expected.
The supposed authorization from me had been submitted alongside copies of my driver’s license, tax documents, bank statements, and a letter that claimed I had agreed to provide financial support.
The letter was professionally written.
The signature looked convincing.
But the notary stamp contained an obvious problem.
The notary commission number belonged to someone whose license had expired months earlier.
Rebecca immediately pointed it out.
“This document should never have been accepted.”
The title company began an internal investigation.
Meanwhile, the lender froze the transaction.
But then another problem surfaced.
The $180,000 Madison had requested wasn’t the real target.
It was the amount she needed to convince me to voluntarily reveal enough financial information to support the larger loan.
The moment I understood that, I felt sick.
The request had been bait.
Madison knew I would refuse.
She also knew my parents would pressure me.
And if I finally agreed to “just help with paperwork,” she could obtain what she needed.
But there was still one question.
Who created the fake documents?
Rebecca eventually got the answer.
The electronic submission had come from an account belonging to Madison’s business manager.
His name was Trevor Hale.
Trevor admitted he had prepared the paperwork.
But he claimed Madison told him she had permission.
Then came the twist.
He produced a text message from my father.
It said:
“She’ll never agree directly. Just prepare everything. I’ll handle her.”
I read it three times.
My father had planned to pressure me into signing.
But Trevor had gone further and submitted documents without my permission.
That distinction mattered.
Legally, it changed the entire situation.
The lender withdrew from the deal.
The title company corrected the property record.
And Rebecca filed formal notices disputing the fraudulent documents.
But I still hadn’t spoken to Madison.
Until she showed up at my house.
She looked exhausted.
“I didn’t know Dad would do that.”
I didn’t answer.
“I swear.”
“You knew he was using my property.”
“I knew he was asking about it.”
“That isn’t the same thing.”
She looked down.
“No.”
I stepped aside and let her enter.
She sat on the couch, crying quietly.
“I was desperate.”
“I know.”
“I thought if the company survived, everything would work out.”
“For you.”
She looked at me.
“For everyone.”
I shook my head.
“You didn’t ask me for help. You tried to make me responsible for your choices.”
She had no answer.
Then she said something I hadn’t expected.
“I don’t want the company anymore.”
I stared at her.
“What?”
“I shut it down.”
The startup was already insolvent.
Even without the fraudulent loan, Madison couldn’t cover the remaining expenses.
She had spent nearly everything she raised.
Employees were owed money.
Vendors were demanding payment.
Investors were threatening legal action.
For the first time, she wasn’t talking about saving the company.
She was talking about facing what had happened.
I asked where Dad was.
She looked away.
“He left.”
“Where?”
“I don’t know.”
Rebecca later learned that my father had hired an attorney.
He denied authorizing any fraudulent filing.
He claimed he believed I had agreed to help.
The case eventually became a civil dispute involving the title company, the lender, Madison’s business, and the people responsible for submitting the documents.
Because the property transfer had never been validly completed, I kept ownership of my grandmother’s house.
The bank accounts were secured.
My credit was protected.
And the fraudulent authorization was formally removed from the records.
Months later, Madison and I met at a small coffee shop.
She looked different.
Not physically.
Just quieter.
“I owe you an apology,” she said.
“You do.”
“I kept telling myself you were selfish because you wouldn’t give me what I needed.”
I listened.
“But the truth is, I was angry because you had something I didn’t.”
“What?”
“Control.”
That word stayed with me.
She had watched me save money carefully for years.
She had watched me refuse to spend beyond what I could afford.
She had mistaken discipline for selfishness.
My parents had done the same thing.
They believed because I had savings, those savings were somehow available to the family.
They forgot something simple.
Having money doesn’t mean someone else has a claim to it.
Madison eventually found work at another company.
She paid what she could toward the debts from her failed business.
She also signed a written agreement acknowledging that she had no ownership or financial interest in my grandmother’s property.
My mother and I slowly began speaking again.
My father took longer.
For almost a year, we barely communicated.
Eventually, he sent me a letter.
He didn’t ask for money.
He didn’t defend himself.
He simply admitted that he had convinced himself he was “protecting the family.”
I wrote back only once.
I told him that protecting family doesn’t mean taking away their choices.
I never emptied my savings for Madison.
I never lost my grandmother’s house.
And I never gave my family another opportunity to decide what my money was supposed to be used for.
The strangest part was that the original argument had started over $180,000.
But that amount was never the real issue.
The real issue was whether I had the right to say no.
I did.
And when my family finally discovered the reason I had refused to empty my savings, they learned something I should have told them years earlier:
My savings weren’t sitting there waiting for someone to take them.
They were protecting my future.
And after everything they had done, I decided that future would no longer include anyone who believed my boundaries were something they could negotiate.