My son’s voice cut through the phone before I could even say hello. “Mom, don’t drive over. There isn’t room for you at Christmas.” I was already standing in my hallway with two wrapped gifts under one arm and a pecan pie cooling on the counter. For a second I thought he was joking. Then I heard my daughter-in-law, Vanessa, laughing in the background.
Daniel lowered his voice. “Her parents, her sister, the kids, everyone’s coming. Vanessa wants this year to be just her family. The real guests.”
The real guests.
I looked at the red overnight bag by my door. Three days earlier, Daniel had asked me to bring extra folding chairs because he expected a crowd. I had also paid for the new dining table sitting in that house, the same house I had bought twelve years earlier after his father died.
“Of course,” I said. “I hope you all have a warm holiday.”
He sounded relieved. “Thanks for understanding.”
I hung up, put the pie in my refrigerator, and returned the gifts to the closet.
Ten minutes later, Vanessa texted me a photo of the dining room. The table was covered in gold plates, candles, and place cards. I zoomed in without thinking. There were sixteen names. One empty chair stood at the far end.
Then another message appeared.
Sorry, Margaret. Family tradition. Hope you understand.
I did understand. Just not what she thought.
Two weeks later, Daniel called while I was sorting tax papers at my desk.
“Mom, call me back. It’s about a loan. It’s urgent.”
I let the phone ring.
In front of me was the deed to Daniel’s house, still in my name.
When Daniel’s business failed years earlier and the bank refused him a mortgage, I had purchased the property outright for $438,000. He and Vanessa paid me monthly, casually calling it “the mortgage,” but ownership had never been transferred.
That morning I noticed something strange in the payment records. For eleven months, deposits had come from a company I did not recognize. Three were labeled “loan reimbursement” instead of rent.
I searched county records.
A financing notice was connected to my address.
My hands went cold.
I called my attorney, Rachel Stein. Twenty minutes after I sent her the documents, she called back.
“Margaret, do not sign anything Daniel sends you.”
“There’s a loan application using the property as collateral,” she said. “Your signature appears on a preliminary authorization.”
“I never signed one.”
She added that the lender also had a copy of my driver’s license and a tax form I kept locked in my home office.
Rachel went silent.
At 9:14 that night, someone pounded on my front door.
Daniel stood outside in the rain, pale and furious. Vanessa was behind him, clutching a folder.
“Mom,” he said, “we need you to fix something before the bank opens tomorrow.”
Vanessa shoved the folder toward me.
On top was a notarized document bearing my name.
Beneath my forged signature was a line I had never seen before.
Transfer of ownership effective upon execution.
I did not take the folder.
“Who prepared this?”
Daniel glanced at Vanessa. She answered first. “It’s only temporary. We need the house transferred so the bank can approve a bridge loan.”
“We?”
“My father’s company had a cash-flow problem,” she said. “The loan will be repaid in ninety days.”
I stared at Daniel. “You tried to pledge my property to rescue her father’s business?”
He rubbed both hands over his face. “I thought the house was basically ours.”
“Basically is not a legal word.”
Vanessa’s expression hardened. She said I had accepted payments for years and had promised Daniel the property eventually. Then she accused me of using the deed to control them.
I closed the door.
Daniel called six times before midnight. I answered none of them.
The next morning Rachel and I met at her office. She had already contacted the bank’s fraud department. The application requested $310,000, supposedly for renovations to Daniel’s home. The money, however, was scheduled to be wired to an LLC owned by Vanessa’s father, Martin Cole.
The bank’s file showed my identification had been uploaded from an email account created only six days earlier, along with a notarized statement claiming I had personally approved the transfer.
Only three people had legitimate access to those documents: me, Rachel, and Daniel.
Rachel checked the notary’s name.
Evelyn Price.
I knew it immediately. Evelyn was Vanessa’s aunt.
At noon Daniel finally left a voicemail.
“Mom, please don’t report this yet. Martin has people depending on him. If the financing collapses, everything gets worse.”
Not I’m sorry.
Not I didn’t know.
Don’t report this.
Rachel froze the application. An hour later, she discovered something that changed the case completely. The transfer document Vanessa brought to my house was not the only version. Another deed had been electronically submitted to the county four days before Christmas.
It showed that I had transferred the property to Daniel for ten dollars.
The filing had been rejected because the legal description contained one incorrect parcel number.
Someone had almost stolen my house because of a typing mistake.
Then Rachel found the twist neither of us expected.
Daniel was not listed as the person who prepared the deed.
Martin was.
I drove straight to Daniel’s house, against Rachel’s advice. Christmas decorations still hung over the porch. Vanessa opened the door and tried to block me, but I heard shouting from the kitchen.
Martin was inside.
So were Vanessa’s mother, brother, and aunt Evelyn.
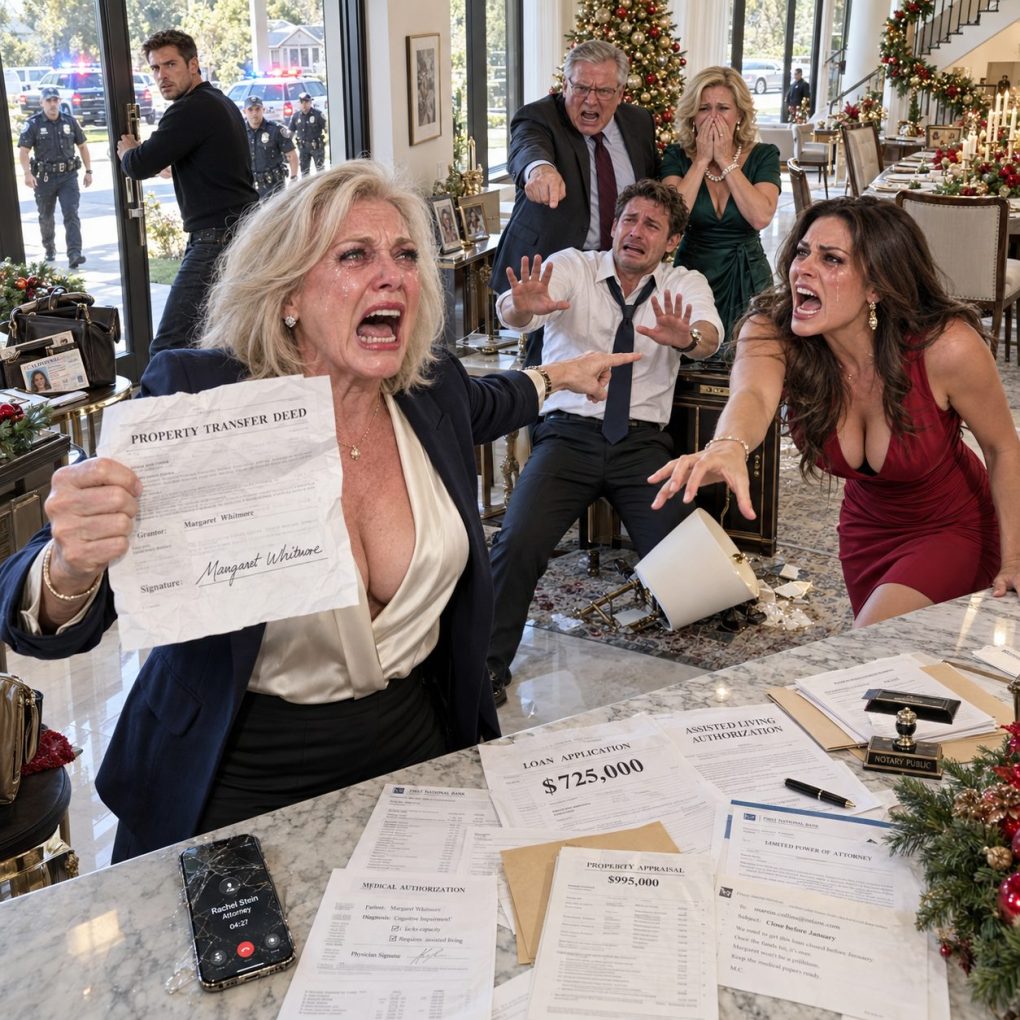
The “family-only Christmas” had not simply been a celebration. They had gathered there while I was excluded, and according to papers spread across the kitchen island, they had been planning the financing that same weekend.
Daniel came downstairs looking sick.
I held up the rejected deed. “Did you know about this?”
He said nothing.
Vanessa stepped between us. “You were going to give him the house anyway.”
“That wasn’t my question.”
Martin stood and calmly told me the business would collapse unless the loan closed within forty-eight hours. He said hundreds of thousands of dollars were already committed and warned that stopping the transaction would “hurt everyone.”
Then my phone rang.
Rachel.
I answered on speaker.
“Margaret, leave that house now. I found a second application. This one is not for $310,000.”
Martin’s face changed.
Rachel continued.
“It’s for $725,000, and Daniel signed it yesterday.”
I turned toward my son.
Rachel said the bank had received a fabricated appraisal valuing the house at nearly one million dollars and a letter claiming I was moving permanently into assisted living. Attached to it was a medical authorization carrying another signature that looked like mine.
I felt the room tilt.
“I’m not sick,” I said.
No one answered.
Then I noticed my handbag on the entry table. It was open. I had zipped it before coming inside.
My wallet was half pulled out.
Daniel followed my eyes and whispered, “Vanessa, what did you do?”
Before he could speak, someone behind me locked the front door.
What do you think will happen next? I’d love to hear your honest guess or reaction.
I turned slowly. Vanessa’s brother, Owen, stood with his hand still on the lock. “Open it,” I said.
Martin lifted both palms as if he were the reasonable person in the room. “Nobody is threatening you, Margaret. We just need five minutes without lawyers turning this into a disaster.”
Rachel’s voice came sharply through my phone. “Margaret, do not agree to anything. Leave now.”
Vanessa snatched the phone from my hand.
Daniel moved faster than I expected. He grabbed her wrist, the phone slipped, and it struck the hardwood floor. The screen cracked but the call stayed connected.
“Stop!” Daniel shouted.
Owen stepped toward him. Daniel shoved him back. Owen shoved harder, sending Daniel into the edge of the console table. A lamp crashed beside him.
Then Martin pointed at the papers on the kitchen island.
“This is exactly why we need to finish this tonight. Sign the transfer, the bank releases the money, and nobody loses anything.”
“I lose my house.”
“It’s Daniel’s house in every way that matters.”
“No. It is the house I bought.”
Vanessa’s face twisted with anger. “And you’ve reminded us of that every time you wanted something.”
I stepped toward my phone.
Owen blocked me.
That was the moment fear finally replaced disbelief.
I looked directly at Daniel. “Move him.”
Daniel’s eyes filled with tears. “Owen, open the door.”
Martin snapped, “Daniel, think about what happens if this falls apart.”
Daniel looked at him, then at Vanessa.
“What exactly happens?”
The room went quiet.
Martin tried to wave the question away, but Daniel repeated it.
Vanessa finally screamed, “We lose everything!”
And the truth came out.
Martin’s construction company had been insolvent for nearly a year. He had concealed unpaid payroll taxes, two lawsuits, and a private loan secured by equipment he no longer owned. Vanessa had quietly given him more than $90,000 from the account she shared with Daniel. When that disappeared, she opened credit lines using Daniel’s business information. Daniel discovered those debts in October.
Instead of telling me, he joined the plan.
The first idea had been to ask me for a conventional loan against the house. Martin believed I would refuse if I knew where the money was going. So Vanessa suggested transferring the property to Daniel first, arguing that I had always intended to give it to him eventually.
When they learned a legitimate transfer required my cooperation, Evelyn offered to notarize a deed without my presence.
The rejected deed was their first attempt.
The wrong parcel number saved me.
After that failure, they created the $310,000 application and forged my authorization. But Martin’s liabilities were growing so quickly that $310,000 was no longer enough. The plan expanded into the $725,000 loan.
The inflated appraisal came from an appraiser Martin had worked with before. The assisted-living letter was meant to explain why I would not appear at closing. The medical authorization and a forged limited power of attorney were designed to let Daniel act for me if the lender demanded additional signatures.
And Christmas had been their working meeting.
Vanessa’s entire family had gathered in my house, eaten dinner at my table, and discussed how to take the property while I sat alone three miles away.
I looked at Daniel. “Was that why I wasn’t invited?”
He lowered his head.
Vanessa answered for him. “We couldn’t have you there asking questions.”
Daniel whispered, “I didn’t know they were going to go this far.”
I stared at him. “You signed a seven-hundred-and-twenty-five-thousand-dollar application yesterday.”
“I thought we could repay it.”
“That is not the same as not knowing.”
Martin stepped between us. He said the lender needed one final owner verification. That was why Daniel had been calling me about “a loan.” If I confirmed the transfer, the money could fund the next morning. If I refused, the bank would stop everything and Martin’s creditors would begin seizing assets.
Then sirens sounded outside.
Rachel had heard enough before Vanessa dropped the phone. She had called police from another line while keeping ours open.
Owen unlocked the door immediately, but it was too late.
Two officers entered after I opened it. Martin began explaining that it was a family financial disagreement. Vanessa said I had misunderstood. Evelyn claimed the notary issue was only a paperwork mistake.
Then Rachel’s voice rose from the floor.
“Tell them to preserve every document on that kitchen island.”
I showed them my identification and the deed records Rachel had emailed me. I explained that I had never signed either transfer document, never authorized either loan, and had been prevented from leaving after confronting them.
When the officer asked who had locked the door, no one answered.
Daniel did.
“Owen locked it,” he said. “Vanessa took her phone. My father-in-law brought the loan papers. And I signed the second application.”
Vanessa stared at him as if he had struck her.
“You coward.”
Daniel looked destroyed. “No. I was a coward before.”
The officers did not arrest everyone on the spot. Financial crimes required records, interviews, and verification. But they photographed the documents, took statements, and told Martin, Vanessa, Evelyn, and Owen not to remove or destroy anything relevant. Because of the physical confrontation and the locked door, Owen was taken in for questioning that night.
Daniel asked if he could come home with me.
I said no.
Over the next forty-eight hours, the bank froze both applications. The county recorder flagged the property for suspected fraud. Rachel filed formal notices challenging any attempted transfer and instructed me to freeze my credit.
Then the digital evidence began to surface.
Martin had emailed draft deeds to Vanessa.
Vanessa had sent scans of my driver’s license to Evelyn.
Evelyn had texted, “I can stamp it if Margaret isn’t there, but make sure the date matches.”
Daniel had sent Martin my tax documents.
The appraiser had received a spreadsheet telling him what value the property “needed” to reach.
And on Christmas night, while I was home alone, Vanessa had sent a message to the family group chat.
Once Margaret is out of the chain, we can close before January.
Daniel had replied with one word.
Good.
When Rachel showed me that message, I stopped making excuses for him.
For years I had treated Daniel’s bad decisions as accidents that happened around him. A failed business. Missed payments. Credit-card debt. Emergency repairs. Each time I had rescued him because I thought helping my child was what a mother did.
But a forty-year-old man who hands over his mother’s identification and signs a fraudulent loan is not a child trapped in someone else’s mistake.
He had made a choice.
Three weeks later, Daniel asked to meet at Rachel’s office.
Vanessa had moved in with her parents. Martin’s company had stopped operating. Investigators had begun tracing other suspicious transactions, including loans involving two properties owned by elderly relatives. Evelyn’s notary commission had been suspended pending the investigation.
Daniel slid an envelope across the table.
Inside was a written confession prepared with his criminal attorney. He admitted giving my documents to Vanessa and Martin, knowing the deed had not been legitimately signed, and signing the larger loan application because he believed the money would save both Martin’s company and his own finances.
Then he admitted something I had not known.
The $725,000 was not only for Martin.
About $220,000 was supposed to pay Daniel’s business debts and personal credit lines.
He had been willing to put my house at risk to erase his own failures too.
“I’m sorry,” he said.
I believed he was sorry.
That did not mean I trusted him.
I told him I loved him, but I would never again finance his life, guarantee his debts, share my financial documents, or let him treat my property as an inheritance he had already received.
The legal process lasted months.
The forged deed never became valid because the first filing had been rejected and the later attempts were stopped before recording. The bank canceled the loan applications and cooperated with investigators. My title remained untouched.
Martin eventually pleaded guilty to charges connected to fraud and falsified loan documents after investigators found evidence extending beyond my property. Evelyn admitted performing an improper notarization and lost her commission. Vanessa entered a plea agreement related to identity theft and document fraud. Owen’s case concerning the confrontation was handled separately after he admitted locking the door and preventing me from leaving.
Daniel cooperated with investigators. His attorney negotiated an agreement that included restitution obligations, probation, financial restrictions, and testimony about how the documents had been created. I did not ask prosecutors to excuse him, and I did not ask them to punish him more harshly. I simply told the truth.
Then came the house.
Because the deed was mine, Rachel helped me begin the legal process to end Daniel and Vanessa’s occupancy. I did not change the locks overnight or throw their belongings onto the lawn. We followed the required notice procedure.
Daniel moved out quietly.
Vanessa fought at first, insisting that years of payments gave her ownership. Her attorney eventually acknowledged what the documents showed: the payments had never transferred title.
I sold the house six months later.
The buyer was a young couple with a little girl who ran through the empty dining room laughing while their parents signed the final papers.
I used part of the proceeds to buy a smaller home near my sister, one with a garden and a guest room that belonged to no one by default. I changed my passwords, locked my credit files, and stopped keeping family paperwork in places Daniel knew about.
The following December, Daniel called me.
He did not ask for money.
He did not ask to come over.
He only said, “Mom, I know I don’t have the right to expect an invitation. I wanted to wish you a merry Christmas.”
I looked around my kitchen. My sister was chopping vegetables. Two neighbors were arguing cheerfully over a pie. Rachel had sent flowers. There were eight place settings on my table.
Every chair was meant for someone who wanted me there.
“Merry Christmas, Daniel,” I said.
There was a long pause.
“I’m trying to become someone you can trust again.”
“I hope you do.”
I meant it.
But forgiveness, I had learned, was not the same as access. Love was not a signature. Family was not permission to take what belonged to someone else.
After the call, I opened the drawer where I kept the closing statement from the sale.
For months, the deed had felt like a weapon they had forced me to use.
Now it felt like something simpler.
Proof that when they told me I was not one of the real guests, I finally stopped begging for a seat at a table I had paid for.
I returned to my kitchen, pulled out a chair, and sat down among people who had already made room for me.