“My mother-in-law gave me 30 days to kick me out of ‘her son’s’ house. She had no idea I bought it 14 months ago—until my husband called the very next morning.”
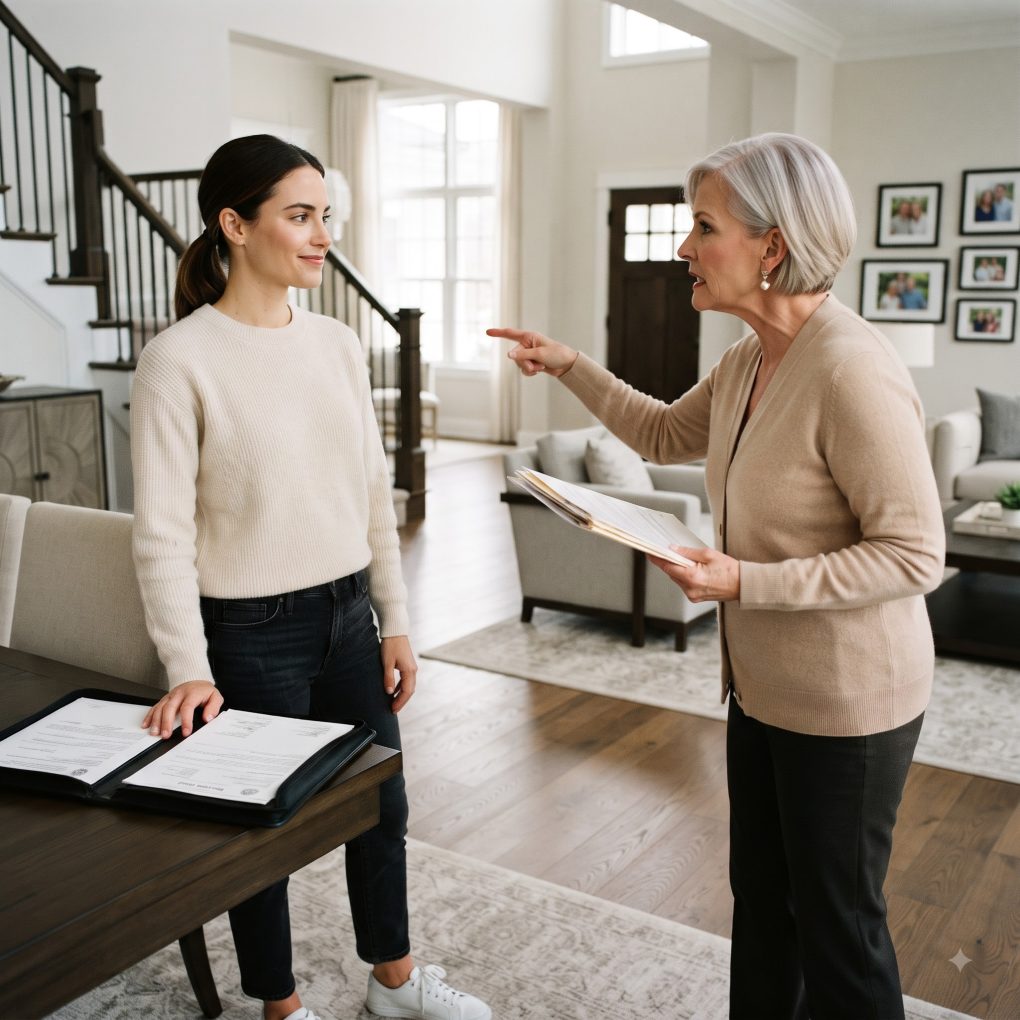
“You have thirty days to get out of my son’s house.”
My mother-in-law, Linda, stood in my kitchen holding a folder of papers like she had just delivered a court order.
I looked at my husband, Mark.
He didn’t defend me.
He just stared at his coffee.
I swallowed my anger and nodded. “Okay.”
Linda smiled.
For months, she had acted like our marriage was temporary and the house belonged to her son alone. She criticized everything I bought, moved my things without asking, and told relatives I was “living off Mark.”
What she didn’t know was that I had bought the house fourteen months earlier.
Not Mark.
Me.
My name was on the deed. My money had paid the down payment. Even the mortgage came from an account Mark barely knew existed.
I had kept it quiet because Mark once told me, “A wife shouldn’t use money to control her husband.”
So I never told him.
Not even after Linda began telling people I would eventually be thrown out.
That afternoon, I walked upstairs and quietly opened the small safe in our bedroom.
Inside was the original deed.
I touched it once, then closed the safe.
I wasn’t going to argue with Linda.
I wasn’t going to expose anything yet.
I wanted to see what she and Mark would do next.
The following morning, my phone rang at 7:12 a.m.
It was Mark.
I answered.
There was silence for two seconds.
Then he said the one thing I never expected:
“Why did my mother tell me the house isn’t mine?”
My stomach dropped.
Because there was something else he had discovered overnight.
Something that had nothing to do with the deed.
And suddenly, I realized Linda wasn’t the only person hiding something.
“Mark, what are you talking about?”
His breathing was uneven.
“Mom said you bought the house.”
I said nothing.
He lowered his voice. “Is that true?”
“Yes.”
Another silence.
“How long?”
“Fourteen months.”
I expected anger.
Instead, he laughed once—short and bitter.
“Then we’re in bigger trouble than I thought.”
I sat down.
“What happened?”
Mark told me that Linda had gone to his office the previous evening, furious after their conversation. She demanded that he “take control” of the house before I could do anything with it.
But when Mark checked the county property records, he discovered something that shocked him.
The house wasn’t just in my name.
There was also a home-equity loan application attached to a recent filing.
Using his information.
And he hadn’t applied for one.
“Mom said you were trying to steal the house from me,” Mark said. “Then she told me she had paperwork proving I was supposed to be the owner.”
I opened my laptop.
“I never signed anything transferring ownership.”
“I know.”
His voice cracked.
“Because the signature on the document isn’t yours.”
My hands went cold.
“Whose is it?”
Mark hesitated.
“Mom’s.”
I immediately called an attorney I had used when purchasing the house.
He reviewed the document and told me not to confront Linda yet.
The signature wasn’t legally valid.
But there was something worse.
Someone had submitted the paperwork using information from our household financial records.
Someone had access to our tax documents, account numbers, and copies of identification.
Then Mark whispered:
“I found Mom’s notebook.”
“What notebook?”
“She wrote down every payment you made toward the house.”
My chest tightened.
Why would Linda have been tracking my payments?
Mark continued.
“She also wrote something beside your name.”
“What?”
He went silent.
Then he read it aloud.
“Once she leaves, refinance immediately.”
I stared at the kitchen table.
Suddenly, the thirty-day deadline made sense.
Linda hadn’t been trying to make me homeless.
She was trying to make me leave before I discovered what she had planned.
Then Mark said something that changed everything.
“There’s one more page.”
“What does it say?”
His voice dropped.
“It has your name… and the name of another man.”
For several seconds, neither of us spoke.
“Who?” I finally asked.
Mark exhaled.
“Evan Cole.”
I recognized the name.
He was a mortgage broker who had helped Linda refinance her own house years earlier.
But I couldn’t understand why his name was written beside mine.
Mark told me he was coming home.
An hour later, he walked through the front door carrying the notebook.
Linda’s handwriting covered several pages.
Dates.
Amounts.
Bank account numbers.
Notes about the house.
And beside my name were instructions about when I would supposedly move out.
Mark placed the notebook on the table.
“I found this in Mom’s room.”
I turned the first page.
There were calculations showing how much equity the house had gained since I bought it.
Linda had tracked everything.
Every mortgage payment.
Every renovation.
Every increase in property value.
Then I saw the line that made my stomach turn:
“After divorce—force sale or refinance.”
I looked at Mark.
“Your mother knew we were going to divorce?”
He shook his head.
“She wanted us to.”
That was the part that hurt him most.
Linda had apparently spent months telling Mark that I was controlling, secretive, and financially manipulative.
She convinced him that the house was “really his” because he was her son.
And when he refused to confront me, she escalated.
The fake transfer document was meant to create the appearance that Mark owned the property.
The plan was simple.
Get me out.
Convince Mark the house belonged to him.
Then refinance it or sell it.
The problem was that Linda had underestimated one thing.
The house wasn’t merely a place we lived.
It was legally mine.
And I had records proving every dollar.
My attorney contacted the mortgage company and county office.
The questionable filing was flagged.
The refinancing attempt was frozen.
Evan Cole was contacted as part of the investigation.
At first, he claimed he had only processed documents submitted to him.
But when the investigators compared the paperwork with the original records, inconsistencies appeared everywhere.
The identification used wasn’t mine.
The signature wasn’t mine.
And several documents contained information that only someone close to our family could have accessed.
Linda.
When Mark confronted her, she didn’t deny knowing about the refinancing plan.
Instead, she shouted that she had been “protecting her son.”
“You were going to lose everything because of her!” Linda screamed.
Mark stood quietly.
“No, Mom.”
He looked at me.
“She was the one paying for everything.”
Linda’s face changed.
For the first time, she couldn’t pretend she had misunderstood.
She had known.
She had simply believed that because I was married to her son, what belonged to me somehow belonged to him.
The thirty-day eviction threat disappeared.
So did Linda’s control over our finances.
Mark and I eventually separated.
Not because of the house.
Because the situation forced both of us to admit how badly trust had been damaged.
I kept the property.
The mortgage stayed in my name.
And I stopped explaining myself to people who had already decided I was guilty.
Months later, I stood in the same kitchen where Linda had once told me to pack my things.
There was no shouting.
No dramatic confrontation.
Just silence.
My own silence.
The kind that comes when you finally understand that you don’t have to prove your worth to anyone.
Linda had believed she was giving me thirty days to leave.
She never realized that, fourteen months earlier, I had already made the decision that mattered most.
I had put the house in my own name.
And this time, I wasn’t quietly nodding because I was afraid.
I was nodding because I already knew exactly where I stood.