The CEO threatened to have security remove me from my father’s company at 9:17 on a Monday morning. Twenty minutes later, he discovered I controlled the votes that could remove him. Until then, everyone in the conference room believed I had inherited just enough stock to watch them sell the company without me.
My father, Richard Bennett, had founded Bennett Industrial Systems in Cleveland, Ohio, thirty-four years earlier. When he died unexpectedly, company counsel told me his estate included twelve percent of the outstanding shares. The CEO, Martin Keller, controlled nineteen percent and had support from several directors.
Three months after the funeral, Martin called a special board meeting. A private-equity firm had offered $86 million for the company. Martin supported the sale, as did four directors. I opposed it because the buyer planned to close our Ohio manufacturing operation and move production elsewhere.
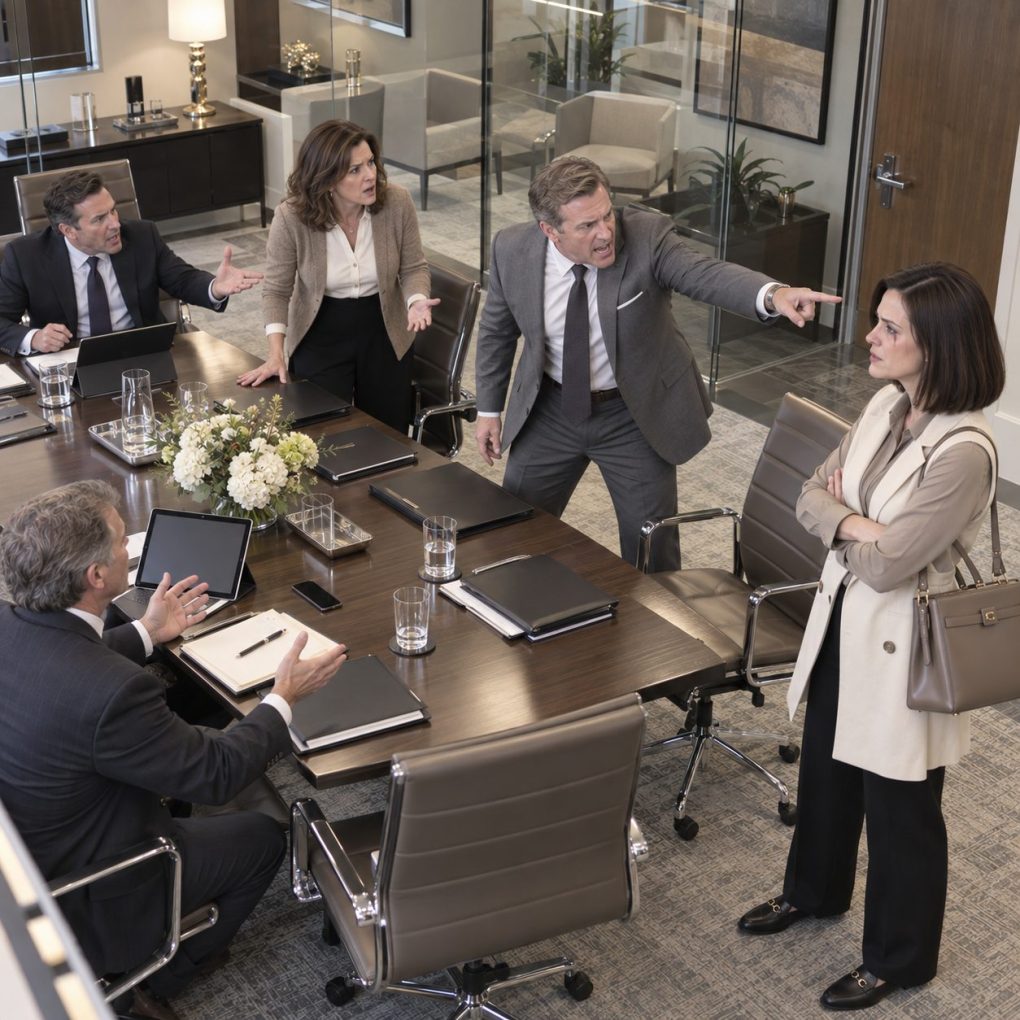
Martin smiled when I objected. “Twelve percent doesn’t give you veto power, Emily.” Then he suggested I take my inheritance, accept the premium, and let experienced executives handle the company.
I placed my father’s old leather folder on the table. Martin refused to look at it. When I said there were unresolved voting-right questions, he stood and told his assistant to contact security if I continued disrupting the meeting.
So I closed the folder and walked out.
Nobody understood why I wasn’t fighting. The answer was waiting downstairs. My father’s former attorney, seventy-one-year-old Samuel Grant, had called me the previous evening after learning about the proposed sale.
Samuel arrived carrying records from a trust my father had created eleven years earlier. My personal twelve-percent stake was only part of the structure. Another twenty-seven percent of Bennett Industrial had been transferred into the Bennett Family Voting Trust.
My father had remained voting trustee while alive. Under the trust agreement, control did not pass to the CEO, the board, or even my father’s estate after his death. The successor trustee named in the signed document was me.
At 9:38, Samuel entered the conference room with me and handed certified copies to corporate counsel. Martin’s expression changed as the attorney read the controlling provision aloud. I didn’t own thirty-nine percent personally, but I held voting authority over the trust’s twenty-seven percent plus my twelve percent. More importantly, another shareholder agreement gave the trust decisive rights over any sale of substantially all company assets. The transaction they were celebrating couldn’t proceed without my approval.
Nobody spoke for several seconds. Martin finally accused Samuel of producing an outdated agreement. Samuel calmly handed corporate counsel the amendment confirming the trust remained active. The company’s own records showed the twenty-seven-percent block had never been transferred back to my father personally.
The problem was administrative confusion. After Dad became ill, distributions from the trust had been reported alongside his other holdings. Several executives apparently assumed those shares would become ordinary estate assets after his death. They never examined the underlying voting documents before planning the sale.
Corporate counsel immediately suspended the meeting. He explained that no vote on the acquisition could proceed until the company verified the trust, shareholder agreement, and required approvals. Martin protested that weeks of negotiations had already occurred.
“That doesn’t change the governing documents,” Samuel replied.
I didn’t celebrate. I asked for the buyer’s complete proposal, including employment projections, plant-closure plans, executive compensation arrangements, and every side agreement involving existing management.
That last request changed the atmosphere.
Two days later, my attorney discovered that Martin would receive a substantial transaction bonus if the acquisition closed. He also had a consulting agreement offering him eighteen months of additional compensation after the sale.
Neither arrangement automatically proved misconduct, and both had been disclosed to certain directors. But I had never been shown them despite being the successor voting trustee whose approval was required for the transaction.
I requested an independent review before considering any sale. Martin called me privately and said I was risking millions because I was emotional about my father’s legacy. I told him preserving Dad’s name wasn’t my argument.
My concern was economic. Bennett Industrial was profitable, carried manageable debt, and had recently secured two major contracts. The buyer’s offer represented an attractive immediate payout, but its restructuring plan would eliminate more than 180 local jobs.
I also learned my father had rejected an earlier approach from the same buyer fourteen months before his death. Samuel produced correspondence showing Dad believed the company could increase its value significantly by completing a new automated production line.
That project was now nearly finished.
At the next board meeting, I didn’t demand that everyone reject the acquisition. I demanded something more reasonable: ninety days for independent financial advisers to evaluate the offer, the new production line, competing strategic alternatives, and management conflicts.
This time, nobody threatened to call security. The board approved the review. Martin vote
The independent report arrived eleven weeks later. It didn’t claim the private-equity offer was fraudulent or worthless. Instead, it concluded that selling immediately could undervalue the company if the new production line performed as projected.
The advisers recommended testing the market before making an irreversible decision. Two strategic buyers later expressed interest, while a third proposed purchasing only one division without closing the Cleveland plant.
Meanwhile, the board reviewed Martin’s handling of the original transaction. The issue wasn’t simply his potential bonus. Directors became concerned that he had pushed for an accelerated vote while failing to make sure all controlling shareholders and trustees received complete information.
Martin insisted he had relied on internal ownership summaries. That explanation protected him from accusations that he knowingly ignored the trust, but it raised another question: why had the CEO of a closely held company supported an $86 million transaction without verifying who possessed approval rights?
The board eventually negotiated Martin’s departure. There was no dramatic security escort. His employment agreement was reviewed, a separation package was reached, and an interim CEO took over while the directors conducted a search.
I didn’t become CEO. I was a financial analyst, not an industrial executive, and inheriting voting power did not magically qualify me to run a manufacturing company. Instead, I accepted a board seat and remained trustee of my father’s shares.
Six months later, the automated production line exceeded its initial efficiency target. Revenue improved, and the company hired twenty-three additional employees. We still considered acquisition proposals because refusing every sale forever would have been just as irresponsible as accepting the first one.
Eventually, Bennett Industrial entered a strategic partnership with a larger manufacturer. The agreement provided new capital and distribution access while keeping the Cleveland operation open. Our shareholders received liquidity without surrendering the entire company.
Samuel attended the meeting where the final documents were signed. Afterward, he handed me my father’s leather folder. Inside was a handwritten note Dad had left with the trust documents years earlier.
It said simply, “Control is responsibility, not a prize.”
I understood then why Dad had structured the company the way he did. He hadn’t secretly crowned me his successor or ordered me to preserve everything he built. He had given someone he trusted enough authority to force important decisions into daylight.
Months earlier, Martin had looked at my twelve-percent inheritance and decided I was irrelevant. I had walked away from that conference room because arguing wouldn’t change the documents. My father had already made sure that when the company faced its biggest decision, nobody could silence my vote by calling security.