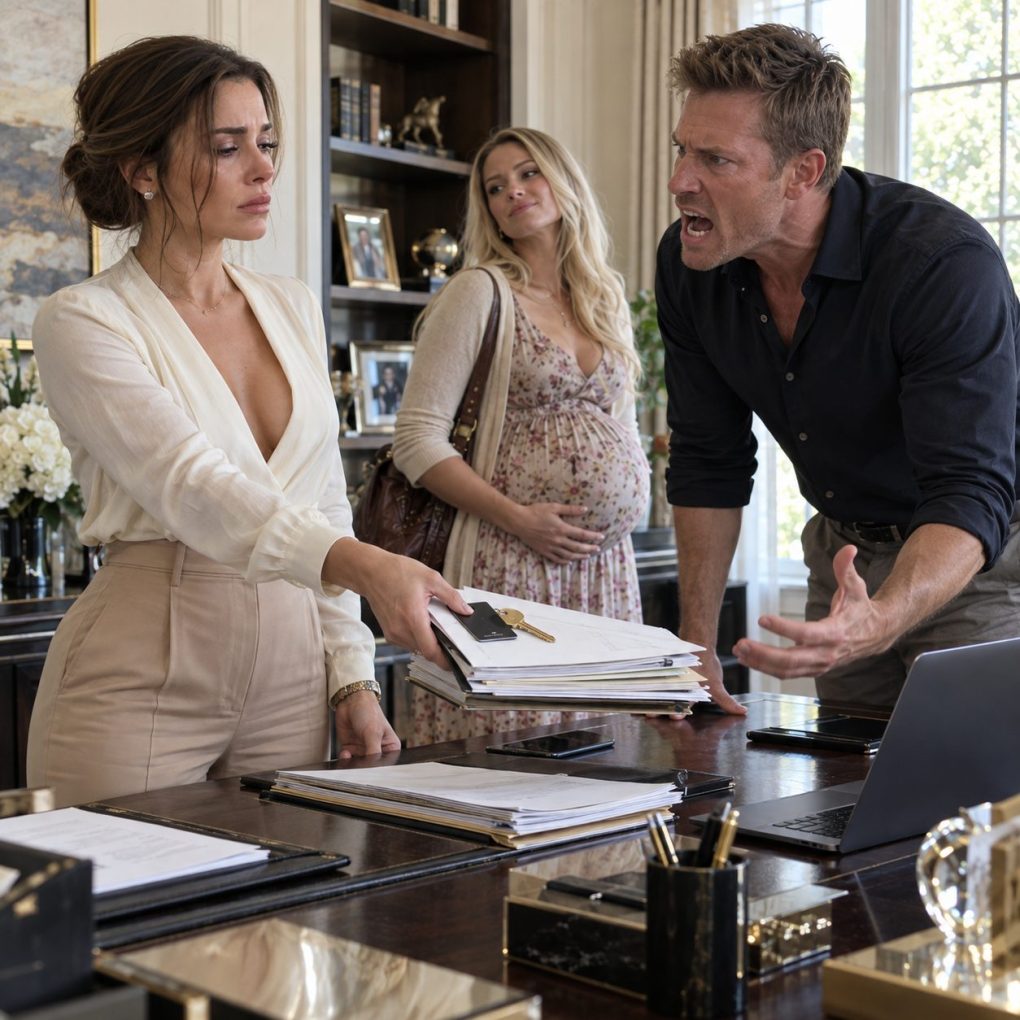
“Unlock the payment account, Claire. Now.”
My husband’s voice carried across our kitchen while his pregnant ex stood behind him with a suitcase. On my phone, our company’s largest client was demanding an explanation for a $480,000 invoice I had never approved.
Daniel shoved a laptop toward me. “Sign the release. Madison needs a place to stay, and I need you to stop making a scene.”
Madison stared at the floor. Seven months pregnant, one hand pressed against her stomach, she looked less like a woman who had won and more like someone waiting for a door to open.
“Why is her name on the invoice?” I asked.
“Because she did the consulting,” Daniel said.
“She left construction accounting two years ago.”
His smile vanished. “I built this company.”
I had spent six years keeping that company alive: negotiating contracts, fixing payroll, and explaining away Daniel’s promises whenever he made them before checking whether we could deliver. Our house had become another problem he expected me to manage. But I would not authorize a payment I could not explain.
I closed the laptop. “Then you can explain it to the client.”
Daniel snatched my phone and held it above my reach. “You’re done as operations chief. No salary, no company card, no office. Give me your keys.”
I took the keys off my ring and set them beside his laptop. Then I opened my personal email, forwarded the client’s message to my attorney, and told Daniel I was resigning my officer role in writing. I still owned forty percent of the company. He could take my job; he could not take my shares with a speech in our kitchen.
For the first time, Madison looked directly at me. Her eyes filled. She whispered, “Claire, don’t leave me alone with him.”
Daniel turned so fast his chair scraped the tile.
Then a second message appeared on the laptop. The client had attached the payment authorization Daniel wanted me to sign.
It already carried my signature.
He had taken my keys, my job, and my place in our home. But the signature on that document could threaten much more than our marriage. Madison knew how it got there—and Daniel was determined to keep her quiet.
I stared at the signature. It was a scan of one I had used on a contract months earlier, right down to a stray ink mark near the C.
“Where did you get that?” I asked Daniel.
“It’s yours. Stop pretending.”
Madison gripped the back of a chair. “He copied it,” she said.
Daniel slammed the laptop shut. “Go upstairs.”
She did not move. Instead, she pulled a folded invoice from her purse. The company listed at the top, Harbor Project Services, had billed our firm for work on a hospital renovation. Beneath its address was Madison’s name.
“I didn’t do the work,” she said. “He told me he was paying me back for money I lent him. Last week, the client called to ask why I had approved an inspection I’ve never seen.”
The hospital contract required a second review before certain payments cleared. I performed that review. Daniel had apparently decided he could replace it with a copied signature.
I reached for the invoice. He grabbed Madison’s wrist.
“Let go,” I said.
A car horn sounded outside. My attorney, Rachel, had agreed to pick me up after I sent her the client’s email. Daniel released Madison and stepped back, smiling as though Rachel could see through the wall.
I walked out with my overnight bag. Madison followed. Daniel called after us, “If you contact the client, every employee loses a paycheck.”
In Rachel’s car, Madison showed me three more invoices. Harbor was registered under her name, but she said Daniel had handled its accounts. She had kept the emails in which he told her what to sign. I sent copies to Rachel and asked her to preserve them. I also called the client’s contract manager and stated one fact I could verify: the authorization bearing my name was not mine.
By morning, the client had paused the disputed payment and requested an independent review. Daniel sent a companywide email saying I had abandoned my duties. Minutes later, the bank called me. As a forty percent owner and guarantor on the company’s credit line, I was still listed on the account.
The bank officer asked whether I had authorized a change to my personal guarantee the previous Tuesday.
I had not.
Rachel requested the document. When it arrived, we saw a different signature copied beneath my name. This time Daniel had used an old signature from our mortgage paperwork.
But the attached statement held the real shock: the request had not been made to remove me from the debt. It asked the bank to increase the credit line by $900,000, with our home listed as additional collateral.
Our home. The one Daniel had told me he owned outright.
“Is the house even in his name?” I asked.
Rachel studied the attachment. “We’ll check the title. First, tell the bank in writing that you did not sign this.”
From her office, I sent the bank a signed dispute and copies of both documents. Rachel asked for the original files and access records, then called the title company. I sat across from Madison while she scrolled through months of emails, searching for the first time Daniel had mentioned Harbor.
She found it in February: Set this up under your name. Claire won’t approve another advance until the inspection is complete.
Madison held out her phone with shaking hands. “I thought he meant you were being difficult.”
“Did you know the inspection wasn’t complete?”
“No. I never even visited the hospital.”
That answer mattered. Madison had signed paperwork for Harbor and accepted transfers from it. Rachel told her to get her own lawyer before speaking further to investigators. Madison made the call from the hallway.
The title report arrived first. Daniel and I both owned the house. He had told Madison it belonged to him alone. Rachel also found a recorded deed of trust securing our original mortgage, but nothing showing that I had agreed to pledge the house for more debt. The bank confirmed it had not approved the increase. The request was still under review because one of its employees had flagged an inconsistency.
Relief came in a thin, temporary wave. Our home had not been pledged to the new loan. Daniel had tried to make it happen.
That afternoon, the hospital’s contract manager called with another problem. The $480,000 invoice was only one of five submitted through Harbor. Two earlier invoices had been paid. The hospital wanted records showing who ordered the work, who inspected it, and where the money had gone.
Daniel had removed my access the night before. I gave the manager Rachel’s number and asked our outside accountant to preserve his monthly reports.
By evening, Daniel was on my voicemail. First he called me cruel. Then he offered to restore my salary. Finally he said, “Sign a statement saying you approved Harbor, or the bank takes the house.”
Rachel listened beside me. “Save that,” she said.
I did. I saved the next message too, in which he insisted the money was already gone.
I worried about our employees. Rachel helped me direct the finance manager to preserve payroll records and contact the bank about the next payroll draw. I could not promise every paycheck would clear.
Three days later, the accountant’s reports showed transfers from Harbor into an account Daniel controlled. Some covered legitimate company expenses. Others paid his personal credit cards and the deposit on the apartment he had promised Madison. The reports did not prove whether every billed service was false. They gave the hospital and the bank a trail they could follow.
Madison’s attorney arranged for her to provide her emails and bank records separately. She told investigators that Daniel had asked her to sign the first Harbor invoice without explaining the hospital project. When she challenged the later invoices, he had offered to move her into our house so she would be “safe” until the baby came. She had thought he meant safe from debt collectors. Now she believed he meant close enough to watch.
I could not know everything she had known when she first agreed. I could see why she was frightened when she asked me not to leave her there.
The independent review took weeks. The hospital suspended new work under our contract and demanded repayment for services it could not verify. Our bank froze further credit advances while it examined the forged request. Daniel told anyone who would listen that I had destroyed the business to punish him for Madison.
Then our finance manager found a folder he had missed when he locked me out. It contained draft responses to the hospital, each blaming me for approving the Harbor payments. One draft was dated the morning before Madison moved into our home. Daniel had planned his explanation before I ever refused to sign.
That was the last piece Rachel needed to file a civil claim on my behalf. I sought access to company records as an owner, protection from liability for signatures I had not made, and an accounting of the Harbor payments. I also filed for divorce. Through his attorney, Daniel agreed to stop speaking for me or using my signature while the cases proceeded. He resigned from day-to-day management after another lender demanded an independent manager as a condition of keeping the ordinary payroll facility open.
It was not a clean rescue. We lost the hospital contract. The company shrank, and several employees found other jobs. An independent manager sold equipment we no longer needed and negotiated a repayment schedule with the hospital. The accountant corrected the records. Months later, I sold my shares to a local competitor after Rachel reviewed the terms. The sale paid off my part of the valid business debt. It did not erase what Daniel had done, or give us back the jobs that were lost.
A prosecutor later charged Daniel over the forged bank request and the false billing. He pleaded guilty to two charges as part of an agreement and was ordered to pay restitution. Madison provided evidence through her attorney. She moved into her sister’s apartment before her daughter was born. I saw her once at a courthouse, holding the baby against her shoulder. We nodded to each other and kept walking.
When the divorce was final, I kept the house by refinancing the existing mortgage in my name and buying out Daniel’s share. For a while, every room reminded me of the night he demanded my keys. Then I changed the locks, painted the kitchen, and invited two former coworkers over for dinner.
One of them asked whether I missed running the company. I thought about the reports, the frantic calls, and all the nights I had told myself that keeping everything together meant protecting everyone.
“I miss the people,” I said. “I don’t miss covering for him.”
Daniel had expected me to beg for my job and sign whatever he put in front of me. Instead, I handed over the keys, kept the evidence, and let the people who were owed answers ask their questions. His empire fell apart under the weight of decisions he had made long before I walked out.