The cashier at the Target in Raleigh tried my card twice before lowering her voice and saying, “I’m sorry, ma’am, it’s still being declined.” My eight-month-old son, Noah, was fussing in the cart beside a box of diapers and formula while I stared at a credit card that had worked the day before.
I had another debit card buried in my wallet, but the deliberate humiliation hit me before the practical solution did. Until that moment, I had never imagined Ethan would use access to groceries and baby supplies to prove a point.
I stepped away from the register and called my husband, Ethan, expecting him to mention a fraud alert or banking mistake. Instead, he said, “I turned your card off this morning. You keep saying you want to be treated like an equal, so figure it out yourself.”
For a second, I thought I had misunderstood him. “Ethan, I’m buying diapers for your son,” I said, but I heard his mother, Diane, laughing beside him before she called out, “Tell the useless leech to get a job if she wants spending money.”
Ethan did not correct her; he simply said, “Mom’s right,” and hung up. I stood beside customer service with my face burning, because I finally understood that this had not been an accident or a bad joke.
What Ethan had forgotten was that I had spent nine years building a healthcare software consultancy before we married, then sold my share three years earlier. Most of the proceeds—just over $1.6 million after taxes—sat in investment accounts in my name, while scheduled transfers had quietly covered nearly seventy percent of our household expenses since Noah was born.
I had never used that fact as a weapon because marriage, to me, was not an accounting competition. Ethan handled the joint checking account and credit cards while I handled our savings and investments, and when I paused consulting after Noah’s birth, I trusted that the arrangement still made us partners.
I called my private banker, Marcus Hale, who knew the safeguard we had set up when I stopped working full-time. “Marcus,” I said, “release the funds, move this quarter’s distribution into my individual account, and stop every automatic transfer into the joint account.”
There was a short silence before he asked, “Are you sure you want all scheduled household sweeps suspended?” I looked at Noah rubbing his tired eyes and answered, “Yes. Effective today.”
Twenty minutes later, I paid for the diapers with my own debit card. Ethan and Diane had no idea that the account they believed proved I was dependent on him had just lost the money keeping their entire version of our life afloat.
Ethan did not notice anything that evening because the joint account still had enough cash to look normal, and he came home acting as though our phone call had never happened. He kissed Noah, ignored me, and spent dinner telling Diane on speakerphone that I would “calm down once I realized how expensive independence was.”
I said nothing, but after Noah fell asleep, I downloaded eighteen months of statements from every joint account. By midnight, I had found recurring transfers I did not recognize: $2,400 a month to Diane, payments on a Ford F-250 registered to Ethan’s landscaping company, and several large credit-card charges that had been categorized as “business expenses” even though they had come from our household account.
The next morning, I called our accountant, Rachel Kim, and asked her to review the records without drawing conclusions until she had traced the money. By that afternoon, she confirmed that Ethan had been using the household account as a bridge whenever his company was short on payroll, then replacing only part of what he took when clients paid him.
“He may have intended to put it back,” Rachel said carefully, “but he never asked you, and the pattern is getting larger.” She also pointed out that the monthly payments to Diane had totaled more than $28,000 in a year, even though Ethan had repeatedly told me we could not afford part-time childcare because I was “not bringing in income.”
That sentence changed something in me more than the insult at Target had. I had spent months waking every three hours with Noah, cooking, handling appointments, and postponing consulting work because Ethan insisted daycare would strain our budget, while he was quietly sending his mother almost the exact amount a reliable nanny would have cost.
At 10:15 the following morning, the automatic transfer that normally replenished our joint account did not arrive. Ethan texted me before lunch: “Did something happen with the bank?” and when I did not answer immediately, he sent another message saying his business insurance payment was due and he needed the transfer corrected.
I replied, “The household transfers from my individual investments are suspended. We can discuss finances tonight with full statements in front of us.”
He called within seconds. “You can’t just shut off our money because you’re angry,” he said, his voice already rising.
“Our money?” I asked. “Yesterday you shut off my card while I was buying diapers.”
“That was different,” he snapped. “I was trying to teach you some responsibility.”
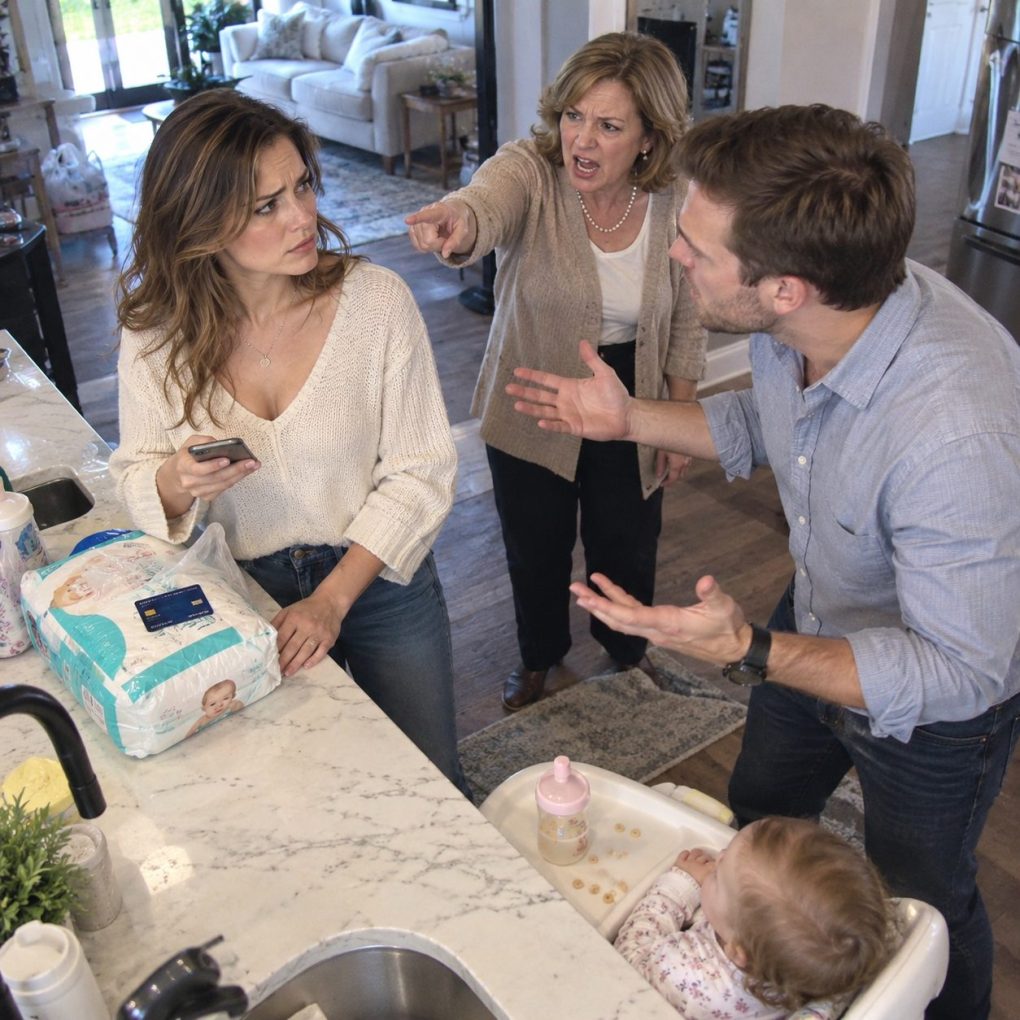
When he got home, Diane was with him, which told me he had invited an audience rather than a conversation. She walked into my kitchen, dropped her purse on the counter, and said, “So this is your little revenge stunt?”
I placed printed statements between us and pointed to the transfers bearing her name. “No, Diane. This is me finding out why my husband claimed we couldn’t afford childcare while sending you $2,400 every month.”
Her expression changed before Ethan’s did. He reached for the papers, but I pulled them back and said, “Copies are with my accountant, and tomorrow they’re going to an attorney.”
Ethan’s voice softened instantly. “Claire, don’t make this bigger than it is.”
“I didn’t,” I said. “You did when you decided financial control was something you could use to humiliate me.”
That night, Ethan slept in the guest room, and Diane left without another insult. For the first time since Noah was born, I did not feel financially trapped; I felt angry enough to start counting everything I had ignored.
The attorney I met the next morning, Natalie Brooks, did not promise me a dramatic courtroom victory, which was exactly why I trusted her. She reviewed the records showing that my investment portfolio came from the sale of my company before our wedding, then told me we needed to separate emotion from evidence.
“You can stop voluntary transfers from your separate account,” she said. “But do not move joint money, hide assets, or turn this into punishment. Document everything and let the legal process handle what belongs to both of you.”
That afternoon, Marcus confirmed that the quarterly distribution—$84,600—had settled into my individual checking account and every automatic sweep to the joint account had been canceled. I used part of it for Natalie’s retainer, arranged part-time childcare, and rented a modest townhouse near Noah’s pediatrician, while leaving enough in the joint account to cover ordinary bills until a temporary agreement was signed.
Ethan reacted less like a man losing his wife than a man discovering his budget had been fictional. Within a week, he admitted my monthly transfers had been covering the gap between what his landscaping company earned and what he spent, so he had to cancel an equipment purchase, reduce his own salary, and tell Diane that her $2,400 monthly payments were over.
Diane called me exactly once. “After everything this family has done for you, you’re going to leave Ethan struggling?”
I kept my voice steady. “The money supporting Ethan, your payments, most of the mortgage, and the groceries came from the person you called a useless leech. I’m not asking you to apologize, Diane, but I am asking you never to speak to me that way again.”
She hung up, and I blocked her number until we could establish boundaries concerning Noah. Ethan cycled through anger, apologies, promises of counseling, and accusations that I had “planned this all along,” but the bank records showed years of regular contributions from me and months of undisclosed withdrawals by him.
We eventually entered mediation instead of turning the divorce into a public war. The jointly titled house was sold, the remaining equity was divided under our settlement, Ethan kept his company and its debts, and I kept the investment accounts our financial professionals could trace to my premarital business sale.
The childcare arrangement changed my daily life almost immediately. I returned to consulting three afternoons a week, not because Diane had told me to “get a job,” but because I missed the part of myself that solved difficult problems and spoke to adults about something other than feeding schedules.
The work also gave me a routine that belonged to me again, instead of a life arranged around Ethan’s moods and emergencies. For the first time in months, I could look at my calendar and see something beyond feedings, bills, and arguments waiting for me.
Ethan also became more responsible once there was no invisible transfer rescuing him every month. Our custody agreement gave him consistent parenting time, and although I never trusted him with my finances again, I wanted Noah to have a father who learned that caring for a child meant more than posting smiling photos while someone else quietly carried the cost.
Six months after the Target incident, I was standing in the same store with Noah when my phone buzzed with notice that our divorce had been entered. I looked at the diapers in my cart and realized the most important thing I had released that day had not been $84,600.
It had been the belief that dependence was the same thing as partnership.
At checkout, the cashier smiled and said, “You’re all set.”
This time, so was I.