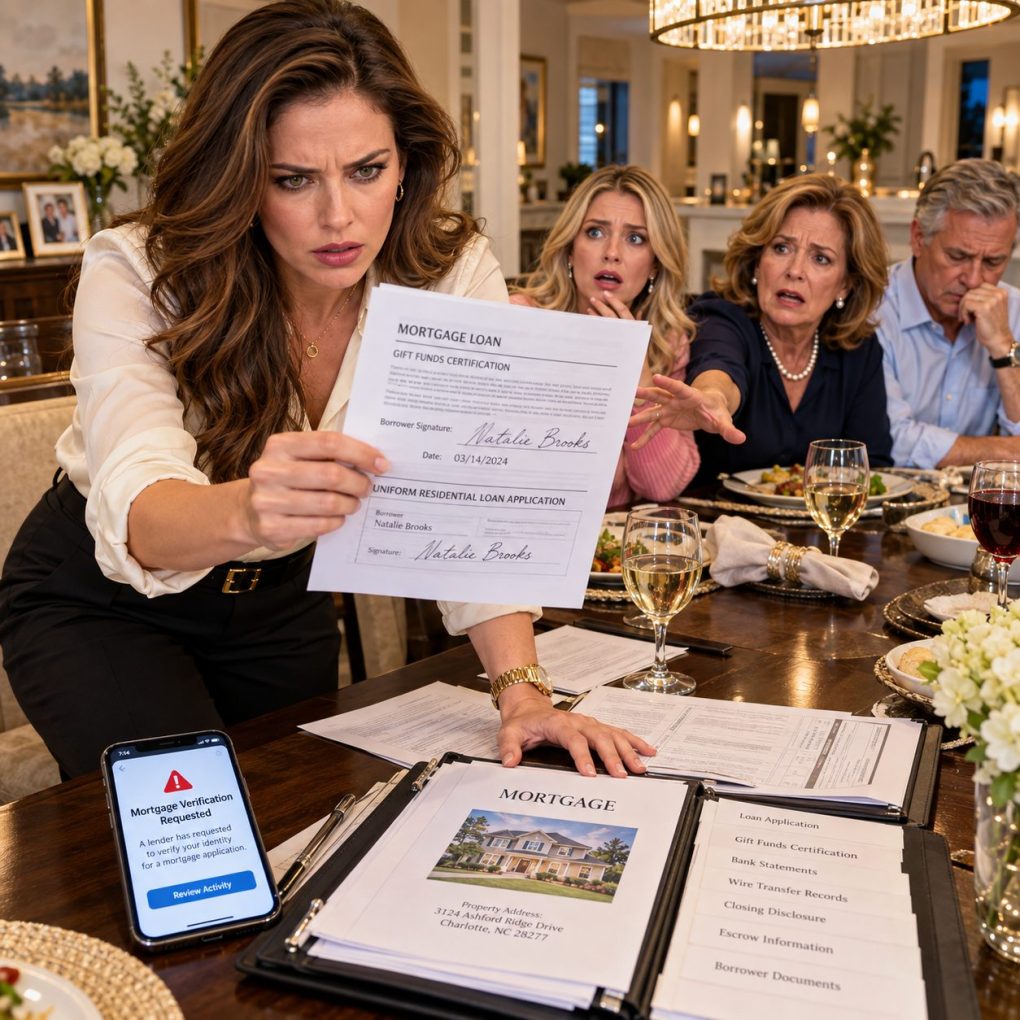
My father pushed a thick folder across the dining table and said, “Before you get upset, just understand we already did it.”
I stared at him. “Did what?”
My mother folded her hands like she was delivering wonderful news.
“We spent eighty-five percent of your savings to help Lauren buy her house.”
For a second, I honestly thought I had misheard her.
My younger sister leaned back in her chair, smiling. “You should see your face.”
I grabbed my phone.
The old savings account I had opened as a teenager still had my mother listed as a joint owner. I had meant to remove her years ago, but because she had never touched a dollar, it stayed near the bottom of my financial to-do list.
That mistake had just become very expensive.
There it was.
$112,625 transferred that morning to Harbor Title & Escrow.
My balance was barely $20,000.
Lauren laughed.
“You don’t have a single penny left.”
And that was when I burst out laughing.
Not nervous laughter.
Not disbelief.
I laughed so hard I had to put my phone down.
The three of them stared at me.
Mom’s confidence cracked first. “What’s funny?”
I wiped my eyes.
“You actually thought that was all my money?”
Lauren’s smile disappeared.
I’m thirty-six. I work as a senior procurement director for a medical-device company in Charlotte, North Carolina. I had spent more than a decade building my finances carefully.
The account my mother could access wasn’t my retirement account.
It wasn’t my brokerage account.
It wasn’t my emergency fund.
It wasn’t even the account where my paycheck went.
It was an old legacy account I had kept because my grandmother helped me open it when I was sixteen.
There was substantial money in it, yes.
But it represented less than a quarter of my liquid assets.
Lauren looked at Mom.
Mom looked at Dad.
Dad’s face tightened.
Then he said the sentence that changed everything.
“It doesn’t matter. The money was sitting there, and your sister needed it.”
I stopped laughing.
“You took more than a hundred thousand dollars from me without asking.”
“We didn’t take it,” Mom snapped. “We used it for family.”
Lauren crossed her arms. “I’m closing Monday. It’s already done.”
Something about that sentence bothered me.
“Closing?”
She nodded.
“On the house in Matthews?”
“Yes.”
I looked at the transfer again.
A mortgage lender would require documentation for a six-figure gift used toward a down payment.
They would want proof of source.
They would want a gift letter.
And most importantly, they would want confirmation that the money wasn’t a loan.
I looked at my mother.
“What exactly did you sign?”
Nobody answered.
My father suddenly became very interested in his water glass.
I reached for the folder he had pushed toward me.
Mom grabbed it first.
That was all the confirmation I needed.
“Give me the folder.”
“It’s nothing.”
“Then give it to me.”
Lauren stood up.
“Oh my God, Natalie. Stop acting like someone robbed you. You make plenty of money.”
That sentence made my stomach turn.
I reached across the table and pulled the folder from Mom’s hands.
Inside was Lauren’s purchase agreement, lender paperwork, an escrow receipt and, near the bottom, a document titled GIFT FUNDS CERTIFICATION.
Donor: Natalie Brooks.
Recipient: Lauren Brooks.
Amount: $112,625.
I had never seen it before.
Then I saw the signature.
My signature.
Or something close enough to fool someone who didn’t know me.
Underneath it were my date of birth, my address and the last four digits of my Social Security number.
My laughter vanished.
I looked up slowly.
“Which one of you forged my name?”
Nobody spoke.
Then my phone buzzed.
It was an email from the mortgage company.
Thank you, Ms. Brooks. Your financial contribution has been verified.
I opened the attachment.
And what I saw on the second page made my hands start shaking.
Because they hadn’t only taken my money.
Someone had tried to make me legally responsible for Lauren’s mortgage.
I looked at my sister.
Her face had gone completely white.
Someone in that room knew exactly what had been done, and suddenly the missing money was no longer the worst part. The documents in my hands could destroy Lauren’s house purchase, expose whoever forged my identity, and tear apart far more than one family dinner.
The second page wasn’t a gift form.
It was a borrower authorization.
My name was listed as a proposed non-occupant co-borrower.
My income was there.
My employer was there.
Even my estimated annual bonus was there.
I looked at Lauren.
“Where did you get this information?”
She didn’t answer.
Mom did.
“We knew approximately what you made.”
“You knew my Social Security number approximately too?”
Dad stood up. “Natalie, calm down.”
“No.”
That one word came out so sharply that everyone went silent.
I called the lender from the number printed on the paperwork. Their normal office was closed, but the fraud line connected me to an after-hours representative.
I explained that I had not signed the gift certification, had not authorized anyone to use my personal information and had never agreed to guarantee or co-sign a mortgage.
The woman’s tone changed immediately.
She told me not to sign anything and not to contact anyone pretending to be the lender. She flagged the file for compliance review.
Then I called the title company.
The escrow officer couldn’t reverse anything that night, but she placed an internal hold on Monday’s closing pending verification.
Lauren exploded.
“You’re ruining my house!”
I stared at her.
“I’m ruining your house?”
Mom started crying.
Dad accused me of being vindictive.
Lauren paced around the dining room insisting they were going to lose their earnest money, their rate lock and maybe the property.
Then I asked the question none of them wanted to answer.
“Who forged my signature?”
Mom finally whispered, “I signed the gift letter.”
Lauren immediately said, “Mom!”
That reaction told me there was more.
I turned to her.
“What did you do?”
Nothing.
Dad closed his eyes.
“Tell her.”
Lauren’s mouth opened, but no words came out.
Dad looked exhausted.
“The bank denied Lauren twice,” he said. “Her debt-to-income ratio was too high.”
Lauren’s fiancé, Ethan, had recently changed jobs. Lauren still carried student loans, two car payments and almost $30,000 in credit-card debt.
They couldn’t qualify for the house they wanted.
So Lauren had suggested adding me.
“I never agreed to that.”
Dad nodded.
“I know.”
The room went dead quiet.
I felt cold.
Lauren finally admitted she had photographed my driver’s license at Christmas when I left my wallet on Mom’s kitchen counter.
Then she used information from old family tax records to complete preliminary mortgage documents.
Mom knew.
Dad found out later.
Neither stopped it.
Lauren looked at me with tears in her eyes.
“I was going to remove you after closing.”
I almost laughed again.
“That isn’t how mortgages work.”
Then my phone buzzed.
A credit-monitoring alert.
Hard inquiry.
Six weeks earlier.
A lender I didn’t recognize.
Then another.
And another.
They hadn’t tried this once.
They had been shopping my identity around to multiple mortgage companies.
I turned the screen toward Lauren.
“How many applications did you submit?”
She started crying.
Mom covered her face.
Dad whispered, “Lauren.”
Finally she answered.
“Three.”
My heart was pounding when another message arrived from the lender’s compliance officer.
She had found something else.
The mortgage application included a digitally signed occupancy and liability certification using my name.
And according to their records, the electronic verification had come from an email address I had never seen before.
The address contained my name.
But the recovery phone number ended in four digits I recognized immediately.
They belonged to my mother.
I stared at those four digits until the room around me seemed to disappear.
Mom lowered her hands.
She knew exactly what I had seen.
“You made an email account in my name?”
“It was temporary.”
I actually felt something inside me go still.
Until that moment, part of me had been trying to separate what happened into pieces.
Mom took money because she believed Lauren deserved it.
Lauren used my information because she was desperate for a mortgage.
Dad stayed quiet because confrontation made him uncomfortable.
Ugly choices.
Selfish choices.
But perhaps choices made in panic.
The fake email destroyed that interpretation.
This had required planning.
Someone created an account pretending to be me.
Someone intercepted verification messages.
Someone answered questions as me.
Someone signed documents as me.
And then they had invited me to dinner to announce my financial destruction like they were presenting me with a completed family decision.
I stood up.
“I’m leaving.”
Dad moved toward me.
“Natalie, don’t make any decisions tonight.”
“I’m thirty-six years old. Apparently I’m the only person here who should have been making decisions about my money.”
Mom followed me toward the front door.
“We can fix this inside the family.”
I turned around.
“No. You already tried fixing things inside the family. That’s how my name ended up on a mortgage application I never signed.”
Lauren was crying now.
I didn’t care.
Not yet.
I drove home, locked my door and sat at my kitchen island with my laptop.
For the next three hours, I did everything I should have done years earlier.
I froze my credit with all three major credit bureaus.
I changed passwords.
I replaced security questions my parents might know.
I reviewed every account.
I downloaded statements from the joint savings account.
Then I filed an identity-theft report and made a police report documenting the forged mortgage paperwork.
That was the moment my phone began exploding.
Mom called eleven times.
Dad called six.
Lauren sent twenty-three messages.
I read none of them.
At 7:42 the next morning, Ethan called.
Lauren’s fiancé.
I almost ignored him.
Then he texted:
I didn’t know they used your identity. Please answer.
I called.
Ethan sounded like he hadn’t slept.
He told me Lauren had said the down-payment money was an early family gift.
She told him I had volunteered to help because my income was stronger and I wanted them to get the house.
He believed her because my parents backed up the story.
“Did you sign anything with my name on it?” I asked.
“No.”
“Did you know they created an email account pretending to be me?”
“No.”
There was silence.
Then he said something I hadn’t expected.
“I’m not going to closing.”
I leaned back in my chair.
He continued.
“I asked Lauren to show me everything last night. She wouldn’t. Then your dad finally told me enough that I realized I don’t know what’s true anymore.”
By Monday morning, there was no closing.
The lender suspended the application.
The title company froze the escrowed funds while its legal department reviewed the source and authorization.
Lauren and Ethan lost the house.
They also lost their relationship.
Ethan moved out of their apartment two weeks later.
Lauren blamed me for that too.
At least initially.
The financial part became complicated because Mom had still been legally listed as a joint owner of the old savings account.
The bank explained that her ability to initiate a withdrawal did not automatically resolve who ultimately owned the money or whether the transfer had been made for a lawful purpose.
That became a matter for lawyers.
Fortunately, because the house transaction had not closed and the title company had been notified before disbursement, most of the $112,625 remained in escrow during the investigation.
Three weeks later, after documents were reviewed and the purchase collapsed, the funds were sent back to the originating account.
I moved every dollar that was unquestionably mine into a new account in my name alone as soon as the bank cleared it.
Then I closed the old account.
That account was what my family had never understood.
Yes, it contained real money.
Yes, losing $112,625 would have hurt.
But it was never my entire financial life.
Years earlier, after getting serious about money, I had separated everything.
My retirement funds were in employer-sponsored accounts.
My emergency fund was at another institution.
My investment accounts were individually titled.
I also owned a small rental townhouse I had purchased before prices surged.
By the night of that dinner, my parents had access to only one outdated account.
They mistook access for control.
And Lauren mistook a visible balance for my entire net worth.
That was why I laughed when she said I didn’t have a penny left.
She thought they had emptied my future.
In reality, they had exposed themselves.
The criminal investigation moved more slowly.
The police obtained copies of the lender documents.
The fake email account was documented.
So were the credit inquiries.
So was Lauren’s admission that she had photographed my identification.
My mother eventually admitted she had created the email address because lender verification messages kept going to me directly.
She said she was “helping the process.”
Her lawyer probably hated that phrase.
My father had not forged my name himself, but investigators learned he knew about the second and third applications and helped provide old tax paperwork that contained personal information.
The part that hurt most wasn’t learning that my sister had started it.
It was learning how many opportunities my parents had to stop it.
They could have told Lauren no.
They could have told me.
They could have returned the money.
Instead, every time the plan became worse, they helped it move forward.
About two months after the failed closing, Lauren appeared at my office parking garage.
I almost walked past her.
She looked terrible.
Not dramatic-movie terrible.
Just exhausted.
No makeup.
Hair pulled into a messy ponytail.
A woman who had finally stopped believing everyone else would absorb the consequences of her decisions.
“I’m not asking you to forgive me,” she said.
“Good.”
She swallowed.
“I need to tell you something else.”
I waited.
Lauren told me she had been drowning financially for almost two years.
The credit cards.
The student loans.
A personal loan she had hidden from Ethan.
Mom had repeatedly covered payments and told Lauren that eventually “Natalie will help.”
I felt my jaw tighten.
Lauren looked down.
“She talked about your money like it belonged to all of us.”
“And you believed her.”
“Yes.”
At least she didn’t make excuses.
Then she said something that surprised me.
“I think Mom did that because she needed me to believe I deserved whatever you had.”
I said nothing.
Lauren started crying.
“If I admitted you earned it, then I had to admit what I was doing was stealing.”
For the first time since everything happened, I felt something other than rage.
Not forgiveness.
Clarity.
Our parents had spent years creating a family mythology.
I was the responsible one.
Therefore, I would always recover.
Lauren was the struggling one.
Therefore, she always deserved rescue.
Every success I had became evidence that I could afford another sacrifice.
Every bad decision Lauren made became evidence that she needed more help.
That logic had worked until they finally crossed a line so obvious nobody could pretend it was generosity anymore.
Identity theft has a way of removing euphemisms.
Lauren asked if there was anything she could do.
I told her there was.
“Tell the truth.”
She did.
She cooperated with investigators.
She admitted her role in the mortgage applications.
She provided messages between herself and Mom discussing my financial information.
She also admitted she had known the $112,625 came from my account before the transfer.
The final legal outcome took almost a year.
Lauren entered a plea agreement involving identity-related fraud and forgery charges. She received probation, financial penalties, mandatory restitution obligations and a record that followed her into every apartment application and financial job background check afterward.
My mother faced separate consequences for her role in the forged documents and false email account.
My father avoided the most serious charges but still spent thousands on legal fees and agreed, through a civil settlement, to reimburse costs I had incurred protecting my identity and pursuing the case.
I didn’t celebrate any of it.
Watching your family face consequences is not the same thing as enjoying their pain.
But I also didn’t rescue them from those consequences.
That distinction changed my life.
For almost a year, I had no contact with my parents.
Lauren and I communicated only through short emails.
Then, slowly, she began doing something she had rarely done before.
She stopped asking me for things.
She found a cheaper apartment.
Sold her luxury SUV.
Took extra contract work.
Entered a debt-management program.
When our conversations eventually resumed, she didn’t begin with excuses.
She began with updates on what she had repaid.
Two years after that dinner, Lauren asked me to meet her for coffee.
She handed me an envelope.
Inside was a check.
Not a huge one.
But it represented the final portion of the legal restitution she personally owed me.
“I know this doesn’t undo it,” she said.
“No.”
“I know you may never trust me completely again.”
I looked at her.
“That depends on what you do next.”
She nodded.
And for once, she didn’t ask me to make her feel better.
My relationship with my parents never returned to what it had been.
I no longer gave them financial information.
They never saw account balances.
They didn’t know what I earned.
They didn’t know what I invested.
Money stopped being a family discussion.
That boundary cost me the illusion of the family I thought I had.
But it gave me something more useful.
Peace.
Sometimes I think back to Lauren sitting at that dining table, smiling as she told me I didn’t have a single penny left.
She believed money was power because our parents had always used money that way.
Reward one child.
Pressure another.
Call theft generosity.
Call favoritism family responsibility.
But the part none of them understood was that my security had never come from one savings balance.
It came from years of work, planning and learning not to depend on anyone who believed love gave them ownership over me.
They took eighty-five percent of one account.
For a few hours, they thought they had taken eighty-five percent of my life.
Instead, they gave me the clearest lesson I had ever received.
A person who believes they are entitled to your money usually believes they are entitled to your silence too.
I stopped giving them both.