My girlfriend admitted she had been using my credit card to pay her ex-boyfriend’s rent while we were standing in my kitchen on a Wednesday night. She said it like she was confessing to something inconvenient, not criminal. “I’ve been using your card to help Marcus with rent,” she said, watching my face carefully.
For a few seconds, I said nothing. Then I asked how long. She looked away and said, “A few months,” which turned out to mean six. I nodded and replied, “That’s kind of you.”
She visibly relaxed. That was the part I still remember most clearly. She thought my calm meant permission, forgiveness, or weakness. Instead, I walked into my home office, opened my banking app, and started checking every charge.
There were payments to a property management company in Phoenix that I had never authorized. The amounts varied between $1,450 and $1,700, always near the first of the month. There were also utility payments and one security deposit charge that made my stomach turn.
Her name was Tessa Morgan, and we had been together for almost three years. I had added her as an authorized user on one card for groceries and emergencies because she occasionally picked things up for our apartment. I had never given her permission to finance Marcus’s life.
When I asked why she had done it, she started crying. She said Marcus had lost work, was “going through a difficult season,” and had nowhere else to turn. Then she added, “You make enough. I thought you wouldn’t really notice.”
That sentence ended the conversation for me. I told her I needed some air and left the apartment. From my truck, I called the card issuer, froze the account, reported the unauthorized transactions, and documented every charge I could identify.
The next morning, I spoke with a fraud specialist and then with local police. I brought screenshots, statements, dates, messages, and the original authorization paperwork showing the limits of Tessa’s permitted use. The officer told me the investigation would depend on the evidence, but the amounts were significant enough to take seriously.
I did not warn her. I did not threaten her. I simply removed my belongings from the apartment while she was at work, left my key on the counter, and sent one message: “Do not use any of my accounts again.”
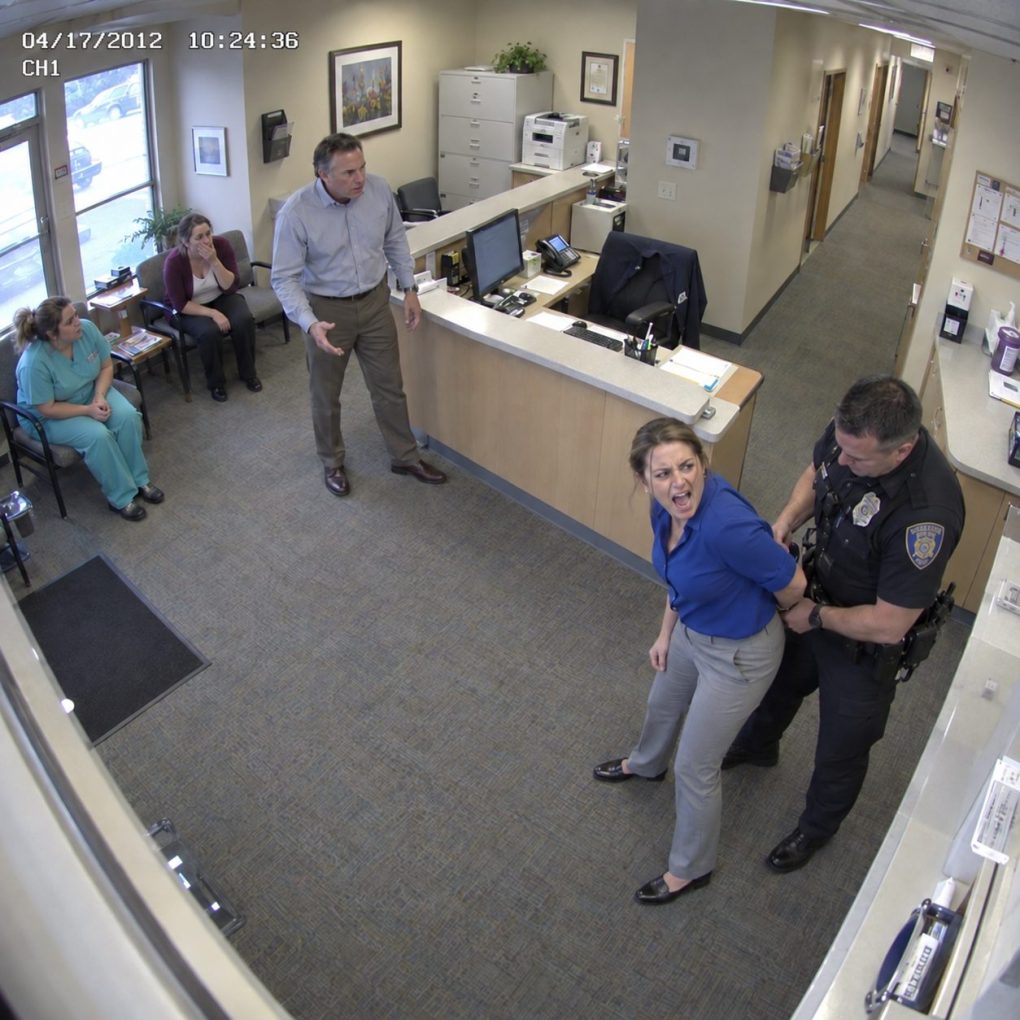
Two days later, I received a call from Tessa just after lunch. She was whispering so hard she could barely speak. “There are police officers at my office,” she said. I looked at the case number on my desk and answered, “Then I guess they found the charges.”
Tessa’s voice changed immediately. “You actually reported me?” she hissed. I reminded her that she had spent thousands of dollars that were not hers. She said, “I told you about it,” as though confession after the fact erased everything before it.
By then, the investigators had already contacted the property management company. Their payment records showed that my card had been used repeatedly for Marcus’s apartment. Several transactions were entered online from devices linked to Tessa’s email account.
The worst part was that she had not acted impulsively. She had created a pattern. Every month, she waited until after my statement cycle closed, then moved money through charges small enough that she assumed I would overlook them.
Marcus initially claimed he thought Tessa had permission. That was possible, and the police treated his involvement separately. But text messages later showed that he had asked her more than once whether I knew.
One message read, “He’s not checking, right?” Tessa had replied, “He never looks closely.” Another said, “Just use the same card again this month.” That conversation destroyed the last excuse she had tried to make.
Her employer did not fire her when officers came to the office, but everyone noticed. She worked as an office coordinator for a private medical practice, and the humiliation of being questioned in front of coworkers mattered deeply to her. She blamed me for that too.
That evening, her mother called me. She said I was “ruining Tessa’s future over money.” I asked whether she had seen the statements. She said no, but insisted couples were supposed to solve problems privately.
I told her there was nothing private about using my financial identity to support another man without permission. I also reminded her that Tessa had not borrowed from me. She had taken.
The disputed charges eventually totaled more than $9,000. Some were refunded during the bank’s investigation, while others remained part of the criminal case. My attorney advised me not to discuss specific evidence directly with Tessa anymore.
For the first time since we met, I blocked her number. It felt strange, almost cruel, but peaceful too. I realized how much time I had spent explaining basic boundaries to someone who understood them perfectly whenever they protected her.
The case moved more slowly than Tessa expected. There was no dramatic courtroom scene the following week, no instant conviction, and no television-style arrest. Instead, there were interviews, records requests, transaction logs, and months of paperwork.
Tessa hired an attorney. Through him, she admitted using the card but argued that she believed our relationship gave her broad financial permission. My lawyer responded with the signed cardholder agreement and messages where I had explicitly told her the card was for shared household expenses and emergencies.
Those messages mattered. So did the fact that Marcus’s rent was neither. The prosecutor eventually offered a resolution that required restitution, probation, and financial counseling rather than jail time, partly because Tessa had no prior criminal record.
I did not celebrate when I heard. By then, anger had mostly burned out. What remained was disappointment, because the situation had forced me to reconsider three years of memories through a different lens.
Tessa sent me a letter through her attorney after the case was resolved. She apologized, but the apology was tangled with explanations. She wrote that she had felt responsible for Marcus because they had been together since college and that she believed I could “absorb the cost.”
That phrase stayed with me. Absorb the cost. As if my trust, my money, and my dignity were just resources that could take the impact for everyone else.
Marcus moved out of his apartment a few months later. I heard through mutual acquaintances that he had gone to stay with his brother in Nevada. I felt nothing about it.
What surprised me was how much the experience changed my own habits. I started reviewing every account weekly, removed unused authorized users, froze old cards, and stopped confusing trust with the absence of boundaries.
Almost a year later, I ran into Tessa at a grocery store. She looked thinner, quieter, and older somehow. We stood near the freezer aisle for a few awkward seconds before she said, “I really thought you’d forgive me.”
I answered, “I did forgive you. That didn’t mean I had to stay.” Then I walked away with my cart and never looked back. Losing the money had been painful, but learning that forgiveness and access are not the same thing turned out to be worth far more.