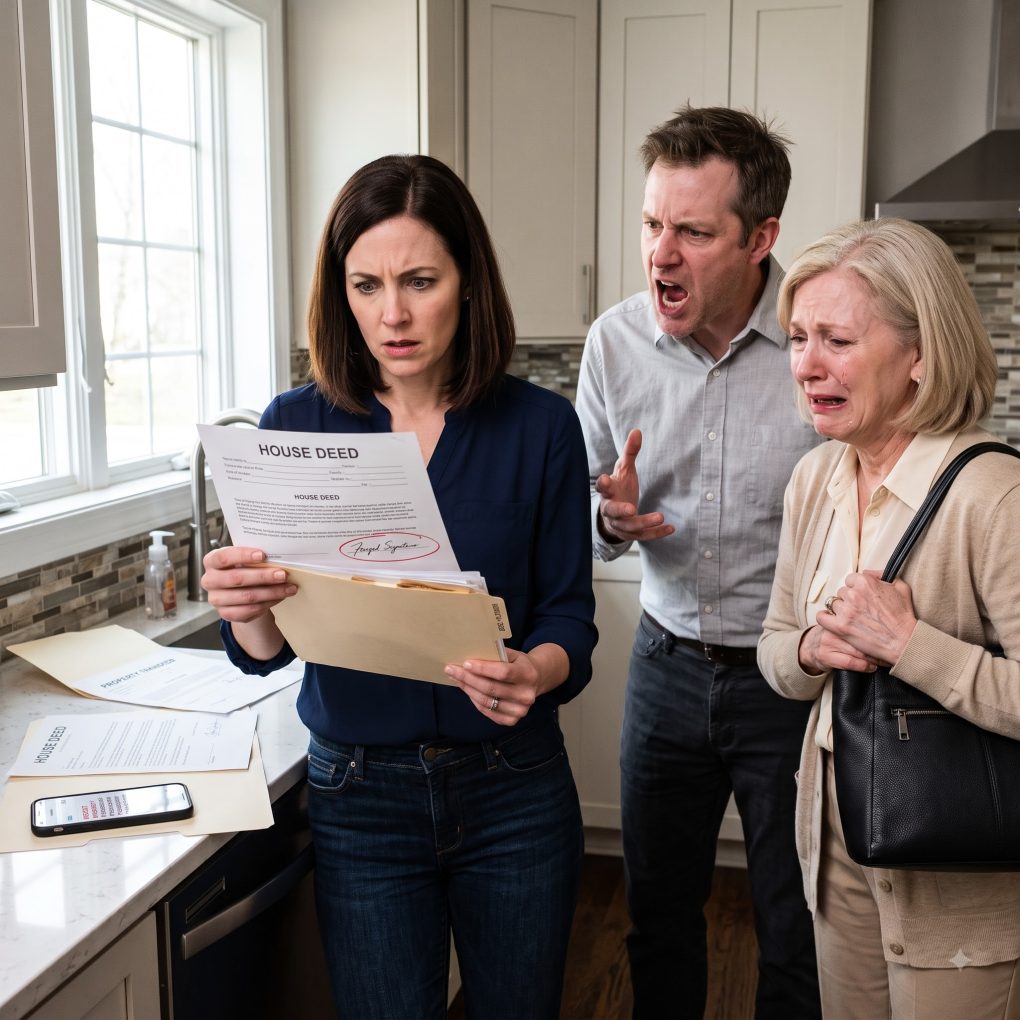
The document on my kitchen counter had my name on it—but I had never signed it.
I stared at the signature until my hands went cold.
For the past month, my mother-in-law, Diane, had been “staying for a bit.” That was how my husband, Mark, explained it. But within days, she was moving my furniture, replacing groceries, telling Mark what time to come home, and referring to the guest room as “my room.”
I kept telling myself it was temporary.
Then I found the paperwork.
It was a preliminary sales agreement for our house in Columbus, Ohio. The address was ours. The listed seller was Mark—and me. At the bottom was a signature that looked close enough to mine to fool a stranger.
But I knew exactly how I wrote my last name.
This one was fake.
I heard Diane laughing in the living room while Mark spoke quietly on the phone. I slid the papers back beneath a grocery circular and forced myself to breathe.
That night, I said nothing.
At dinner, Diane talked about “downsizing.” Mark barely looked at me.
I smiled.
At 11:40 p.m., after they went to bed, I photographed every page, emailed the files to myself, and checked the county property records. The deed told me something Mark apparently hoped I had forgotten.
The house had been purchased three years before our marriage.
By me.
My name alone was on the deed.
At 7:15 the next morning, I called the title company listed on the paperwork. Then an attorney. Then my bank.
By noon, Mark came storming through the front door with Diane behind him.
“What did you do?” he shouted.
Diane’s face was white. Her phone shook in her hand.
Then she shoved it toward me.
On the screen was an email from the title company.
The sale had been frozen.
But that wasn’t the part that made my stomach drop.
At the bottom was one sentence about the forged signature—and a name I recognized.
I thought freezing the sale would end it. Instead, one phone call exposed a second set of documents—and showed me that my husband and his mother had planned far more than a quiet house sale.
The name was “Elaine Porter.” I knew Elaine. She was Diane’s longtime friend—and a commissioned notary. Mark snatched the phone from Diane. “You had no right to interfere.” “With the sale of my house?” His jaw tightened. Diane stepped between us. “Don’t be dramatic. We were trying to solve a family problem.” I asked what problem required forging my signature. Neither answered.
Then my attorney, Rachel Kim, called. I put her on speaker. Rachel said the title company had stopped the transaction after receiving my fraud notice. But during its review, it found something worse: a notarized authorization claiming I had given Mark power to sign property documents for me. I had never signed that either.
Rachel told me not to touch anything else and not to let anyone remove papers from the house. Diane lunged toward the hallway. I moved first and stood in front of the small desk where Mark kept our household files. “Move,” she snapped. “No.” Mark’s face changed. The anger disappeared. For one second, he looked scared.
That was when I realized the forged sale contract wasn’t the beginning. It was evidence of something already in motion. Rachel asked whether anyone had access to copies of my driver’s license, Social Security card, or old signatures. I looked at Mark. Six months earlier, he had insisted we put all our important documents in one fireproof box “in case of an emergency.” The box was in his office.
I opened the closet. It was gone. Mark backed toward the garage door. I told him not to leave with anything that belonged to me. He laughed too quickly. “You think I’m stealing from you?”
Then Diane’s purse slipped from her shoulder and hit the floor. A manila envelope slid out. Across the front, in black marker, were the words: PROPERTY TRANSFER. Diane grabbed for it. I got there first. Inside were copies of my deed, my driver’s license, and three pages covered with signatures that looked like mine.
Rachel went silent on speaker. Then she said, “Do not give that envelope back.” Mark suddenly shouted, “Mom, stop talking!” Diane froze. I looked at her. “What were you going to do after the house sold?” Her eyes filled—not with guilt, but panic. She whispered, “Mark told me you already knew.”
I turned to my husband. And Rachel said, very carefully, “There’s one more document the title company just sent me. It isn’t about the house.”
Rachel emailed the document while we were still standing in the kitchen. It was an application for a $180,000 home-equity line of credit. My house was listed as collateral. My forged signature appeared on the final page. For several seconds, nobody spoke. Then Mark said, “It was never supposed to get this far.” That sentence told me everything.
Rachel told me to photograph the envelope, secure the documents, and make a police report. Mark started pacing. Diane sank into a chair. Slowly, the truth came out. Eight months earlier, Mark had lost nearly $70,000 in an online investment scheme. He hid it from me, borrowed more money trying to recover the loss, and eventually fell behind on payments. Diane offered to help, but she did not have enough cash. So they built a plan around the one asset they thought could save him: my house.
Mark claimed he first intended to take out a home-equity loan. He found old copies of my identification and practiced my signature until it looked convincing. Diane admitted she had asked her friend Elaine how property documents were usually notarized. She insisted Elaine did not know about the fraud. I wrote down exactly what Diane said and called the non-emergency police line. Mark immediately grabbed his keys. I told him he could leave, but the missing fireproof box and anything containing my records stayed. He stopped.
Two officers arrived about twenty minutes later. I showed them the sale agreement, the authorization, the loan application, and the envelope from Diane’s purse. Mark called it a “marital misunderstanding.” I showed them the deed proving I had bought the house three years before our marriage. The officers took a report and warned everyone not to destroy or remove possible evidence. After they left, Mark went upstairs and came down carrying the missing fireproof box. He refused to open it.
Then Diane said, “Just give it to her.” Mark shouted at her to stay out of it. Their alliance cracked instantly. Diane began crying and claimed Mark had promised the house would be sold legally after I agreed. Mark called her a liar. Then Diane looked at him and said, “Tell her about Nevada.” Mark froze. Diane told me he had been communicating with a real-estate investor in Las Vegas who handled fast cash purchases. According to her, Mark planned to sell my house below market value, use the money to clear his debts, and put the rest toward a condo in Nevada—for himself.
I asked Mark how long he had planned to leave me. He stared at the floor. “Three months.” That answer hurt more than his shouting. By evening, he packed clothes and left for a hotel. Diane remained one more night while the evidence was being sorted out. I changed the locks on my office, moved my important papers to a bank safe-deposit box, changed every password, and froze my credit.
The next morning brought two pieces of good news. The lender’s fraud department confirmed the $180,000 credit line had never funded. The title company formally canceled the proposed house sale. Then Rachel found the detail that unraveled the rest: the authorization carried Elaine Porter’s notary seal and commission number, but Elaine’s commission had expired four months before the document was supposedly signed.
Rachel contacted Elaine. Elaine denied notarizing anything and said her old stamp had disappeared during a move. Then she asked, “Was Diane involved?” Diane heard the question on speaker and broke down. She admitted that while helping Elaine unpack months earlier, she had taken the expired stamp. Mark had told her they only needed it “to make the paperwork look official” until I signed real documents later. I stared at her and asked, “You stole a notary stamp and used it on fake papers?” She whispered, “Yes.”
That admission changed everything. Over the next two weeks, detectives collected the loan application, title-company records, emails with the Nevada investor, and messages between Mark and Diane. The messages erased any possibility of confusion. Mark had written, “Once it closes, she can’t undo it.” Diane had replied, “Make sure the signature matches.” I filed for divorce. Rachel helped me notify the credit bureaus and every institution that had received the forged documents. The house remained mine. No loan funded. No sale went through. Mark’s debts remained his.
Diane moved out three days after a second police interview. At the door, she tried to apologize and said she had only been “protecting her son.” I told her helping someone steal another person’s home was not protection. She had no answer. The criminal case moved more slowly than the divorce, but investigators eventually cleared Elaine after confirming she had not participated. Mark later accepted responsibility for submitting forged financial documents under a plea agreement that included restitution for investigation-related costs, probation, and fraud-related restrictions. Diane faced a separate case connected to the false notarization and unauthorized use of the expired seal.
The divorce ended quietly. Through his attorney, Mark asked whether I would sell the house anyway and split the proceeds. I refused. Not because the house was perfect, and not because I wanted revenge. It had been mine before Mark entered my life, and he had nearly convinced himself that marriage gave him the right to take it.
The first night after everything was finalized, I sat at the same kitchen table where I had found the forged contract. Diane’s decorations were gone. The furniture was back where I wanted it. In front of me was one folder containing the deed, fraud reports, canceled loan application, and final divorce papers. For months, I had thought the frightening part was the forged signature. It wasn’t. The frightening part was how calmly two people I trusted had built a plan around my silence. They expected me to argue, doubt myself, or keep it inside the family. Instead, I documented everything, called professionals, and stopped the sale before their lie became a legal transaction.
The next morning, I made coffee in my kitchen. My kitchen. My house. My name on the deed. And for the first time in months, nobody was telling me where anything belonged.