She thought she had successfully planned my move to a nursing home. But she had no idea I was planning a much bigger surprise for her apartment.
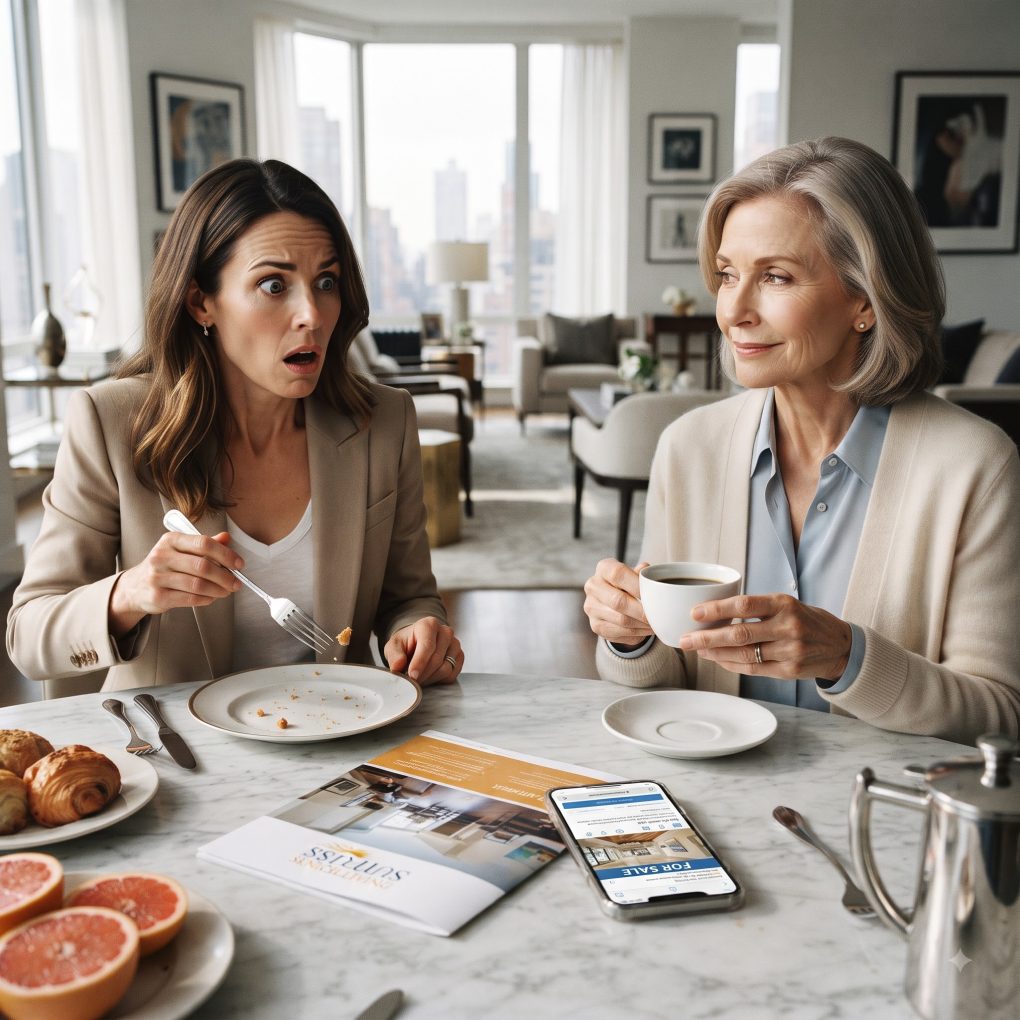
“My daughter pushed an assisted-living brochure across the brunch table.”
“We toured a beautiful place for you, Mom,” Emily said brightly. “You’d have your own room, meals, activities, everything.”
I took one slow sip of coffee.
Then I smiled.
“Wonderful. I already toured your apartment.”
Emily’s smile disappeared.
“I’m sorry?”
“It’s listed for sale.”
Her fork slipped from her hand and clattered against the plate.
“What did you just say?”
“I said your apartment is listed for sale.”
My son-in-law Mark stopped chewing.
Emily stared at me as if I had suddenly become a stranger.
“That’s impossible. We own that apartment.”
“No,” I said calmly. “The bank does. And I happen to know the mortgage is six months behind.”
Mark went pale.
Emily looked at him.
“Mark?”
He wouldn’t meet her eyes.
I placed my coffee cup down.
“I also know the property taxes haven’t been paid.”
Emily’s voice dropped.
“Mom, how do you know this?”
“Because my name is still on the original loan documents.”
Silence.
Three years earlier, Emily and Mark had begged me to help them buy the apartment. They promised they would refinance within a year.
They never did.
Instead, they quietly stopped making payments.
And last week, I received a notice from the lender.
The property was heading toward foreclosure.
So I made a decision.
I paid the overdue balance.
Not because I wanted their apartment.
Because I wanted my money back.
Emily suddenly leaned forward.
“You can’t sell our home!”
“I can,” I replied. “You can’t afford it.”
Mark finally spoke.
“Mrs. Carter, please. Give us time.”
I looked at both of them.
“You gave me three years.”
Emily grabbed the brochure and tore it in half.
“You’re punishing us because we suggested assisted living?”
“No.”
I stood and picked up my purse.
“I’m responding to the fact that you planned my future while secretly destroying mine.”
Then my phone buzzed.
A message from my attorney appeared.
URGENT: I FOUND THE SECOND PROPERTY DEED. YOU NEED TO SEE THIS BEFORE THEY DO.
I looked at Emily.
She noticed my expression.
“What did your lawyer find?”
I slipped my phone into my purse.
“Something you should have told me about.”
And suddenly, Emily stopped looking angry.
She looked frightened.
The brochure was only the beginning.
Because the apartment wasn’t the only asset connected to my name—and the document my attorney had uncovered suggested that someone had been making financial decisions behind my back.
What I discovered next would turn a simple family argument into a battle over a property nobody expected me to still control.
Emily followed me into the parking lot.
“Mom, wait!”
I stopped beside my car.
She grabbed my arm.
“What did your attorney find?”
I pulled away.
“You should ask your husband.”
She turned toward Mark.
He looked trapped.
“Mark?”
“I don’t know what she’s talking about.”
I almost laughed.
“You will.”
My phone rang.
It was my attorney, David.
“Linda, are you somewhere private?”
“Yes.”
“Good. I reviewed the records you sent me.”
His voice was serious.
“The apartment isn’t the biggest problem.”
I glanced at Emily and Mark through the windshield.
“What is?”
“Your late husband’s old investment property.”
My heart stopped.
“What property?”
“The one on Westbrook Avenue.”
I remembered it immediately.
Years ago, my husband had purchased a small commercial building before he died. After his death, I assumed it had been sold.
David continued.
“It was never sold.”
I gripped the phone.
“Then who has been collecting the rent?”
Silence.
“That’s what I was about to tell you.”
He sent me a document.
I opened it.
A property-management company had been receiving monthly rent payments for years.
But the account receiving those payments wasn’t mine.
It belonged to a company registered under Mark’s name.
My stomach tightened.
“How much?”
“Approximately $8,000 a month.”
For nearly four years.
That was hundreds of thousands of dollars.
I looked at Mark.
He was staring at me.
He knew.
Emily suddenly whispered, “Mom…”
I put the phone on speaker.
David continued.
“There is something else. Someone filed a transfer document attempting to move the property into that company.”
“When?”
“Two months ago.”
My blood ran cold.
“Who signed it?”
David paused.
“Your daughter.”
Emily’s face collapsed.
“That isn’t true.”
David said, “Her signature appears on the filing.”
Emily shook her head violently.
“I never signed anything!”
Mark stepped backward.
I looked at him.
“Did you?”
He didn’t answer.
Then Emily’s phone rang.
She glanced at the screen and froze.
“It’s the property manager.”
She answered.
A man’s voice came through.
“Emily, your husband told us your mother had approved the transfer.”
Emily slowly looked at Mark.
“You told them Mom approved it?”
Mark’s face turned white.
He finally whispered, “I was going to fix everything.”
I felt something inside me break.
“You weren’t fixing anything.”
Mark suddenly stepped toward me.
“Linda, please. We were drowning.”
“You stole from me.”
“I borrowed it.”
“For four years?”
“I intended to pay it back.”
David interrupted.
“Linda, don’t argue with him. We need to preserve the records.”
Then he said something that made Emily gasp.
“There are also two unauthorized withdrawals from Linda’s retirement account.”
I stared at my daughter.
Emily covered her mouth.
“I didn’t know.”
Mark backed away.
“I can explain.”
“No,” I said.
“You can explain that to the police.”
Mark’s expression changed.
And then he said the one thing I never expected.
“You can’t report me.”
“Why?”
“Because Emily knew.”
Emily turned toward him.
“What?”
Mark looked at her.
“You signed the first document.”
Emily’s face went completely blank.
And I realized the family betrayal was much deeper than I had imagined.
Emily stared at Mark.
“I signed what?”
Mark swallowed.
“The authorization.”
“What authorization?”
“The one that let me manage the property.”
Emily shook her head.
“I thought it was a refinancing form.”
Mark’s silence told her everything.
She turned toward me.
“Mom, I swear I didn’t know.”
I believed that she hadn’t understood the full situation.
But there was still a problem.
Her signature was on the document.
And legally, that mattered.
David told us to meet at his office the next morning.
Emily barely slept.
Neither did I.
I kept thinking about the brunch.
The brochure.
The cheerful way my daughter had announced that she had found an assisted-living facility for me.
At first, I had assumed it was simply insensitive.
Now I understood that it had been part of something bigger.
The next morning, David spread several folders across the conference table.
“We need to separate three issues,” he said.
“The apartment.”
“The commercial property.”
“And the retirement withdrawals.”
He looked at Emily.
“Your signature appears on a limited authorization.”
Emily nodded slowly.
“I remember signing something. Mark told me it was necessary because the property needed refinancing.”
David pointed to another document.
“But this authorization was later used to support a transfer attempt.”
Emily looked sick.
“I didn’t know.”
“I believe you,” David said. “But that doesn’t automatically erase the legal consequences.”
She lowered her head.
I reached across the table.
“Emily.”
She looked up.
“I need you to tell me everything.”
She took a deep breath.
Then she finally did.
Months earlier, Mark had told her that they were struggling financially.
Their apartment payments had fallen behind.
His business had accumulated debt.
He said my commercial property could be used as temporary collateral.
Emily had agreed to help.
But Mark didn’t tell her that the property was still legally mine.
He also didn’t tell her that he had been collecting rent from the building.
The money had gone toward his business debts.
Some had paid credit cards.
Some had paid contractors.
Some had covered their mortgage.
And some had disappeared into an account Emily didn’t know existed.
But there was another twist.
Mark hadn’t started the scheme.
David had discovered the first unauthorized transaction from four years earlier.
The money had initially been transferred by Mark’s business partner.
Mark had later taken control of the account and continued using it.
When his business partner left, Mark inherited the entire mess.
Instead of confessing, he doubled down.
He kept borrowing against the property.
He believed he could eventually sell his business, repay everything, and nobody would ever know.
Then the business failed.
That’s when the apartment payments stopped.
And that’s when Mark began planning something desperate.
He wanted to sell my commercial property.
He believed the sale proceeds would erase the debt.
The assisted-living conversation suddenly made sense.
If I moved into a facility, he assumed my finances would become easier to manage.
He had hoped to persuade me to give him authority over my accounts.
Then he could solve his financial crisis.
Emily looked horrified.
“Mark never told me any of this.”
I believed her.
But I still couldn’t excuse her behavior.
She had brought the brochure.
She had talked about moving me.
She had treated me like an inconvenience.
Even if she hadn’t known about the fraud, she had been willing to make major decisions about my life without asking what I wanted.
David looked at me.
“There is one more thing.”
He opened another folder.
The apartment’s title.
“I reviewed the loan.”
I expected bad news.
Instead, he smiled faintly.
“Linda, you don’t need to sell the apartment immediately.”
I frowned.
“Why?”
“Because your original guarantee gives you certain rights.”
He explained that when I helped Emily and Mark purchase the apartment, I had been added as a guarantor and secondary secured party.
Because the mortgage had fallen behind, I had the legal ability to protect my financial interest.
I could require them to refinance.
Or sell the property voluntarily.
But I could not simply throw them out without following the proper legal process.
That mattered to me.
I didn’t want revenge.
I wanted boundaries.
I told Emily and Mark they had ninety days to refinance the apartment or sell it.
As for my commercial property, I wanted complete control restored.
The unauthorized withdrawals from my retirement account were reported.
The bank investigated.
Fortunately, most of the money was recovered because the transfers had been flagged.
The property transfer was also stopped before it became permanent.
Mark’s business entered bankruptcy proceedings.
He eventually admitted to the unauthorized transactions.
The legal consequences were serious.
But I never enjoyed watching him suffer.
He had made terrible choices.
That didn’t mean I needed to become cruel.
Emily was different.
She came to my house several weeks later.
She didn’t bring flowers.
She didn’t bring another brochure.
She brought a handwritten letter.
“I don’t expect you to forgive me,” she said.
I opened the door wider.
“Come in.”
She sat at my kitchen table.
“I was embarrassed by how dependent we had become on you,” she said.
“So instead of admitting it, I tried to make you feel dependent on us.”
I looked at her.
“That hurt.”
“I know.”
She started crying.
“I thought putting you somewhere comfortable would make everything easier.”
“For whom?”
She didn’t answer.
I did.
“For you.”
She nodded.
“Yes.”
That honesty mattered.
Not enough to erase what happened.
But enough to begin rebuilding something.
A few months later, Emily sold the apartment.
She moved into a smaller place.
She found a job.
She stopped asking me for money.
And, more importantly, she stopped making decisions for me.
The commercial property remained mine.
I hired a professional management company and opened a separate account for the rent.
I also updated every estate document.
No family member would ever again have financial authority simply because they were family.
One Sunday, Emily invited me to brunch.
I almost laughed at the irony.
She slid a menu toward me.
“No brochures,” she said.
I smiled.
“Good.”
We ordered breakfast.
Halfway through the meal, she reached into her purse.
My heart skipped.
She laughed.
“Relax.”
She pulled out a photograph.
It was a picture of us from years earlier.
“Remember this?”
I looked at it.
Emily was twelve.
She was sitting beside me at the kitchen table, holding a paper crown she’d made for my birthday.
I smiled.
“I remember.”
“I wanted to give you something.”
She pushed the photograph toward me.
On the back, she had written:
You don’t need to take care of everyone anymore. Let us take care of you when you want it—not when we decide you need it.
I read it twice.
Then I folded the photograph carefully.
“I appreciate that.”
She smiled.
“Mom?”
“Yes?”
“If you ever actually want assisted living someday…”
I raised an eyebrow.
She immediately laughed.
“I’ll wait until you ask.”
“That’s better.”
We both laughed.
The apartment had been sold.
The hidden property was secured.
The money had been protected.
The financial deception had been exposed.
But the biggest change wasn’t financial.
It was the boundary I finally established with my own daughter.
Family doesn’t mean unlimited access.
Love doesn’t mean surrendering control.
And caring for an aging parent doesn’t mean deciding that person has stopped being capable of making their own choices.
That brunch had started with a brochure meant to send me away.
It ended with something much more valuable.
My daughter finally understood that I wasn’t an obligation to be managed.
I was her mother.
And I deserved to be treated like one.
As for the apartment?
Emily never forgot the day I told her it was listed for sale.
Years later, she still jokes about it.
“Mom,” she once said, “you scared ten years off my life with that sentence.”
I smiled.
“You scared ten years off mine with that brochure.”
Then we laughed.
Because sometimes the most important thing a family can learn isn’t how to protect its money.
It’s how to stop treating love like a transaction.