My husband stole my credit card, took his mother on a first-class luxury vacation, and told me to “know my place.” I let them enjoy every minute. When they came home, my lawyer and one white envelope were waiting.
At 5:17 a.m., my phone lit up with a fraud alert for $14,862.
Two first-class tickets to Maui. Five nights at an oceanfront resort. A private car from the airport.
I sat straight up and reached for my wallet.
My black credit card was gone.
So was my husband.
I called Ryan three times before he answered. Behind him, I heard airport announcements and his mother laughing.
“Where are you?” I asked.
“At the gate.”
“With my card?”
He sighed, like I was embarrassing him. “Emily, don’t start.”
Then Diane’s voice floated through the phone. “Tell her we’re boarding.”
My stomach turned. Ryan had spent months complaining that I was “too controlling” with money because I refused to fund his mother’s luxury trips. Now he had taken my card while I slept and charged nearly fifteen thousand dollars before sunrise.
“You stole from me,” I said.
Ryan lowered his voice. “It’s our money.”
“No. That card is in my name.”
“We’re married. Stop acting dramatic.”
I heard a flight attendant announce first-class boarding.
Then he said the sentence that ended my marriage.
“Maybe this will finally teach you to know your place. Mom raised me. She deserves to be treated better than you.”
Diane laughed.
I went very still.
For years, I had paid the mortgage and stayed quiet while Diane called me selfish for keeping the savings my father left me separate. Ryan knew that money existed, but not how much.
He thought the card was connected to it.
It wasn’t.
“Have a good trip,” I said.
Ryan chuckled. “See? That wasn’t so hard.”
I smiled after he hung up.
Then I called the card issuer, reported the card stolen, and asked them to preserve every authorization record. I called my bank. Then I called Rachel Kim, the attorney who had handled my father’s estate.
By 8:30, Rachel was at my kitchen table with her laptop open.
She asked one question.
“Did Ryan ever have permission to sign your name on financial documents?”
My smile disappeared.
“No.”
Rachel turned the screen toward me.
Three weeks earlier, someone had submitted an application for a $240,000 home-equity line using my income, my Social Security number, and a scanned copy of my signature.
The application listed Ryan as the person authorized to receive the funds.
But that wasn’t what made Rachel go quiet.
She reached into her folder, pulled out a document, and said, “Emily, the vacation isn’t what you need to worry about.”
Then she pointed to the signature page.
It wasn’t just my name Ryan had forged.
There was a second signature underneath it.
My father’s.
“My father died two years ago,” I whispered.
“I know,” Rachel said.
The document was labeled an amendment to the Carter Family Trust. According to it, my father had supposedly added Ryan as a co-trustee shortly before his death, giving Ryan authority over the house my father had left in trust for me.
There was one problem.
Rachel had drafted my father’s real trust documents herself.
“That amendment never existed,” she said.
My hands started shaking.
The forged amendment had been uploaded with the home-equity application to make it appear Ryan had authority to borrow against the property. Rachel immediately called the lender’s fraud department and sent them my father’s death certificate, the genuine trust, and her original records.
The loan had not funded yet.
It was scheduled to fund Monday.
Ryan and Diane were in Maui until Sunday night.
That afternoon, Ryan called from the resort.
“My card isn’t working.”
“Because it’s stolen.”
“It’s not stolen. I’m your husband.”
“You took it without permission.”
His voice hardened. “Turn it back on.”
“No.”
Diane grabbed the phone. “Do you understand how humiliating this is? We’re at a five-star hotel.”
“Then use your own card.”
She hissed, “After everything my son has done for you?”
I almost laughed.
Then Ryan came back on. “Fix it, Emily. Don’t make me come home angry.”
Rachel, sitting across from me, quietly pressed Record on her phone.
I said, “Enjoy Maui.”
Then I hung up.
The next morning, Rachel received the lender’s internal file.
That was when the situation became much worse.
The $240,000 wasn’t being sent to Ryan.
The wiring instructions named an LLC called DMC Property Group.
I recognized the initials immediately.
Diane Marie Collins.
Rachel searched the state business registry. Diane had formed the company six weeks earlier.
Then she found something else.
A deed had been recorded with the county eleven days ago.
I stared at the screen, unable to breathe.
The deed claimed I had transferred my house out of my father’s trust and into joint ownership with Ryan.
My signature appeared at the bottom.
I had never signed it.
The notary stamp belonged to a woman named Allison Reed.
Rachel called her.
Allison went silent when Rachel gave her the recording number.
“I didn’t notarize that woman’s signature,” she said. “A man contacted me about an appointment, but he canceled.”
Rachel asked if she still had the messages.
“Yes.”
Ten minutes later, screenshots arrived.
Ryan had sent Allison a photo of my driver’s license.
Then another message appeared beneath it.
From Diane.
Make sure the deed is done before the trip. Once the credit line clears, she can’t stop us.
I felt physically sick.
This wasn’t Ryan impulsively stealing a credit card.
They had planned it.
Rachel contacted the county recorder, the lender, and a detective in the financial-crimes unit. By Friday afternoon, the loan was frozen and a fraud affidavit was filed.
Then Rachel printed one final document.
A petition for divorce.
On Sunday night, I placed it inside a plain white envelope on the entry table.
But ten minutes before Ryan’s flight landed, the detective called.
“Mrs. Carter,” he said, “do not confront your husband alone.”
I looked at Rachel.
“Why?”
“Because we found another application.”
He paused.
“This one is for seven hundred and fifty thousand dollars.”
The second application was tied to a lake house my father had left me outside Madison.
It had no mortgage.
Ryan had used a forged power of attorney claiming I had authorized him to borrow against it. The private lender had been asked to wire $750,000 to the same company Diane controlled.
Detective Mark Ruiz explained that the application surfaced only because the first lender circulated a fraud alert through its title company. The same title examiner recognized my name.
“They were trying to pull money from two properties at the same time,” he said. “Do not delete anything they send you.”
At 9:40 p.m., Ryan texted.
Home in twenty. Hope you fixed the card.
I showed Rachel.
She looked at the white envelope. “No more arguing with him. Let the documents speak.”
At 10:03, headlights swept across the windows.
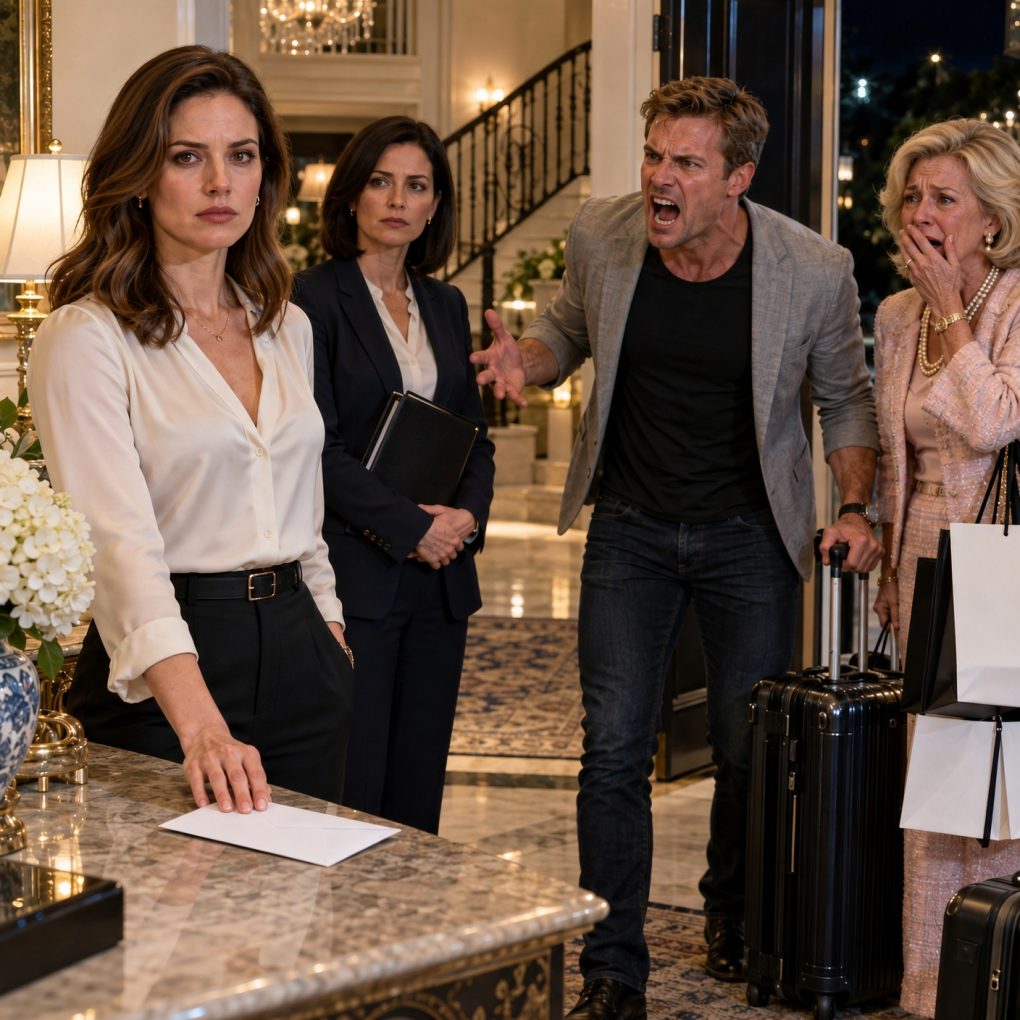
Ryan walked in first, tanned and irritated, dragging a designer suitcase. Diane followed wearing sunglasses on top of her perfectly styled blonde hair and carrying three shopping bags.
Ryan stopped when he saw Rachel.
“What is she doing here?”
Diane looked at me. “If this is about the hotel bill, grow up.”
Ryan dropped his suitcase. “Emily, seriously?”
I slid the white envelope across the table.
“For you.”
He tore it open.
His face changed on the first page.
Petition for dissolution of marriage.
Notice to preserve financial records.
Copies of the fraud affidavits.
A court order temporarily preventing either party from transferring disputed assets while the case was pending.
Then he reached the final page.
It was a copy of the recorded deed bearing my forged signature.
Ryan looked up.
“You went through my things?”
“No,” I said. “You filed it in a public office.”
Diane stepped closer. “Married people share property.”
Rachel finally spoke.
“Inherited property held through the Carter Family Trust is not automatically yours because your son married Emily. Forging trust documents does not change ownership.”
Ryan pointed at me. “You’re really going to destroy our marriage over a vacation?”
“You stole my card, forged my signature, forged my dead father’s signature, and tried to borrow almost a million dollars against property you don’t own.”
“It was an investment.”
“For your mother’s company?”
Silence.
Then someone knocked.
Detective Ruiz stood outside with another officer.
Diane whispered, “Ryan?”
For the first time, he looked scared.
Ruiz asked Ryan to step outside. Ryan demanded a lawyer and called it a “family money issue.” Ruiz told him he had every right to an attorney, then explained that the investigation involved suspected identity theft, forgery, attempted loan fraud, and filing a false instrument.
Diane backed toward the hallway.
Ruiz looked at her.
“Ms. Collins, we also need to speak with you about DMC Property Group.”
Her shopping bag slipped from her hand.
A box of expensive sandals hit the floor.
The woman who had laughed while my husband told me to know my place suddenly looked at me as if I could save her.
“Emily,” she whispered, “tell them this is a misunderstanding.”
I said nothing.
The investigation took months.
Neither loan ever funded.
After the forged deed was challenged, the title was restored to the trust records. The credit-card company reversed the unauthorized travel charges after its investigation, although Ryan remained responsible for purchases he had put on his own card when mine stopped working.
The evidence became difficult for him to explain.
The lender had his IP address.
The title company had emails from him.
Allison, the notary, had his messages.
Diane’s company was listed as the destination for both attempted transfers.
Investigators also recovered a draft email from Ryan’s laptop: Once the loans clear, we can move the money before she figures it out.
Ryan eventually entered a plea agreement on charges related to the forged documents and attempted fraud. Diane also faced charges connected to the applications and her company’s role. Their lawyers handled the criminal case; Rachel handled my divorce.
Ryan fought hardest over the house.
He told the court he had “invested years” into our marriage and deserved half.
Rachel produced the trust, my father’s estate records, the original deed, and the financial history showing that the property had passed to me separately.
Ryan got no ownership interest in my father’s trust property.
The divorce still required the normal division of actual marital assets and debts, but the fortune Ryan thought he could seize was never his.
At the final hearing, he barely looked at me.
Outside the courtroom, he said, “You could have just talked to me.”
I almost laughed.
“I did. You told me to know my place.”
He looked away.
“I do now.”
My place was not behind him.
It was not beneath his mother.
It was not quietly paying for people who treated my kindness like weakness.
My place was inside the life I had protected after they tried to steal it from me.
Six months later, I sold the lake house. Not because Ryan had ruined it, but because I no longer wanted every room connected to the fight he had started. I kept my father’s home, changed the locks, and turned Ryan’s old office into a reading room.
The white envelope stayed in a drawer for a long time.
Not because I missed him.
Because sometimes I needed the reminder.
Ryan thought luxury meant first class, oceanfront suites, and spending someone else’s money.
I learned something different.
Luxury was waking up in a house nobody was trying to take from me.
Luxury was opening my banking app without fear.
Luxury was silence after years of being told where I belonged.
And the best part?
I never had to tell Ryan where his place was.
The law, the bank records, and his own signatures did that for me.