The splash came less than thirty seconds after I told my father I would not give him $139,000.
I was standing on my parents’ patio outside Tampa when Dad picked up my laptop from the table.
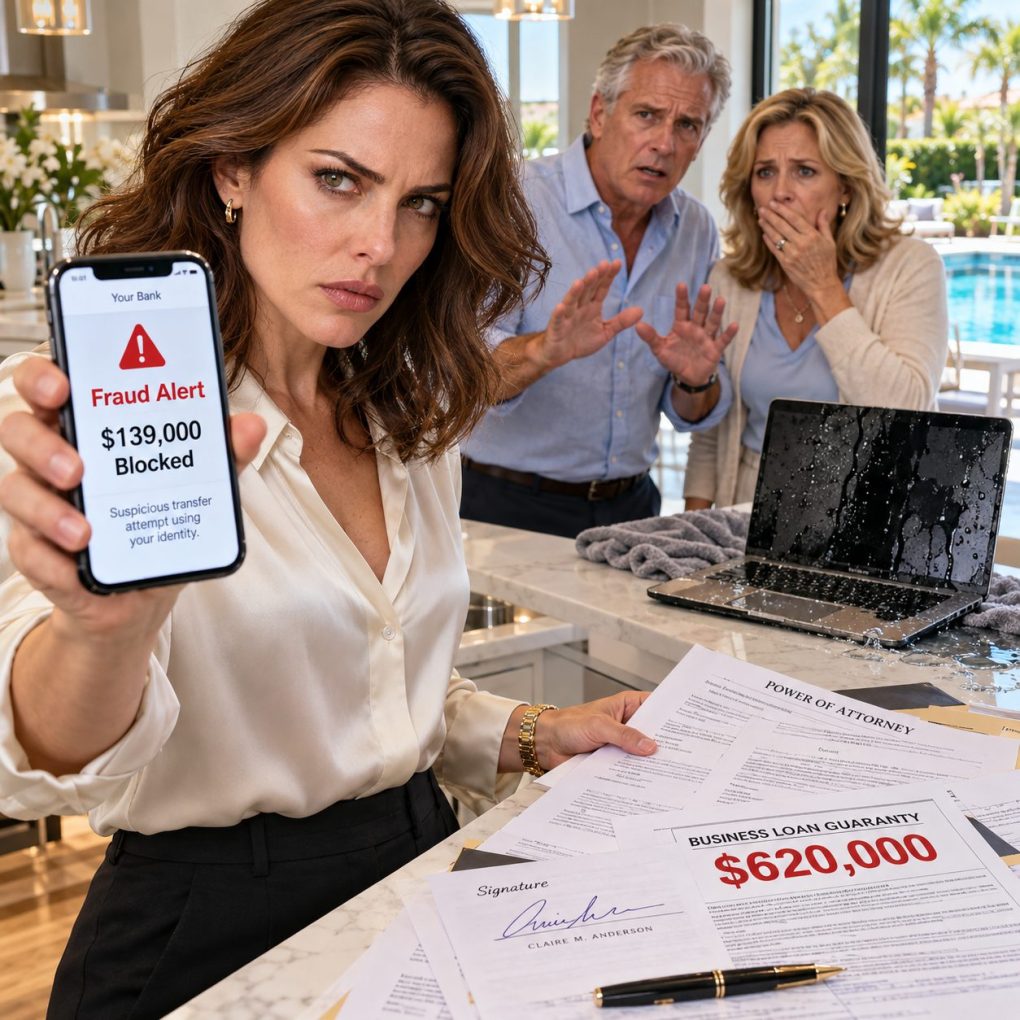
“Oh, sorry—I accidentally dropped your laptop in the pool.”
He said it with a smile.
My MacBook hit the water open.
For a second, nobody moved. Mom looked from the pool to me and shrugged. “It’s just an accident, Claire. Don’t make a scene.”
I stared at the laptop sinking beneath six feet of blue water. It contained client files, tax records, contracts, and financial models for the consulting firm I had spent nine years building.
Dad knew that.
He also knew I had refused his proposal ten minutes earlier.
He and Mom wanted to buy a struggling waterfront restaurant in Clearwater and turn it into a “family legacy business.” The asking price was $410,000. They had little cash, weak credit, and a lender willing to proceed only if they brought in $139,000.
They expected that money from me.
Not as a loan.
As a “family contribution.”
When I said no, Dad called me selfish after “everything they’d done for me.” Mom reminded me that my younger brother, Evan, had agreed to manage the restaurant.
She didn’t mention Evan had put in zero dollars.
I closed the folder and said, “I’m not financing this.”
Then Dad reached for my laptop.
Now water rippled across the pool while he pretended it had slipped.
I didn’t yell. I didn’t threaten them. I didn’t even retrieve it.
I simply said, “Okay.”
Dad looked disappointed, almost as if he had wanted a fight.
I drove home to my condo in St. Petersburg and opened the fireproof box in my bedroom closet. Inside were copies of every financial arrangement I had quietly maintained for my parents for four years.
Their health insurance premiums.
Their car payments.
The $2,850 monthly mortgage payment on their house.
Their phones.
Their homeowners insurance.
A credit card I had given them for emergencies that somehow averaged $2,000 a month.
After Dad’s construction company collapsed, I stepped in because I thought helping family meant helping them recover.
Apparently, they had started thinking I belonged to them.
At 11:47 p.m., I logged into every account I legally controlled.
I stopped recurring transfers, removed my card from their utilities, canceled the phone plan scheduled to renew the following week, and froze the authorized-user cards tied to my account.
Then I emailed Dad one sentence:
“Just a small mistake.”
I slept better than I expected.
At 8:31 the next morning, my phone lit up with Mom’s name.
Then Dad.
Then Evan.
By 8:38, I had nineteen missed calls.
At 8:41, Dad left a voicemail.
His voice was no longer smug.
“Claire, call me. The bank says the mortgage payment was reversed, both cards are dead, and your mother’s car payment failed. What did you do?”
I was about to delete it when another notification appeared.
It was from my bank’s fraud department.
Someone had tried to initiate a $139,000 transfer from my business savings account at 8:27 that morning.
And the authorization request carried my father’s name.
For one terrible moment, I thought canceling the payments had been the whole story. It wasn’t. The laptop in the pool had been retaliation, but the forged transfer was only the first clue that my parents had gone much further than I imagined.
I called the fraud department before I called my family.
The investigator, Marisol Vega, said the transfer had been blocked because the request came from an unfamiliar device and tried to move nearly the exact amount I had discussed with my parents the night before.
Then she said something that made my stomach drop.
The request included an authorization form bearing my signature.
I told her I had signed nothing.
Within twenty minutes, my business accounts were locked against outgoing transfers, my passwords were reset, and the bank opened a fraud case. I also called my attorney, Rachel Kim, who told me not to confront anyone until she saw the documents.
Dad kept calling.
At 9:12, Evan texted: Stop being dramatic. Dad said you already promised the money weeks ago.
I had never promised anything.
Rachel called at 10:05. The bank had sent her the authorization packet with my permission. She asked whether I had ever given Dad power of attorney.
“Once,” I said. “In 2022, when I was working in Seattle. Limited authority for the sale of my old condo.”
“That’s what I thought,” she said. “Someone attached that old power of attorney to yesterday’s transfer request.”
My hands went cold.
Someone had removed the pages describing its limited purpose and presented it as if Dad still had authority over my finances.
Then Rachel told me there was more.
The restaurant’s lender had sent over its file.
My name was listed as a 40 percent investor. My income appeared in the underwriting package. And a personal financial statement supposedly signed by me showed $1.6 million in assets.
“That isn’t mine.”
“I know.”
At 10:22, Mom left a voicemail.
She was crying.
“Claire, please don’t involve lawyers. Your father was only trying to make sure the deal didn’t fall apart. We were going to explain everything after closing.”
After closing.
Those two words changed everything.
They had built the restaurant deal around my money and identity before I ever said no.
I drove to Rachel’s office.
She had one final document waiting on the conference table.
It was an email from the lender’s file, sent six days earlier from an address containing my full name.
The message said I authorized my father, Daniel Mercer, to act for me regarding funding and guarantees for the Clearwater acquisition.
I had never created that email address.
But the recovery phone number ended in four digits I recognized.
My mother’s.
Below it was something worse: a signed personal guaranty for a $620,000 business loan.
If the restaurant failed, the lender believed it could come after me.
Rachel looked across the table.
“Claire, your parents weren’t asking you for $139,000.”
She tapped the guaranty.
“They were trying to make you responsible for everything.”
For a few seconds, I could only stare at the guaranty.
Then Rachel slid a legal pad toward me. “From this point forward, treat this like identity theft, not a family argument.”
That helped.
Family arguments are emotional. Fraud leaves records.
That afternoon, I signed a sworn statement for the bank. Rachel notified the restaurant lender that I had never invested in the purchase, authorized Dad to act for me, or signed the guaranty. I froze my credit, changed every financial password, revoked the old limited power of attorney, and filed a police report.
The lender suspended the closing immediately.
By five o’clock, the $139,000 transfer was permanently rejected.
No money left my account.
Then, at 6:18, Mom sent the message that changed the case.
Your father only used the old paperwork because the lender was rushing us. We knew you would come around once you saw the restaurant making money. I made the email because they needed a contact address and you weren’t cooperating. Nobody was stealing from you.
I read it twice and forwarded it to Rachel.
Do not answer, she replied. Preserve this.
Mom had just admitted creating the fake email.
The next morning, Evan called from another number because I had removed him from the family phone plan too.
He sounded scared.
Dad had promised him a $75,000 salary to run the restaurant and told him I was the “silent investor.” Evan swore he knew nothing about the fake email, altered power of attorney, or guaranty.
Rachel later confirmed that none of the fraudulent documents came from Evan.
Still, he had insulted me when he thought Dad had access to my money.
“Did it ever occur to you to ask whether I’d agreed?” I asked.
He went quiet.
“No.”
“Exactly.”
Three days later, the restaurant deal collapsed.
The lender withdrew. The seller refused to extend the contract. My parents lost their earnest-money deposit and what they had already paid consultants and inspectors.
Dad told relatives I had destroyed the family’s retirement over a misunderstanding.
An aunt called to lecture me about forgiveness.
I gave her one fact.
“My parents tried to take $139,000 from my business account and make me personally responsible for a $620,000 loan without my consent.”
She stopped lecturing.
Two weeks later, Dad and Mom met me at Rachel’s office.
Dad arrived furious.
“You canceled our entire lives over a computer?”
“No,” I said. “The computer was the moment I stopped pretending this was normal.”
He insisted he would have repaid me once the restaurant became profitable.
Rachel asked why he had altered a limited power of attorney if everything was legitimate.
Dad’s face changed.
Mom stared at the table.
Then Dad said the sentence that ended something inside me.
“You’re our daughter. We shouldn’t need permission for every little thing.”
I looked at him.
“You needed permission for my money. You needed permission for my name. You needed permission to put me $620,000 in debt.”
Mom began crying.
She admitted she had created the email account because Dad feared the lender would contact me directly. She also admitted Dad had taken the old power-of-attorney copy from a file box where I stored documents.
Then Rachel asked about the laptop.
For the first time, Dad stopped calling it an accident.
He admitted he had been angry that I refused to “support the family.” Dropping it in the pool was supposed to teach me what it felt like when someone ruined my plans.
The investigation took months.
The bank produced records tied to the attempted transfer. The lender turned over the altered documents. Mom’s fake email was linked to her phone number, and investigators found copies of the altered authorization pages on Dad’s computer.
No money had actually been transferred, and the restaurant loan never funded. That mattered legally.
But the conduct did not disappear.
Dad eventually accepted a plea agreement on fraud-related and identity-theft charges. He received probation, restitution obligations, and community service. Mom cooperated, accepted responsibility for her role, and received a lighter outcome.
I did not ask Rachel to punish them as harshly as possible.
I asked her to make sure I was protected.
The lender confirmed in writing that I owed nothing under the proposed loan. The bank closed the fraud investigation in my favor. I kept my credit frozen and added extra verification to every business account.
Then came the consequence my parents hated most.
I never restarted the payments.
Without my support, they had to confront the life they had actually been able to afford.
Dad sold his truck. Mom traded her luxury SUV for a used Honda. They canceled vacations and memberships. Six months later, they sold the Tampa house and moved into a smaller townhouse.
They told people I had forced them out.
I reminded myself of the difference.
I had not taken their house.
I had stopped paying for it.
Evan found a sales job at a building-supply company. About eight months later, he asked to meet for coffee.
“I liked believing Dad,” he said. “His version gave me a restaurant without me risking anything.”
It was the first completely honest thing I had heard from him.
We eventually started speaking again, cautiously, with one permanent rule: no money.
Mom and I took longer.
Nearly a year passed before she mailed me a handwritten letter. She did not ask for help. She did not blame Dad.
She wrote that she had convinced herself taking from me temporarily was acceptable because I was successful enough to survive it.
That sentence hurt.
But at least it named the real problem.
They had treated my success like family property and my boundaries like disobedience.
I never returned to my old role.
My parents now pay their own bills. Evan pays his. I pay mine.
My business survived. So did my files. Almost everything on the drowned laptop had been encrypted and backed up, and I replaced the computer within a week.
Sometimes I still picture it sinking into the pool.
Dad expected me to scream.
If I had, maybe everything would have become another loud family argument. They would have called me emotional, apologized eventually, and waited for me to keep paying.
Instead, I said, “Okay.”
Then I went home and stopped financing people who believed love gave them access to me.
Dad called the laptop an accident.
Mom called the forged documents temporary.
They called the restaurant a family dream.
But names do not change facts.
And the most important thing I canceled that night was not a card, a phone plan, or a recurring payment.
It was their assumption that I would always pay the price for whatever they chose to do.