I thought putting my inheritance into a trust was probably unnecessary. My grandmother had left me several million dollars when she died, but the money could not legally come under my control until I turned eighteen. My family had never openly threatened me or demanded anything, so when Grandma’s attorney, Margaret Cole, suggested creating an independent trust the moment I became an adult, I almost laughed. Still, something about the way she said, “Protection feels unnecessary until the day it isn’t,” convinced me.
At 9:10 on the morning of my eighteenth birthday, Margaret completed the transfer. The trust now held approximately $4.2 million in investments and cash, with me as beneficiary and an independent corporate trustee overseeing major withdrawals. My mother, Denise, called it ridiculous when I mentioned I had “handled some paperwork,” but she did not ask for details. That evening, my parents threw me a large birthday dinner at our house outside Philadelphia. My uncle Mark came, my mother’s sister Laura came, and everyone seemed unusually interested in my plans for college.
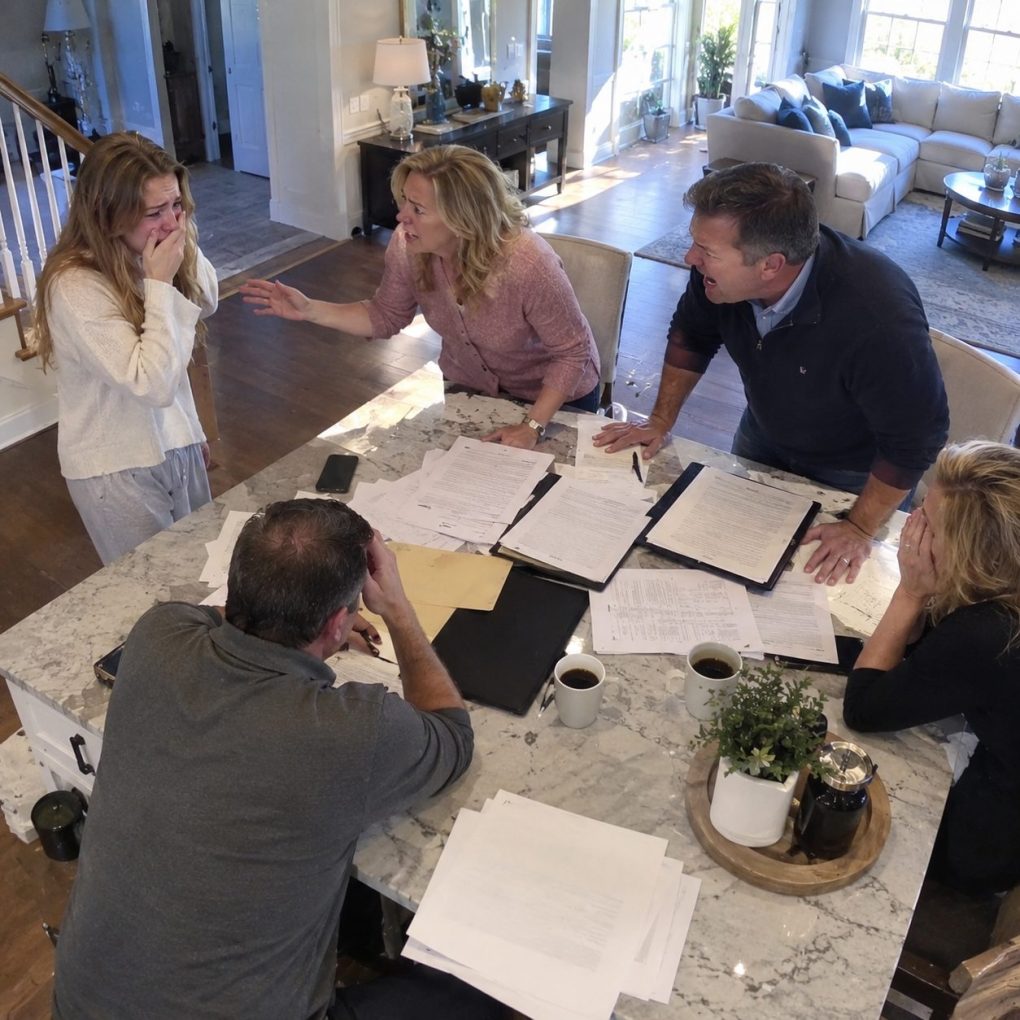
I woke the next morning to voices downstairs. It was barely seven. When I walked toward the kitchen, I heard my stepfather, Richard, say, “Once she signs, we can move the first six hundred thousand immediately.” I froze halfway down the staircase. My mother answered, “She’ll sign. Tell her it’s for tax purposes.” Then Uncle Mark asked whether his $180,000 would come before or after they paid the mortgage.
I stood there gripping the railing so hard my fingers hurt.
On the kitchen table were three folders I had never seen before. One contained a broad power of attorney naming my mother as my financial agent. Another authorized transfers from an investment account that no longer existed in my name. The third was a handwritten page titled FAMILY ALLOCATION, listing $600,000 for the mortgage, $180,000 for Mark’s business, $250,000 toward a Florida property, and $90,000 for Laura’s debts.
They had already divided more than a million dollars of my inheritance.
My mother finally noticed me standing in the doorway. Nobody spoke for several seconds.
Then she forced a smile.
“Good,” she said. “You’re awake. We just need you to sign a few things.”
I looked at the papers, then at all four of them.
“What happens,” I asked quietly, “if the money isn’t there anymore?”
Richard laughed.
My mother didn’t.
And that was the exact moment I realized she knew something had gone wrong.
“What do you mean, it isn’t there?” my mother asked. Her smile vanished so quickly that it frightened me more than shouting would have. I told her I had moved the inheritance into a trust the previous morning. Richard immediately pushed back his chair. Uncle Mark stopped drinking his coffee. Laura stared at my mother as if she had personally broken a promise to them.
Then the questions came all at once. Which trust? Who controlled it? Could I dissolve it? Could I still withdraw money? Richard grabbed one of the folders and demanded to know whether Margaret Cole had “put this idea in my head.” Nobody asked whether I felt comfortable signing their documents. Nobody explained why they had already assigned exact dollar amounts from money that belonged to me.
My mother finally dropped the gentle voice. “We raised you for eighteen years, Sophie. Do you honestly think none of that matters?” I stared at her because I had expected an explanation, perhaps even embarrassment. Instead, she began listing everything she had paid for since I was born—school clothes, vacations, braces, my first car. It sounded less like motherhood and more like an invoice she had been saving.
When I refused to sign anything, Richard slammed his palm against the kitchen counter. Mark accused me of letting “some lawyer” turn me against my own family. Laura started crying and said she had been depending on the money to stop foreclosure proceedings on her house. That was when I understood this plan had existed long before my birthday. These people had made financial commitments based on an inheritance they had never asked me for.
I went upstairs, locked my bedroom door, and called Margaret.
She told me not to sign a single page.
Twenty minutes later, I photographed every document on the kitchen table while everyone argued in the living room. One page contained something even worse: a draft transfer instruction dated two weeks before I turned eighteen, directing $600,000 into an account belonging jointly to my mother and Richard.
Margaret’s voice became very quiet when I sent it to her.
“Sophie,” she said, “take your identification, your laptop, and anything important. Leave the house.”
That afternoon, I moved into my best friend Hannah’s guest room.
Lying awake that night, I kept thinking about how strange betrayal feels when it comes from people you love. You expect cruelty to announce itself with hatred, but sometimes it arrives disguised as concern, obligation, and the phrase we’re family. I had spent eighteen years believing home was the safest place in my life. In less than twenty-four hours, I learned that safety was never about who shared your last name—it was about who respected your right to say no.
Then Margaret called again.
She had examined the documents.
And what my family had planned was far more organized than I had realized.
Margaret asked me to come to her office the next morning. Waiting beside her was Daniel Brooks, an attorney who specialized in trusts and financial disputes. They spread copies of the documents across a conference table and walked me through what they had found. The unsigned power of attorney itself was not illegal. Neither was my family discussing what they hoped I might voluntarily give them. The disturbing part was the preparation surrounding it.
The proposed transfer instructions contained account numbers, investment details, and approximate balances that I had never shared with my family. Someone had clearly obtained information about the inheritance before I turned eighteen. Margaret suspected that my mother had kept copies of older estate statements sent to our home while I was still a minor. More importantly, the documents showed that Richard had contacted a financial adviser weeks earlier to discuss investments he planned to make once “family capital became available.”
There was still no proof they could have taken the money without my signature. But there was overwhelming proof that they expected my signature to be little more than a formality.
Margaret recommended that all communication about the inheritance go through her office. The trustee placed additional verification requirements on distributions and account information. I changed passwords, froze my credit temporarily, moved my personal banking to a different institution, and collected the remaining documents from the house while Hannah’s father waited outside.
My mother called constantly during the first week.
At first she was furious. Then apologetic. Then furious again.
She said the mortgage payment had increased, Richard’s business was struggling, Mark had employees depending on him, and Laura might lose her home. Every problem was real. That was what made everything harder. They were not cartoon villains sitting around plotting how to destroy me. They were frightened adults who had slowly convinced themselves that my inheritance was the solution to problems they had created.
But their desperation did not create ownership.
Three months later, Richard sent me a long email admitting that the “family allocation” had been his idea. He claimed my mother initially resisted but eventually agreed because they believed I would still have more than enough money afterward. He apologized for assuming my inheritance should become family capital, although he also wrote that he hoped someday I would understand the pressure they had been under.
I understood the pressure.
I simply stopped accepting it as an excuse.
Uncle Mark eventually refinanced his business and sold one of his properties. Laura negotiated a repayment plan with her lender. My mother and Richard sold their oversized house the following year and moved somewhere smaller. None of those solutions were easy, but they proved something important: their lives did not collapse because I refused to rescue them.
Mine began moving forward.
I attended college in Pennsylvania and studied economics. The trust paid tuition and reasonable living expenses while most of the principal remained invested. Margaret introduced me to an independent financial adviser who taught me how taxes, diversification, withdrawal rates, and fiduciary responsibility actually worked. For the first time, the inheritance stopped feeling like a mysterious pile of money and became something I knew how to manage.
My relationship with my mother took much longer to repair.
We did not speak for nearly eight months. When we finally met at a small restaurant, I brought no attorney and she brought no paperwork. She apologized without mentioning bills, sacrifice, or how much money I still had. That mattered.
I told her we could rebuild our relationship under one condition: my finances would never again be treated as a family resource.
She agreed.
Trust returned slowly after that, measured not by promises but by behavior.
Years later, I sometimes think about how close I came to ignoring Margaret’s advice. Had I kept the inheritance in an ordinary account, my family still could not legally have taken it without authorization—but eighteen-year-old me might have signed those documents simply because four adults I trusted were telling me that refusing made me selfish.
The trust protected the money.
But more importantly, it created enough distance for me to discover something I had never been taught.
Having boundaries does not mean you love your family less.
Sometimes boundaries are the only reason there is still a relationship left to save.