My family drugged me and stole my home’s deed, but they didn’t realize I set a legal trap three months ago.
“You’re mentally unfit to make decisions like this, sweetie,” my mother purred, sliding a lukewarm cup of mugwort tea across the kitchen island.
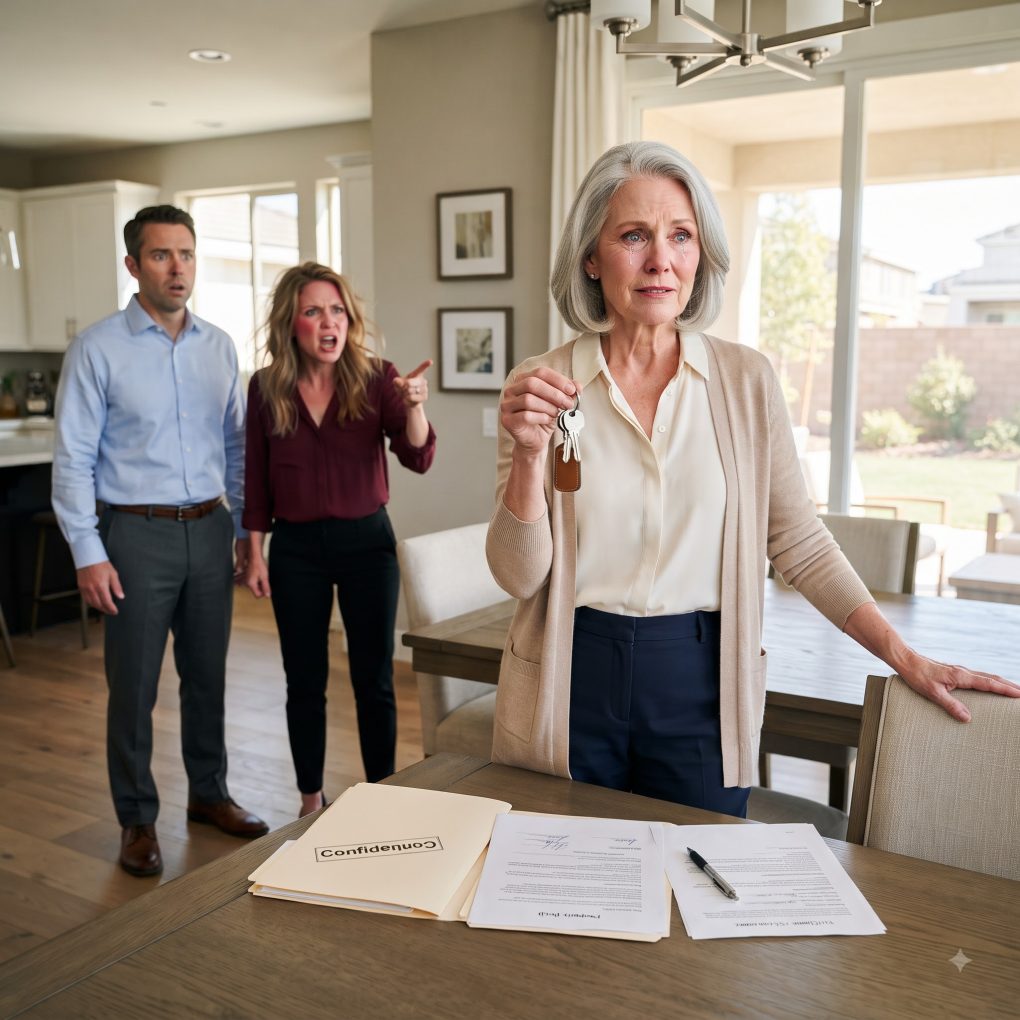
Two hours later, my vision blurred, my limbs turned to lead, and I collapsed onto the hardwood floor of the craftsman bungalow I had spent seven years saving to buy. Through the haze of a forced chemical sleep, I heard the faint click of the front door lock and the muffled voice of my brother, Ethan: “It’s family property now. She can’t handle the responsibility anyway.”
When I finally woke up eighteen hours later on my own sofa, my head pounding like a sledgehammer, I reached for my phone. The first notification on my feed was a photo of my mother, smiling broadly in front of my porch, holding a set of brass keys. The caption read: So proud of her! My daughter finally agreed to let the family manage her estate. Big moves ahead!
I rushed to my home office. The fireproof safe in my closet was wide open. My original deed, title documents, and social security card were gone.
I called Ethan immediately, my voice trembling with rage. “You broke into my house and took my deed?”
“Mom signed the transfer papers as your legal power of attorney, Claire,” Ethan replied smoothly, not a shred of guilt in his voice. “We filed the quitclaim deed with the county clerk this morning. The house is in Mom’s name now. We’re putting it on the market on Friday to liquidate the equity for the family trust. Don’t make a scene. We’re doing this for your own good.”
They thought they had trapped me. They thought my history of anxiety meant they could gaslight me into submission, drug me into compliance, and strip me of my life’s work while claiming to be my saviors. They assumed I would cry, collapse, or beg for their mercy.
They didn’t realize that three months ago, after my mother first hinted that my house “belonged to the lineage,” I had quietly hired a corporate asset attorney and taken out a massive, highly specific insurance policy.
Standing in my looted office, I didn’t cry. Instead, I opened my laptop and filed a report that didn’t just target the stolen deed—it triggered an immediate, automated legal process that my mother and brother never saw coming.
My mother spent years convincing everyone I was too fragile to survive on my own, but she missed the one legal trap hidden inside my property title.
The notification hit my mother’s phone at 8:00 AM on Thursday morning.
I was sitting in a diner two blocks from the county courthouse, sipping black coffee—brewed by a stranger, completely safe—when Ethan called me six times in a row. I let it ring. On the seventh call, I answered.
“What the hell did you do?” Ethan screamed, his voice cracking. “Mom just got served at her house! There are two sheriff deputies outside her front door!”
“I told you not to touch my property, Ethan,” I said calmly.
“You reported the deed as stolen?” he spat. “Are you out of your mind? That’s a felony charge against your own mother! She was just trying to protect the family’s assets!”
“I didn’t file a basic theft report,” I replied softly. “I filed an Affidavit of Forgery, a Notice of Pendency of Action, and a formal claim with the Title Insurance Fraud Division.”
Silence hung on the line for three long seconds.
What my family didn’t know was that when I bought the house, I didn’t just buy standard owner’s title insurance; I added an irrevocable revocable-trust clause linked directly to an independent corporate trustee. The moment a fraudulent transfer document was uploaded to the county database using my forged signature, the title company’s legal defense fund was automatically triggered.
Because the house was worth over $600,000, forging a deed and using a laced beverage to incapacitate the owner wasn’t a civil dispute over “family property.” It was federal-level wire fraud, elder exploitation, and aggravated assault.
“Claire, listen to me,” Ethan’s tone instantly shifted from aggressive to desperate. “Mom didn’t forge it alone. She… she had help. You need to drop the claim right now before they pull the bank records.”
My heart chilled. “What bank records?”
“Mom didn’t just put the house in her name to hold it,” Ethan confessed, his voice dropping to a panicked whisper. “She took out a $250,000 hard-money equity loan against the property three weeks ago using a power of attorney you signed when you were in the hospital last year. She gave the money to… to someone else.”
I sat frozen in the booth. The power of attorney from last year was supposed to be temporary, restricted solely to medical decisions while I had my appendix removed. She had altered the documents months ago.
“Who did she give the quarter of a million dollars to, Ethan?” I asked, my blood running cold.
“To the buyers who already signed the emergency purchase agreement,” Ethan stammered. “If you block this title transfer, those people aren’t just going to sue Mom. They’re coming after all of us. You don’t know who these people are, Claire.”
The diner suddenly felt entirely too small. My hand gripped the coffee mug so tightly my knuckles turned white. My mother hadn’t just stolen my house out of greed or a warped sense of maternal control—she was caught in something far more dangerous.
“Give me the name of the lender, Ethan,” I demanded, keeping my voice steady despite the adrenaline surging through my veins.
“It’s a private investment firm out of Miami,” Ethan whispered, his confidence completely shattered. “Mom got involved in some high-yield investment scheme six months ago. She lost her savings, then she lost the inheritance left by Grandma. She owed them a quarter-million by the end of this month, or they threatened to foreclose on her own house. She used your home as collateral because she thought she could sell it before anyone noticed.”
The picture finally came together. The constant comments about my “mental instability,” the spiked coffee, the fake post on social media to build a public narrative that I was willingly handing over my estate—it was all a frantic cover-up to save her own skin at my expense.
“I’m not dropping the charges,” I said clearly into the phone.
“Claire, she’s your mother!” Ethan pleaded. “She’ll go to prison!”
“She drugged me in my own home, Ethan,” I replied. “She stole my life savings to cover her own fraudulent gambling debts. If I cover for her now, I lose my home, my credit is destroyed, and I become an accomplice to her fraud. Tell her to call her lawyer.”
I hung up the phone and walked straight into the county courthouse to meet with my attorney, Sarah Vance.
Over the next forty-eight hours, the legal hammer fell swift and uncompromising. Because I had acted immediately, the Lis Pendens (Notice of Pendency of Action) was recorded against the property title before the private lenders could execute their lien. Under state law, any encumbrance placed on a property through a forged document or unauthorized power of attorney is legally void ab initio—meaning it never legally existed in the first place.
The private investment firm attempted to assert their claim, but once the police forensic team recovered the hidden camera footage from my living room—which clearly captured my mother slipping a dissolved substance into my cup and retrieving my safe key while I was unconscious—the district attorney stepped in.
My mother was arrested at her home on charges of grand larceny, forgery, identity theft, and possession of a controlled substance with intent to render a person unconscious. Ethan, who had knowingly assisted in filing the fraudulent documents with the county clerk, was named as a co-conspirator.
Two weeks later, the deed was officially restored entirely to my name. The fraudulent $250,000 loan was wiped clean from my property record, shifted entirely as a personal debt and criminal liability onto my mother.
The social media post my mother had proudly uploaded was taken down, replaced by a cold, formal press release from the local sheriff’s department detailing the fraud ring and the arrests made.
Sitting on my front porch a month later, holding a fresh cup of coffee I brewed myself, the silence of my neighborhood felt different. It no longer felt isolated; it felt earned. My family had tried to use my vulnerability as a weapon to strip away everything I had built, expecting me to remain silent out of misplaced loyalty.
Instead, they learned that protecting yourself isn’t a sign of mental weakness—it’s the ultimate proof of strength.