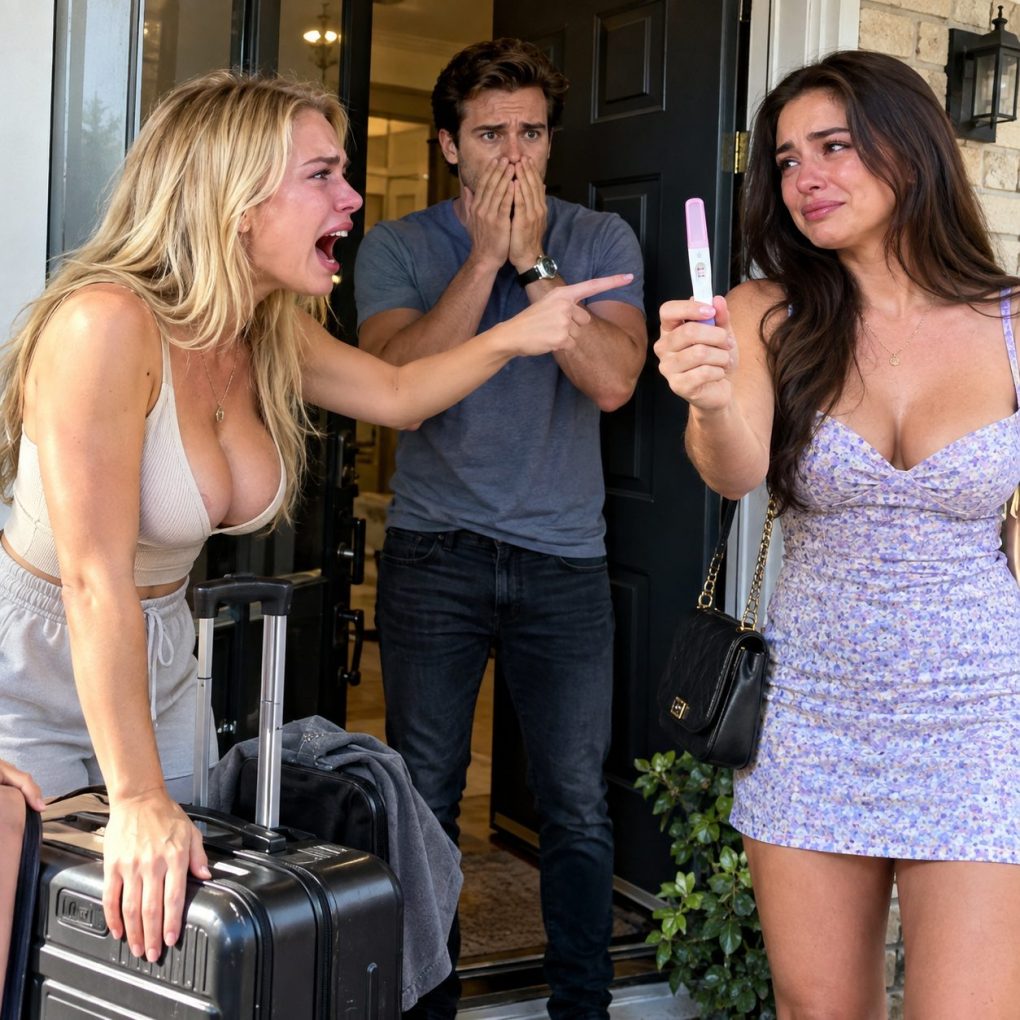
The knock came while I was sealing the last box.
My husband, Adam, was in the kitchen telling someone on the phone that everything was “handled.” He stopped when he saw his ex through the front window.
Six hours earlier, he had canceled our anniversary dinner because Claire “needed him.” I had asked him to stop dropping our plans whenever she called and to be honest about where he went.
He laughed. “I’m not gonna stop seeing her just because you’re jealous. She’s my friend.”
“Okay,” I said.
I had spent three months interviewing for a hospital position in Denver. That afternoon, I accepted the offer. The moving boxes were mine; I had told Adam I was leaving, but he hadn’t looked up from his phone long enough to believe me.
Now Claire stood on our porch, gripping a thick envelope. Her face was blotchy, and she looked frightened rather than triumphant.
Adam opened the door only a few inches. “You shouldn’t be here.”
“You said you told her,” Claire said.
“Told me what?” I asked.
He tried to shut the door. Claire planted her hand against it.
“They called my shop this afternoon,” she said. “The payment bounced, Adam. They’re coming after the collateral.”
My stomach tightened. Claire owned a small furniture repair business. Adam had told me he sometimes helped her with bookkeeping. Why would her bills have anything to do with our house?
He reached for the envelope, but Claire pulled it away. “I asked you whose name was on it. You swore she knew.”
I took the papers. Across the top was a lender’s notice addressed to me. Beneath it was a loan agreement for $186,000, secured by the house Adam and I owned together.
On the signature page, my name appeared in a careful imitation of my handwriting.
“I never signed this.”
Adam’s face went white. Claire stared at him, then at me.
Before either of them could speak, her phone rang. She read the screen and whispered, “It’s the lender. They say someone just submitted another document in your name.”
I thought Claire was the reason my marriage was ending. The papers in her hands suggested Adam had been hiding something far more dangerous, and the lender was still receiving documents with my name on them.
“Put it on speaker,” I said.
The lender’s representative identified herself as Dana from the fraud department. She would not discuss account details until she verified who I was. I gave my name and asked for a callback number, then called the number printed on my own mortgage statement instead. After being transferred to Dana, I learned a request to increase the credit line had been uploaded twenty minutes earlier.
Adam held out a hand. “This is a misunderstanding.”
Dana asked whether I had authorized the request. “No,” I said. “And I did not sign the original loan.”
She said she could flag the account, stop further draws while they reviewed it, and send me instructions for a written dispute. She could not promise what would happen to the debt or the lien. I wrote down her name and case number.
Claire slid down against the hallway wall. “He told me you both wanted to invest in my shop.”
“I never heard about a loan,” I said.
Her business had received $42,000 to buy equipment, she explained. She had signed paperwork believing Adam was funding the rest through a legitimate loan against his own share of our house. When her shop lost a major contract, she missed the payment she had agreed to make. The lender then sent her a notice showing the full amount owed.
Adam had already gone into the kitchen. I heard a drawer slam.
Claire opened an email on her phone. It showed a transfer from the loan proceeds to a company called Northline Consulting. The owner’s name was Adam’s.
The amount was $139,000.
“So where did the money go?” I asked him.
He came back holding my passport and a folder of tax returns. “Give me the envelope,” he said. “I can fix this before you ruin all of us.”
Claire stood. “You told me the rest went toward the house.”
Adam’s jaw tightened. “You signed for your part. Don’t act innocent.”
She played me a voicemail from that morning. His voice said, “If the bank asks, tell them she approved the increase. I have her ID right here.”
My passport was still in his hand.
I stepped toward the front door. Adam moved in front of it. For one terrible second, none of us spoke. Then Claire lifted her phone and said, “I’m calling 911 if you don’t move.”
He backed away, but his phone lit up on the counter. The notification was a confirmation from a title company: a document bearing my electronic signature had been received for a closing scheduled the next morning.
I looked at the packed boxes, then at the man between me and the door. The loan was only the first thing he had put in my name.
“Whose closing?” I asked.
Adam turned his phone facedown. Claire kept hers raised, one finger hovering over the emergency call button. He stared at the two of us, then stepped aside.
I carried my passport and the loan papers out to my car. Claire followed with her envelope. I locked the doors and called the title company using the number on its public website, not the number in Adam’s notification.
The receptionist connected me to the closing coordinator. I explained that I owned the house jointly, had not signed anything, and suspected my identity had been used. She would not send confidential documents to a stranger on the phone. She did confirm there was a closing scheduled for the property the next morning. At my request, she marked the file as disputed and said their attorney would review it before anything proceeded.
I emailed her a short written notice from my own account. I saved the sent message.
Inside the house, Adam knocked on the car window. “You’re making it sound criminal.”
I cracked it an inch. “Is my signature on another document?”
He looked away. That was answer enough.
Claire offered to follow me to a hotel. I called my sister in Denver instead. She stayed on the phone while I drove across town. Claire met me there with copies of her paperwork. Adam sent eleven texts before midnight, moving from apology to accusation to a promise that he could “make the lender whole.” I saved every one.
The next morning, a real estate attorney reviewed what I had. The scheduled closing was for a refinance that would pay off the disputed credit line and add another $58,000 to the mortgage. Adam had submitted an electronic consent form in my name, but the title company had paused the file after my call. No new loan had closed.
The attorney told me not to assume the original lien would vanish just because I disputed the signature. We would have to give the lender evidence and follow its investigation. She helped me send a formal fraud claim, notify our mortgage servicer, and request the complete loan file and signing records. I filed a police report, froze my credit with the three bureaus, and changed passwords on my accounts.
Claire sat beside me at the attorney’s office. She admitted she had ignored a warning sign: Adam had insisted on delivering documents himself whenever my name appeared. She thought he was protecting me from paperwork. Now she handed over her emails, transfer records, and the voicemail without asking for anything in return.
“I came last night because I thought you knew,” she said. “When I saw your face, I realized he’d lied to both of us.”
I believed her. We could start telling the truth.
Three days later, the lender sent the application file. The copy of my driver’s license was an old scan from our shared computer. The supposed signing had been completed remotely through an email address I did not recognize. Its recovery number was Adam’s. The notary listed on one page told the lender’s investigator she had never met me. Her name and commission number appeared on a certificate she said she had not issued.
That was when Adam stopped calling me and started calling Claire.
He told her that if she withdrew her statement, he would cover her missed payments and keep the shop open. She forwarded the messages to the investigator. Then she asked her own attorney what she owed on the portion she had actually received. She intended to account for the $42,000; she refused to take the blame for the forged signature or the money Adam had diverted.
The rest of the money had gone through Northline Consulting. Bank records obtained during the investigation showed transfers to Adam’s personal brokerage account and payments on credit cards he had kept separate from our household finances. He had described those charges to Claire as renovation costs. There had been no renovation.
When I finally spoke to Adam with attorneys present, he tried one last explanation. He said he had planned to put the money back after an investment paid off. He said he had been embarrassed to tell me the investment had failed. He said I should understand that Claire’s shop was struggling.
“You used my name to borrow money,” I said. “And you tried to borrow more after I told you I was leaving.”
He didn’t deny either part. He only said, “I thought I could fix it.”
I remembered our anniversary reservation, still in my calendar. For weeks, I had worried that asking him to keep it made me unreasonable. Sitting across from him, I understood how much energy I had spent arguing about Claire while he kept a second life in spreadsheets and signatures.
The lender completed its review over the following months. It agreed the documents bearing my signature were unauthorized, released the disputed lien against my interest in the house, and corrected its reporting to the credit bureaus. Its claims against Adam and the money he had taken continued separately. My attorney checked the recorded release before I trusted that the house was clear. The investigation also went to the county prosecutor; I was told any decision about charges would take longer.
The divorce took longer than I wanted, too. We sold the house after the title issue was cleared. Through our attorneys, we settled the division of what remained, with Adam responsible under our agreement for the debt tied to his transfers. The agreement could not erase every dispute a creditor might raise, so my attorney kept monitoring the accounts until the lender confirmed its corrections in writing.
Claire closed her shop that winter. She found a job restoring furniture for another business and arranged repayment of the money she had received. We exchanged occasional updates about the case. Neither of us pretended that night had been simple: she had called my husband during our anniversary, and I had resented her for it. But she had come back with the envelope when he wanted her to stay quiet.
In Denver, I started the hospital job. My sister helped me unpack, and I put my late mother’s framed photograph on the first shelf. My phone buzzed with a reminder of an anniversary I had forgotten to delete. I removed it, then opened a new calendar entry for the date I had signed my own lease.
For the first time in months, the signature at the bottom of a document was really mine.