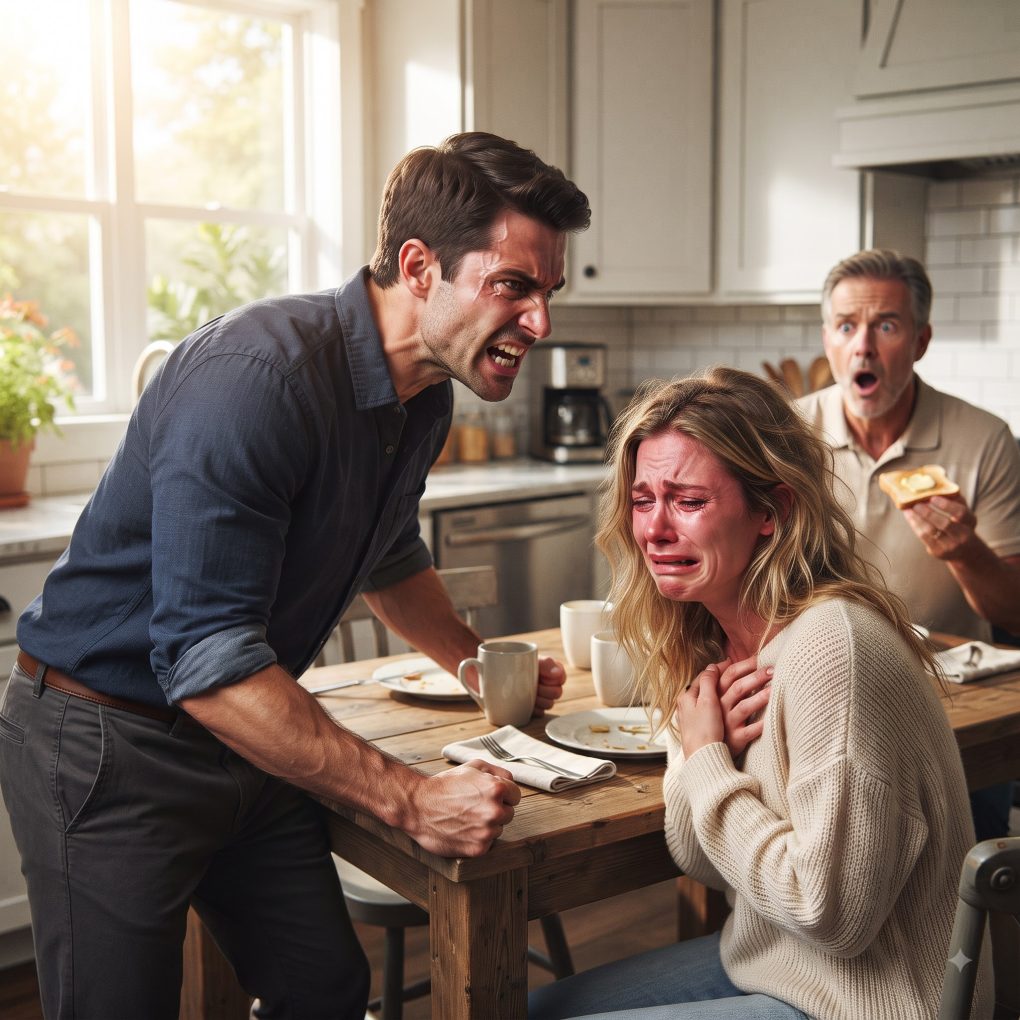
At breakfast, my sister hugged me and whispered, “Thank you for the house.” I nearly dropped my coffee. We were sitting in my parents’ kitchen outside Columbus, Ohio, and I had no idea what she meant. My mother smiled across the table like this was a birthday surprise. Then Dad calmly buttered his toast and said, “I already signed the $1.4 million purchase with your inheritance.” For a second, nobody moved. My sister Madison squeezed my shoulder. “I knew you’d understand. It’s perfect for the kids.” I looked at all three of them and realized they thought the decision had already been made.
My blood ran completely cold. Ten years ago, my maternal grandfather had left me a structured trust fund, specifically designated as my sole inheritance, managed under Dad’s legal guardianship until I turned thirty. I was twenty-eight. The trust was currently worth roughly $1.4 million, earmarked for my future, my independence, and the life I had worked tirelessly to build as a financial analyst in Chicago. I had taken out student loans for my undergraduate degree just to avoid touching the principal early, enduring frugal living and long work hours while my sister, Madison, lived a comfortable, subsidized lifestyle.
“What do you mean you signed it?” I asked, my voice barely above a whisper, staring directly at my father. “Dad, that money is in a locked trust account. You don’t have the legal authority to liquidate those funds for a property purchase.”
Dad set his butter knife down with a soft click, his posture remaining infuriatingly relaxed. “Ethan, you’re single. You make a solid income in Chicago, and you don’t even have a family yet. Madison has three young children and is living in a cramped two-bedroom rental. Her husband’s business took a hit last year. As head of this family, I made a executive decision to reallocate the family resources where they are needed most right now.”
“It’s not family resources!” I shouted, standing up so fast my chair scraped violently against the hardwood floor. “It is an explicit, legal bequest from Grandpa directly to me! It is legally mine!”
Madison’s joyful expression instantly crumbled into tears. “Ethan, how can you be so selfish? It’s a four-bedroom home in Powell with the best school district in the county! I thought you loved your niece and nephews!”
“Don’t manipulate me, Madison,” I snapped, turning on her. “You knew about this? You asked him to steal my entire net worth?”
My mother finally spoke up, her voice laced with sharp disappointment. “Watch your mouth, Ethan. Nobody stole anything. Your father is a co-trustee alongside the firm’s manager. He simply signed the authorization paperwork yesterday to release the funds to the escrow account for closing next month. Family supports family. You will get established eventually on your own merit, just like we raised you to do.”
I stared at the three faces across the table—people I had trusted my entire life—and realized I was completely isolated in my own family home. Dad had forged or bypassed the secondary trustee signature, using his position as my guardian to drain my entire future to buy his favorite child a luxury home. I picked up my phone, grabbed my car keys from the counter, and walked out the front door without saying another word, ignoring their calls as I started my engine.
I pulled into a vacant gas station parking lot two miles down the road, my hands shaking violently against the steering wheel. The reality of the situation hit me like a physical blow. A $1.4 million purchase contract had been executed using my trust as the funding guarantee. If the escrow cleared and the wire went through, my financial security would vanish instantly, transferred into a title deed under Madison’s name.
I immediately called my trust attorney in Chicago, Arthur Vance. When Arthur picked up, I laid out the situation as clearly as my panicked voice allowed: the unauthorized authorization, the signed purchase agreement, and my father’s abuse of his co-trustee power.
Arthur’s tone turned icy within seconds. “Ethan, listen to me very carefully. If your father signed a release order for trust assets without your explicit written consent as the primary beneficiary, or if he misidentified the primary purpose of the trust to the financial institution, he has committed a major fiduciary breach and potential fraud. But we need to act immediately before the escrow company processes the wire transfer.”
“What do I need to do?” I asked, my heart pounding in my chest.
“You need to drive back there, get a physical copy of whatever paperwork he signed, and find out which title company and bank are holding the escrow,” Arthur instructed firmly. “Then, you need to decide right now how far you are willing to go. Stopping this means freezing the accounts, filing an emergency injunction against your own father, and potentially reporting him to law enforcement. If you move forward, there is no going back to normal with your family.”
I closed my eyes, remembering Madison’s smug embrace, my mother’s cold guilt-tripping, and my father’s calm arrogance as he gave away my life’s safety net. They hadn’t just made a mistake; they had treated me as a bank account rather than a son and brother.
“Do it,” I said clearly. “Send me whatever legal notices I need.”
Ten minutes later, I walked back into my parents’ house. The atmosphere was thick with tension. They were sitting in the living room, whispering. When I entered, Dad stood up, assuming I had returned to apologize and fall in line.
“I’m glad you cooled off, Ethan,” Dad began, stepping forward. “We can discuss how Madison can pay you back a small portion over time—”
“Hand over the purchase agreement and the trust release authorization copy,” I interrupted, keeping my voice flat and completely devoid of emotion.
Dad’s eyes narrowed. “Excuse me?”
“I am the primary beneficiary of that trust,” I stated calmly. “If you do not hand over the copies of the documents you executed using my legal identity and inheritance within thirty seconds, my attorney will serve an emergency freezing injunction directly to your bank, the escrow company, and the local county court by noon.”
My mother gasped, and Dad’s face turned an angry, blotchy red. “You’re threatening your own father over money?”
“You stole my life savings, Dad,” I replied, staring him down. “You have ten seconds.”
Dad stood frozen for a few agonizing seconds, calculating whether I was bluffing. When he realized I was staring at him with cold determination, his posture broke. He walked over to his home office desk, retrieved a blue folder, and slammed it onto the coffee table.
I picked up the folder and scanned the contents. The documents revealed the full extent of the scheme. Dad had contacted the secondary trust manager at the local bank branch, claiming that the $1.4 million withdrawal was an “approved real estate investment venture” on my behalf. He had listed himself as the primary decision-maker and used a outdated power of attorney form from when I was a minor to bypass my signature. Madison and her husband were listed as the sole title owners of the Powell property, while my trust was listed as the sole funding source with no equity share or mortgage lien in my name. It wasn’t an investment; it was an outright, uncompensated transfer of wealth.
Without another word, I snapped high-resolution photos of every single page on my phone and emailed them directly to Arthur Vance. Then, I sat down in the armchair opposite my parents, while Madison stood in the doorway, watching in silence.
“Here is what happens now,” I said, looking at all three of them. “Arthur is currently transmitting an emergency Cease and Desist order along with a formal Notice of Fraudulent Trustee Activity to the bank’s legal department and the escrow company handling the Powell house closing. By 11:00 AM, the transaction will be completely frozen. No funds will leave the trust.”
“Ethan, please!” Madison cried out, rushing into the room. “We already put down a $50,000 earnest money deposit from our savings! If the closing falls through because of a legal freeze, we lose that deposit, and the sellers will sue us!”
“Then you should have thought about that before agreeing to use stolen money,” I answered coldly.
My father took a step toward me, his voice trembling with rage. “If you freeze that account and report this to the bank, you will destroy my professional reputation in this town! I am a respected businessman! They could strip my trustee rights entirely and file criminal civil charges against me for fiduciary misconduct!”
“You brought that on yourself the moment you signed my name to a contract to buy your daughter a mansion,” I replied. “You had a legal and moral duty as a fiduciary to protect my assets. Instead, you robbed me.”
At 10:45 AM, Dad’s phone rang. He answered it on speaker, his hands visibly shaking. It was the senior compliance officer from the bank’s trust department. The officer’s tone was formal and extremely severe. He informed my father that based on the emergency legal filings received from my attorney, the bank had flagged the transaction as unauthorized, frozen all trust disbursement requests, and initiated an internal fraud investigation into the power of attorney document used. Furthermore, the bank stated that my father was being immediately suspended from his role as co-trustee, pending a formal court review.
Dad sank into his chair, his face pale and drained of color. The reality of his illegal actions had finally caught up to him.
Over the next two weeks, the fallout was absolute. With the trust funds locked, Madison’s purchase contract failed. She lost her $50,000 earnest money deposit, and the sellers listed the Powell home back on the market. Furious at the humiliation and financial loss, Madison cut off all communication with me, accusing me of ruining her children’s future. My mother sent me several emotional text messages accusing me of destroying the family over material wealth, before eventually going silent as well.
Arthur Vance successfully filed a petition in court to permanently remove my father as a co-trustee, replacing him with an independent wealth management firm. The court also ordered my father to cover all legal fees incurred during the dispute. While I chose not to press formal criminal charges against my father to avoid prolonging the public court battle, the legal record of his fiduciary removal permanently severed our personal and financial relationship.
I packed the rest of my belongings from my childhood room that afternoon and drove back to Chicago. Standing in my apartment overlooking the city, I felt a deep, undeniable pain over losing my entire family in a single morning. But as I looked at my updated account statements—secure, untouched, and fully protected under my independent name—I knew I had made the right choice. I had not destroyed my family; their entitlement and betrayal had destroyed it long before I ever stood up for myself.