“She said it so calmly, like she had just bought a cup of coffee—until I realized our dream home was gone in a single transaction…”
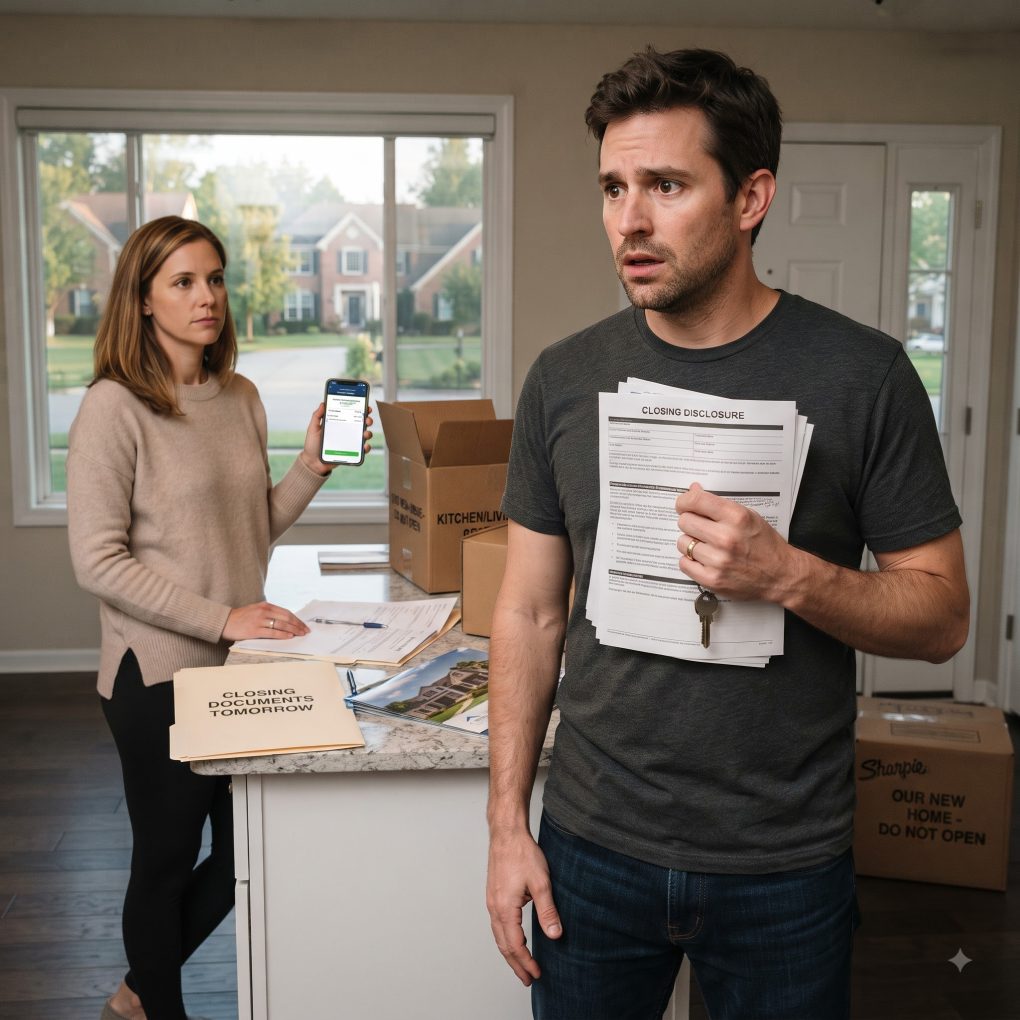
The day before we were supposed to close on our dream home, my wife looked me dead in the eye and said, “I wired the down payment to my brother. He needed it more than we need a house right now.”
She said it so casually, like she had just ordered takeout.
I stared at her. “You mean the $72,000 sitting in our joint account?”
She nodded.
“My brother’s business was about to collapse. He had to pay his suppliers today.”
“You sent him our house money?”
“He’ll pay us back.”
“When?”
She looked away.
That was when my stomach dropped.
I grabbed my phone and called the title company. Our closing was scheduled for 9 a.m. the next morning. The loan officer answered after two rings.
“Mr. Carter, I’m glad you called. We’ve been trying to reach you.”
“Why?”
“There’s an issue with the down payment. We haven’t received the required funds.”
“I know.”
Silence.
Then she asked carefully, “Did you authorize a change to the source of your funds?”
“No.”
My wife suddenly stepped between me and the phone.
“Evan, stop.”
I ended the call.
“What aren’t you telling me?”
She folded her arms. “Nothing. I told you. Mark needed help.”
“Then why did the title company ask whether I authorized a change?”
She didn’t answer.
I opened our banking app.
The $72,000 transfer wasn’t the only transaction.
There were three withdrawals.
$18,000.
$9,500.
And another $7,200.
All sent to accounts I didn’t recognize.
My wife went pale.
I turned the screen toward her.
“What are these?”
She whispered, “Those aren’t mine.”
Then my phone buzzed.
It was an email from our lender.
URGENT: DOCUMENT DISCREPANCY REQUIRES IMMEDIATE RESPONSE.
I opened the attachment.
My blood ran cold.
Someone had submitted a document to the bank claiming I had agreed to use our home’s down payment to cover my brother-in-law’s debts.
And at the bottom was a signature that looked exactly like mine.
Except I had never signed it.
Teaser
I thought my wife had simply made one terrible decision to help her brother. But the bank document changed everything. Someone had been planning this long before the money disappeared—and the next discovery made me realize our dream house might never have been the real target.
I stared at the forged signature until the words on the screen blurred.
“That isn’t mine.”
My wife didn’t answer.
“Sarah.”
She finally whispered, “I know.”
“You know?”
She sat down.
“I found out yesterday.”
My chest tightened. “You found out yesterday and still sent Mark the money?”
“I thought I could fix it.”
“Fix what?”
She rubbed her face. “Mark told me he owed money to three vendors. He said if he didn’t pay them, they’d shut down his business. He promised the transfer was temporary.”
“And the other withdrawals?”
Her eyes filled with tears.
“I didn’t make those.”
I called the bank immediately. A fraud specialist reviewed the transactions and told us something even worse.
The $18,000 and $9,500 transfers had been initiated from our home computer.
Our home computer.
I looked at Sarah.
“Who used it?”
She hesitated.
“Mark came over last weekend.”
My blood went cold.
Before I could respond, another email arrived.
This time from the mortgage lender.
They had received a revised financial statement showing that Sarah had supposedly agreed to remove herself from the mortgage application and transfer ownership of the property to me alone.
I never requested that either.
The lender wanted us in the office immediately.
We drove there in silence.
The loan officer placed a folder on the table.
“This was submitted two weeks ago,” she said.
Inside were copies of bank statements, a signed authorization, and a letter supposedly written by Sarah.
The letter claimed I was “financially irresponsible” and that she intended to protect her personal assets by removing herself from the purchase.
Sarah started shaking her head.
“I never wrote that.”
The loan officer looked at me.
“There’s more.”
She pulled out a second document.
It was a preliminary deed.
The buyer listed on it wasn’t me and Sarah.
It was Mark Carter.
My wife covered her mouth.
“No…”
The loan officer lowered her voice.
“Someone attempted to restructure the entire purchase so your brother could acquire the property.”
Suddenly, everything made sense.
The missing money wasn’t just helping Mark.
It was part of a larger plan.
Then my phone rang.
It was Mark.
I answered on speaker.
His voice sounded strangely calm.
“Evan, we need to talk.”
I said nothing.
He sighed.
“About the house.”
Sarah stared at me.
Then Mark said the one sentence that made both of us freeze.
“You really should’ve asked Sarah why she gave me access to your closing documents.”
Nobody spoke for several seconds.
I looked at Sarah.
She looked like someone had pulled the floor out from under her.
“Sarah,” I said quietly, “what does he mean?”
She swallowed hard.
“I gave him access.”
My heart sank.
“Why?”
“Because he said he needed the paperwork to prove the money came from our family. He told me the bank was threatening to freeze his business accounts.”
“And you believed him?”
“Yes.”
She started crying.
“I thought I was helping my brother.”
Mark was still on speaker.
“Stop making this sound worse than it is.”
I grabbed the phone.
“You forged my signature.”
“No, I didn’t.”
“You submitted documents claiming I agreed to change ownership.”
“I didn’t submit anything.”
“Then who did?”
Silence.
That silence told me more than his words could have.
The lender was still sitting across from us, watching carefully.
She pointed toward the phone.
“Mr. Carter, keep this call active. Our fraud department has already opened an investigation.”
Mark suddenly became defensive.
“You’re making a huge mistake. I can explain everything.”
“Then explain why your name appears on the deed.”
Another pause.
“I was trying to protect the property.”
“By taking it?”
“That’s not what happened.”
I looked at Sarah.
She whispered, “Mark told me there was a way to keep the house if our financing fell through.”
The lender leaned forward.
“What exactly did he tell you?”
Sarah wiped her eyes.
“He said if Evan’s credit caused a problem, Mark could temporarily take over the purchase. He said we could transfer it back later.”
The lender shook her head.
“That is not how this works.”
I felt sick.
For weeks, Sarah and I had talked about that house as our future. We had chosen where the couch would go, argued about paint colors, and planned a small backyard garden.
And while I was imagining our first night there, someone had been preparing paperwork to take it from us.
But there was still one question.
“Where did the $72,000 go?”
Sarah looked at the floor.
“Mark said he needed $72,000 to settle his business debts.”
The fraud specialist had already traced part of the money.
It hadn’t gone to suppliers.
It had gone to an account belonging to a company registered six months earlier.
The company’s only listed manager was Mark.
That was the twist that finally broke Sarah.
“He lied to me.”
I nodded.
“He used you to move our money.”
But the investigation wasn’t finished.
The bank discovered that someone had also accessed our online mortgage portal using Sarah’s credentials.
Sarah immediately admitted something else.
She had given Mark her password.
“I thought he was helping me,” she whispered.
That decision could have destroyed our closing.
But it also gave investigators a trail.
The mortgage company preserved the login records. The bank froze the remaining funds. The title company stopped the attempted transfer.
And then something unexpected happened.
Mark called again.
This time he wasn’t angry.
He was scared.
“Evan,” he said, “I can pay some of it back.”
I laughed bitterly.
“Some?”
“I can get the money.”
“Where?”
He hesitated.
Sarah suddenly stood.
“Mark, tell the truth.”
He said nothing.
Then she asked, “Did you ever intend to give us the money back?”
Silence.
That was the answer.
The fraud investigation eventually uncovered that Mark had been struggling with serious business debt for months. He had borrowed money from several people, used one payment to cover another, and was desperately trying to keep creditors from shutting him down.
The house had become his escape plan.
He believed that if he could redirect our down payment, manipulate the mortgage paperwork, and get the property placed under his name, he could use the house as collateral.
Sarah had unknowingly supplied the information he needed.
But the forged documents crossed a line neither of them could erase.
Our attorney advised us not to contact Mark directly anymore.
The bank recovered a portion of the transferred money from the accounts before it could be moved again. The rest became part of the legal dispute.
Our closing was postponed.
Then postponed again.
For almost two months, the house sat in limbo.
I expected Sarah to defend her brother.
Instead, she finally told our attorney everything.
Every password.
Every document.
Every conversation.
She admitted she had ignored warning signs because she wanted to believe Mark was still the brother she remembered.
Eventually, the title company cleared the property.
The seller agreed to extend the contract.
And one Friday morning, we finally sat at the closing table.
This time, the money was verified.
The documents were reviewed line by line.
Nobody else had access to our accounts.
When I signed the final papers, my hand trembled.
Not because I was excited.
Because I remembered how close we had come to losing everything.
Afterward, Sarah and I stood outside the house.
She looked at the front door.
“I’m sorry.”
I didn’t answer immediately.
“I know you were trying to help him,” I said. “But you made decisions that affected both of us without telling me.”
“I know.”
“And trust doesn’t come back because someone says sorry.”
She nodded.
“I know that too.”
We moved into the house several weeks later.
There was no huge celebration.
No champagne.
Just two exhausted people carrying boxes through the front door.
The first thing we did was change every password.
Then we separated our finances.
Not because we hated each other.
Because rebuilding trust meant creating boundaries neither of us could ignore again.
Sarah also stopped communicating with Mark while the legal case continued.
Months later, she received a letter from his attorney.
His business had collapsed.
Several creditors were pursuing him.
The attempted property transfer had become part of the legal record.
But the house was ours.
One evening, Sarah and I sat on the back steps.
She looked at the empty garden space and smiled sadly.
“Remember when we argued about whether to plant tomatoes or peppers?”
I smiled.
“Yeah.”
“We almost lost this place before we even owned it.”
I looked toward the house.
“No. We almost lost more than the house.”
She knew exactly what I meant.
The money could be recovered.
The documents could be corrected.
The closing could be postponed.
But trust was different.
It couldn’t simply be wired back into an account.
A year later, we finally planted the garden.
Tomatoes on one side.
Peppers on the other.
And every time I walked past our little garden, I remembered the lesson that nearly cost us our home:
Helping family isn’t wrong.
But helping someone should never require hiding the truth from the person standing beside you.
Our dream house had almost become Mark’s escape route.
Instead, it became the place where Sarah and I learned that love without honesty wasn’t enough—and that rebuilding something broken required more than simply getting the money back.