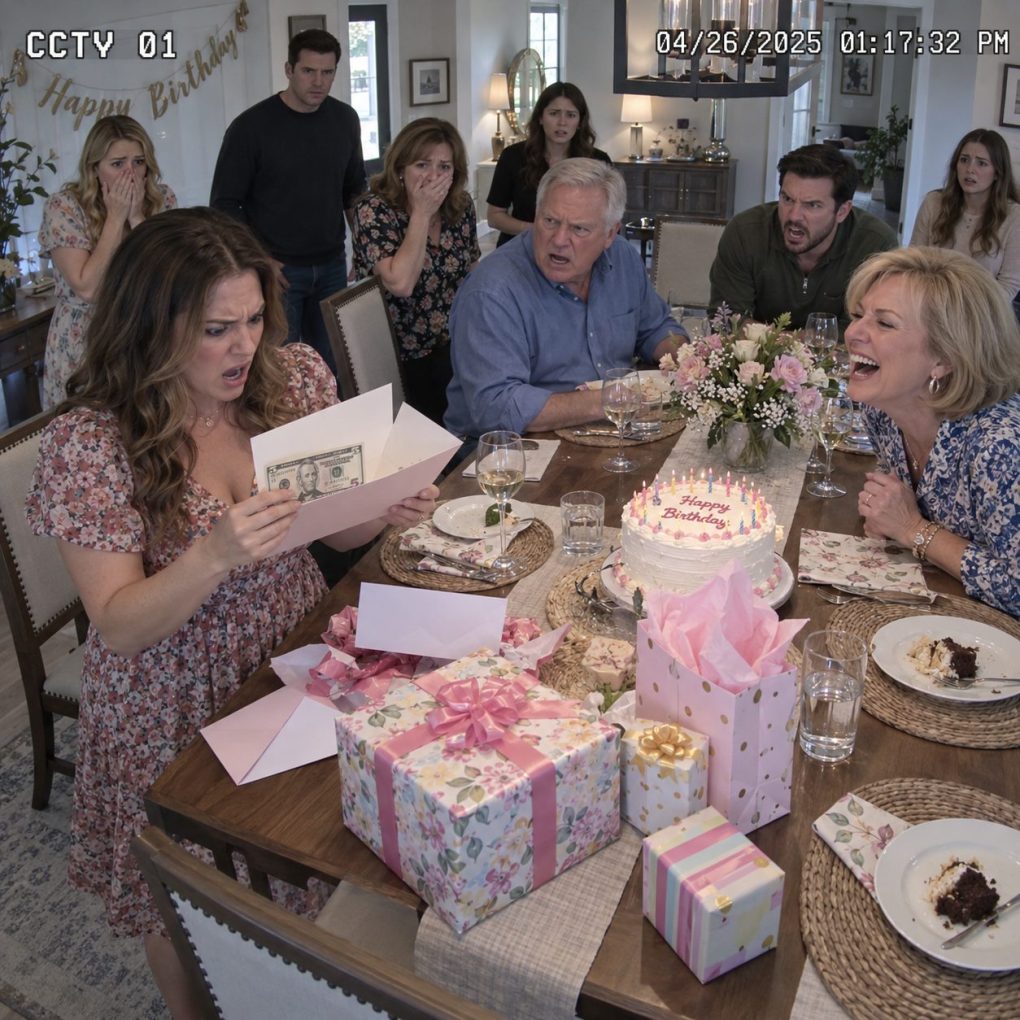
“Five dollars should be plenty for you,” my mother joked as the whole table burst out laughing. I stared at the bill inside my birthday card and said nothing. They mistook my silence for humiliation. In reality, I was calculating exactly how much their little joke was about to cost them.
My name is Natalie Price, and I turned thirty-four in my parents’ dining room outside Cleveland, Ohio.
I had not wanted a party.
My mother insisted.
“You work too much,” she said. “Let us do something nice for you.”
So I showed up after a twelve-hour day, still wearing office clothes, carrying a bakery cake I had bought myself because Mom had “forgotten dessert.”
My brother Ryan was there with his wife, Brooke. My sister Ashley had brought her boyfriend. Dad sat at the head of the table.
Everything looked normal until the cards came out.
Ryan handed me a gift certificate.
Ashley gave me a scarf.
Then Mom passed me a white envelope.
Inside was a five-dollar bill.
I looked up.
She smiled.
“Five dollars should be plenty for you.”
Everyone laughed.
Dad added, “Natalie’s too independent to need anything anyway.”
That word again.
Independent.
It was the family explanation for why I always paid.
For six years, I had covered my parents’ property taxes when Dad’s business slowed down.
I paid Ryan’s health-insurance premiums after he lost his job.
I covered Ashley’s car payment twice.
I financed the roof repair on my parents’ house.
Nobody called those things gifts.
They called them “helping family.”
Last month alone, I had transferred $3,200 into Mom and Dad’s household account.
They had no idea I kept records.
Every payment.
Every loan.
Every promise to repay me.
Mom watched me fold the five-dollar bill.
“Aren’t you going to say thank you?”
I smiled.
“Thank you.”
They laughed again.
Then Ryan raised his glass.
“To Natalie. The family bank.”
That one landed differently.
Because three days earlier, my accountant had warned me that the “temporary” support I had been giving everyone was draining money I needed for a business acquisition.
I had been planning to reduce it gradually.
Now I changed my mind.
I excused myself, walked into the hallway, and sent three messages.
One to my accountant.
One to my attorney.
One to the bank.
Cancel every voluntary transfer.
Separate every recurring payment.
No new loans.
No exceptions.
Then I returned to the table.
Mom was cutting the cake I had paid for.
Dad asked why I looked so calm.
I opened the card again and placed the five-dollar bill beside my plate.
“Just thinking about budgets.”
They laughed one more time.
By the next afternoon, Mom was no longer laughing.
She called me six times before leaving a voicemail.
“Natalie, what happened to the mortgage payment?”
That was only the first bill.
I did not answer immediately. I waited until my accountant, Sarah Mitchell, finished separating every automatic payment attached to my accounts. The numbers were worse than I expected. Over six years, I had transferred just over $186,000 to my parents and siblings combined. Some of it was documented as loans. Most of it was informal support I had never pushed them to repay.
The mortgage payment Mom mentioned was actually the monthly payment on a home-equity loan Dad had taken out after his landscaping business failed. I had been covering it for eighteen months because he told me foreclosure was a possibility. I was not legally responsible for the debt. I had simply stepped in.
Ryan called next. His insurance premium had bounced because I had stopped the transfer to the account he used for household bills. “What are you doing?” he demanded. I asked him the same question I should have asked years earlier. “Why is your family’s insurance still my responsibility?”
He went quiet.
Ashley was angrier. She accused me of punishing everyone over a birthday joke. I told her the joke had not created the problem. It had clarified it. They had spent years treating my money as communal while treating me as the one person who needed nothing in return.
Mom finally reached me that evening. She cried before she became angry. “Your father is going to lose the house.” I reminded her that Dad had received a retirement payout two years earlier. She admitted most of it had gone toward Ryan’s failed gym investment and Ashley’s graduate-school debt.
I had not known that.
That was when I understood how deep the pattern went. My parents were not merely depending on me. They had been using my support to protect everyone else from consequences.
My attorney, Daniel Cole, reviewed the loans I had made over the years. Three were documented with signed repayment agreements: $28,000 to Ryan for the gym, $19,500 to Ashley for tuition and car debt, and $46,000 to my parents for the roof and home-equity payments.
Nobody had made a single scheduled repayment.
Daniel asked whether I wanted to sue.
I said no.
Not yet.
I did something simpler.
I sent each of them a written repayment schedule and told them I would no longer provide additional money until the existing debts were addressed.
That created chaos.
Ryan came to my office without an appointment. He called the repayment plan “cold.” I asked whether signing the loan agreement had felt cold when he needed the money.
He stared at me.
Then he said, “You can afford it.”
That sentence ended the conversation.
I could afford many things.
That did not make anyone entitled to them.
Three days later, Dad asked me to come over. For once, he had spreadsheets on the table instead of excuses. Without my monthly support, my parents had a shortfall of nearly $2,700.
I showed them where the money had been going.
Restaurant spending.
A premium cable package.
Two storage units.
A country-club membership Dad claimed he needed for networking.
Mom looked embarrassed.
Then I pointed to the largest line.
Monthly transfers to Ryan.
$900.
She whispered, “He has children.”
“So do millions of adults who pay their own bills.”
Dad rubbed his forehead.
For the first time, nobody called me selfish.
They just looked scared.
Then Mom said something I will never forget.
“We thought because you earned more, it didn’t hurt you.”
I looked at her.
“It did hurt me. You just never asked.”
The room went silent.
And that was the first time my family understood the five-dollar joke was not what cost them.
Years of entitlement had.
The next six months were uncomfortable for everyone. My parents canceled the country-club membership, sold one storage unit’s contents, and refinanced the home-equity loan under terms they could actually manage. Dad took seasonal consulting work with another landscaping company. Mom began tracking expenses for the first time in years.
Ryan struggled more.
His gym had failed because he expanded too quickly and assumed family money would cover the gaps. Once I stopped helping, he sold his expensive truck, moved into a smaller rental, and picked up work managing another fitness center.
Ashley paused graduate school for one semester and worked full-time.
Nobody became homeless.
Nobody’s life ended.
They simply had to live inside the budgets they had been avoiding.
The repayment plans started small.
My parents sent $400 the first month.
Ryan sent $150.
Ashley sent $100.
Those amounts mattered less than the fact that they finally sent something.
Then something unexpected happened.
My business acquisition went through.
I had been saving to buy a minority stake in the consulting firm where I had worked for seven years. The money I stopped funneling into family emergencies became part of my investment reserve.
A year later, I became a partner.
Mom found out from LinkedIn.
She called me and said, “You never told us.”
I answered honestly.
“For a long time, every financial conversation with the family turned into what someone needed from me. I wanted one thing that was mine before anyone calculated how it could help them.”
She was quiet.
Then she said, “I understand.”
That meant more than any birthday gift could have.
Our relationships changed slowly.
Not perfectly.
Ryan still made jokes sometimes, but he stopped joking about my money.
Ashley became the first person to repay her loan in full.
When she sent the final payment, she included a note: I’m sorry I treated your help like it didn’t cost you anything.
I kept that note.
Dad took longer.
He had spent most of his life believing providing for family meant solving every problem before anyone felt consequences. Once his own business failed, he transferred that expectation onto me without admitting it.
Two years after the birthday dinner, he invited me to breakfast alone.
He placed an envelope beside my coffee.
Inside was a check.
Not for the full amount.
But enough to matter.
“I should’ve paid you back before I let your mother put five dollars in that card,” he said.
I smiled.
“The five dollars wasn’t the problem.”
“I know.”
He finally did.
Mom apologized too.
Her apology was not dramatic. She said, “I thought teasing you was safe because you were the strong one.”
That sentence explained more than she realized.
Families often make the strongest person carry the heaviest load because they assume strength means endless capacity.
It doesn’t.
Strength does not mean unlimited money.
Unlimited patience.
Unlimited forgiveness.
Or unlimited responsibility for everyone else’s choices.
On my thirty-seventh birthday, my family came to my house.
No elaborate gifts.
No jokes.
Ryan brought homemade bread.
Ashley brought flowers.
My parents gave me a card.
Inside was a five-dollar bill.
For one second, my stomach tightened.
Then I saw what Dad had written beneath it.
This time, it’s just five dollars. Nothing attached.
I laughed.
Really laughed.
Then Mom handed me another envelope.
Inside was a receipt showing the final payment on the last debt they owed me.
That birthday felt different.
Not because they finally gave me more.
Because nobody expected me to give anything.
That was the lesson the original five-dollar joke taught us.
Generosity becomes unhealthy when gratitude disappears and expectation takes its place.
Helping people you love is good.
Financing their refusal to change is not.
And sometimes the kindest boundary is the one that finally forces everyone—including you—to learn the difference.