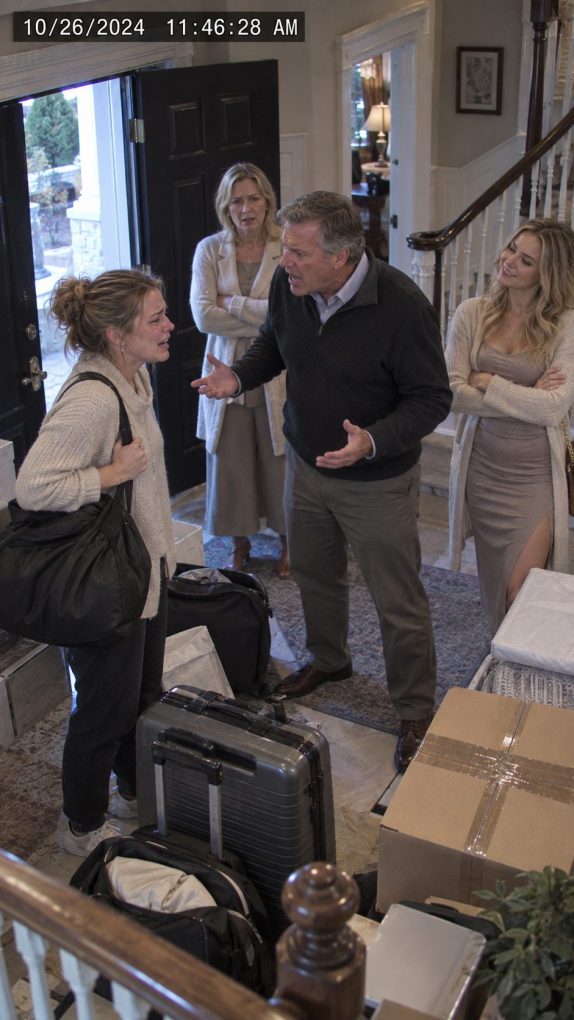
My sister was smiling when Dad told me to leave the house I had spent eighteen months keeping afloat. I was standing in the kitchen with a grocery receipt in one hand and the mortgage statement in the other when he said, “Pack tonight, Megan. Your sister needs the downstairs room more than you do.”
Eighteen months earlier, Dad had lost most of his income after the machine shop where he worked outside Columbus, Ohio, closed. Mom had died years before, and his mortgage was already three payments behind. I moved home, paid the arrears, covered utilities, groceries, insurance, and transferred $1,450 toward the mortgage every month.
My younger sister, Ashley, contributed nothing. She arrived that afternoon with six suitcases after breaking up with her boyfriend. Within an hour, she decided she wanted my room because it had a private bathroom.
I laughed because I thought she was joking.
Dad didn’t laugh.
He said Ashley was going through a difficult period and needed family support. When I reminded him that I was the reason the house hadn’t gone into foreclosure, Ashley leaned against the counter and said, “Nobody forced you to play hero.”
I asked Dad about the $31,000 I had put into the house.
His answer stunned me.
“You were living here. Consider it rent.”
Then Ashley smiled.
Dad told me not to expect reimbursement because my name wasn’t on the deed. Something inside me went completely quiet. I packed my clothes, laptop, documents, and a few belongings that night.
Before leaving, I opened my banking app.
The mortgage payment, electric bill, gas bill, homeowners insurance contribution, internet, and grocery transfer were all scheduled from my personal account.
I canceled every future automatic payment.
I didn’t cancel anything already owed or reverse previous payments. I simply stopped volunteering to pay bills for a house I had just been ordered to leave.
Dad watched me load my car.
He never asked where I would sleep.
Seven days later, my phone rang at 6:13 a.m.
Dad was crying so hard I barely recognized his voice.
“Megan, please come back.”
I sat upright in my friend’s guest room.
“What happened?”
His next words made my stomach drop.
“The bank says if I don’t fix this immediately, we could lose everything.”
I drove to Dad’s house that afternoon, but I didn’t bring my suitcases. Ashley’s car was gone. Dad sat at the kitchen table surrounded by envelopes, loan statements, and printed emails.
The situation was worse than one missed payment.
For months, Dad had been hiding financial problems from me. My $1,450 transfers covered the regular mortgage, but he had also taken out a home equity line two years earlier.
I knew nothing about it.
The balance was almost $46,000.
Dad had used part of the money after losing his job. But nearly $19,000 had gone to Ashley over the previous year for rent, car payments, credit cards, and what Dad called “emergencies.”
I stared at him.
While I was paying his mortgage, he had been borrowing against the house to support my sister.
Then came the immediate crisis.
The home equity loan required minimum monthly payments from Dad’s checking account. He had fallen behind. A temporary hardship arrangement had expired, and the lender was demanding that he cure the delinquency.
The house wasn’t disappearing that afternoon, as Dad’s terrified phone call suggested, but the situation was serious.
“Why didn’t you tell me?”
Dad looked ashamed.
“Because you were already doing enough.”
That answer almost made me laugh.
Ashley returned an hour later carrying shopping bags.
When she saw me, she immediately asked whether I had restarted the mortgage transfer.
“No.”
Her expression changed.
She said I was deliberately putting Dad’s home at risk because my feelings were hurt.
I placed the loan statements in front of her.
“You received nineteen thousand dollars from this house.”
Ashley looked at Dad.
He had never told her where the money came from.
For the first time, she stopped talking.
Dad asked whether I could cover the delinquent amount and resume the household bills until he found work.
I could have.
I had savings.
But I finally understood that rescuing him again would only continue the same arrangement.
I told Dad I would help him organize the paperwork, contact the lender, and meet with a housing counselor.
I would not write another check.
Ashley called me selfish.
Dad didn’t.
He stared at the statements for a long time.
Then he whispered, “If you don’t pay it, I may have to sell.”
“Yes,” I said.
And for the first time in eighteen months, Dad understood that his house was his financial responsibility, not mine.
The next month was painful but practical. A nonprofit housing counselor helped Dad review his options, and the lender agreed to discuss a repayment arrangement while he listed the property.
Dad finally accepted that keeping the house no longer made financial sense.
It sold four months later.
After the mortgage, home equity balance, closing costs, and other expenses were paid, Dad walked away with far less money than he had imagined.
But he walked away without losing everything.
He rented a small two-bedroom apartment near his new job at an auto-parts warehouse.
Ashley assumed the second bedroom belonged to her.
Dad surprised both of us.
He told her she could stay for sixty days while finding work, but after that she would either contribute rent or move elsewhere.
She accused me of changing him.
Dad corrected her.
“Megan didn’t change me. The bank did.”
I almost smiled.
Ashley eventually found a receptionist job and moved into an apartment with a roommate. Dad stopped paying her car payment.
Our relationship remained complicated.
Dad apologized for calling my contributions rent after accepting more than $31,000 from me. He offered to repay me gradually from what remained after the house sale.
I refused to pretend all of it had been a loan. Some of that money had paid for housing I also used, groceries I ate, and utilities I consumed.
But we reviewed my records together and identified $18,600 that I had specifically transferred to cure his mortgage arrears and prevent foreclosure.
Dad signed a repayment agreement.
He sends me $300 every month.
Sometimes I think about that morning when he called shaking, convinced the bank was about to take everything.
For eighteen months, I believed helping family meant preventing them from feeling the consequences of bad decisions.
I don’t believe that anymore.
Dad didn’t need me to move back into the house.
He needed to understand the numbers.
Ashley didn’t need another rescue.
She needed a deadline.
And I didn’t need repayment badly enough to destroy myself chasing it.
What I needed was the lesson I should have learned when Dad ordered me out.
Supporting someone financially does not guarantee they will respect you.
But walking away from disrespect does not mean you have to stop caring.
Sometimes the healthiest help you can offer is information, boundaries, and an empty checkbook.