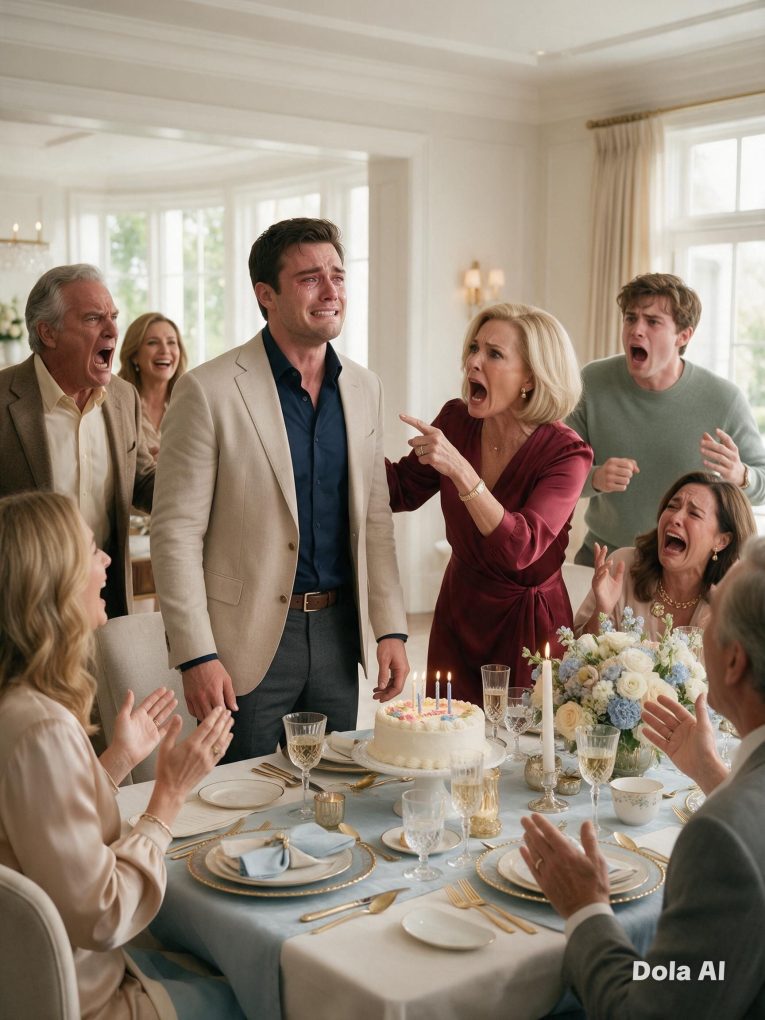
On my thirtieth birthday, my mother, Linda Mercer, waited until everyone had a plate of cake before she decided to make me the evening’s entertainment.
“You’ve been leeching off this family for thirty years,” she said, raising her wineglass. “So how are you going to pay it all back?”
My father, Gary, laughed first. Then my younger brother, Evan. My aunt Denise covered her mouth, pretending she was shocked while laughing harder than anyone. Even my cousin Melissa snorted into her drink.
I sat at the dining table in the house where I had spent most of my adult life fixing broken pipes, replacing appliances, covering property taxes, and quietly paying bills nobody else seemed to notice.
I didn’t argue.
I looked at my mother and asked one question.
“Do you want me to stop paying for everything that has my name on it?”
The laughter faded for half a second.
Mom rolled her eyes. “Oh, please. Don’t be dramatic.”
“Okay,” I said.
Then I stood, picked up my coat, and walked out.
Nobody followed me.
For six years, I had been the family’s invisible financial safety net. After Dad’s contracting business collapsed, I refinanced the house to stop foreclosure. The bank would only approve the loan if I became co-borrower and went on title. Later, when Mom’s credit cards were maxed out, I used my savings to catch up the mortgage, paid the homeowners insurance, and put the electricity and internet in my name because both of my parents had damaged credit.
They still called it “their house.”
They still told relatives I was living there rent-free.
What they never mentioned was that the mortgage payment came out of my account on the first of every month.
The morning after my birthday, I opened a new checking account, moved my direct deposit, canceled every automatic payment that wasn’t legally mine to maintain, and called the mortgage servicer.
I didn’t stop paying the mortgage. I wasn’t stupid enough to wreck my own credit.
Instead, I asked for a full loan review, a copy of the deed, payment history, and information about forcing a sale or refinancing my share.
Then I contacted a real-estate attorney.
Twelve days later, the bank called my parents.
Two days after that, my mother texted me.
Why did the bank call us?
Then another message appeared.
They said something about ownership.
A minute later:
Please come home.
I stared at the screen in my apartment, surrounded by boxes I had not bothered to unpack.
For the first time in years, they were afraid of losing something they thought I would always protect.
And this time, silence was doing what years of explanations never had.
I didn’t go home that night.
Instead, I called my attorney, Rachel Kim, the next morning and forwarded her screenshots of every text Mom had sent. Rachel had already warned me not to discuss the house alone with my parents, especially now that the bank had confirmed what I had spent years trying not to think about: I owned forty percent of the property.
The refinancing had happened when I was twenty-four. Dad’s business had been underwater, and the original mortgage was three months behind. Because my income from an engineering firm in Columbus was stable, the lender approved the new loan only after I joined the note and deed. My parents kept sixty percent between them. I received forty percent because I contributed the cash required to cure the arrears and closing costs.
At the time, Dad had gripped my shoulder and said, “We’ll make this right when we’re back on our feet.”
They never did.
The bank had called because Rachel sent a formal request asking whether the loan could be assumed or refinanced if I sought a partition sale. The servicer contacted all borrowers, including my parents, to confirm contact information and discuss the account.
To Mom, that phone call sounded like an eviction notice.
By noon, Dad called seven times.
Evan texted next.
Mom is freaking out. Whatever you’re doing, stop.
I typed three responses and deleted all of them.
At six, Rachel called me.
“Your mother contacted the bank and told them you had no ownership interest,” she said.
I laughed once, without humor. “Of course she did.”
“They pulled the deed.”
“And?”
“And now she knows lying doesn’t change county records.”
Rachel explained that my parents could refinance and buy out my share if they qualified. They could also agree to sell the house and divide the net proceeds according to ownership. If they refused both options, I could ask a court to order a partition.
I didn’t want revenge. I wanted separation.
For years, I had convinced myself that paying was easier than fighting. Every utility bill I covered prevented an argument. Every mortgage payment bought another month of peace. Every emergency repair made me useful enough that maybe, eventually, someone would admit I wasn’t a burden.
My thirtieth birthday had finally shown me how ridiculous that hope was.
Three days later, I agreed to meet my parents at Rachel’s office.
Mom arrived carrying a folder as if she were coming to prove I had committed fraud. Dad looked exhausted. Evan came too, although nobody had invited him.
The first thing Mom said was, “You’re really going to throw your parents into the street over a joke?”
Rachel gestured toward the chairs. “Mrs. Mercer, nobody is being thrown anywhere. We’re here to discuss ownership and repayment.”
“Repayment?” Mom snapped. “He lived with us for years.”
I opened my own folder.
Inside were six years of mortgage statements, tax receipts, insurance payments, utility records, contractor invoices, and bank transfers.
I slid one page across the table.
“This is what I paid after the refinance.”
Dad stared at the total.
Mom didn’t.
She pushed it back.
“That doesn’t count rent.”
So I placed another page beside it.
It showed fair-market rent for one bedroom in our neighborhood, multiplied by the exact months I had lived there.
Even after subtracting that amount, my documented contribution was more than $118,000.
Evan stopped leaning back in his chair.
Dad finally looked at me.
“Why didn’t you ever tell us it was that much?”
I held his gaze.
“I did. You just called it helping.”
Mom stood so quickly her chair scraped the floor.
“This family does not keep score.”
Rachel looked at the spreadsheets, then at her.
“Apparently only when the score favors you.”
For once, my mother had nothing to say.
Rachel gave everyone ten minutes to cool down.
My mother spent eight of them in the hallway making angry phone calls. I could hear enough through the office door to know she was calling Aunt Denise. The same aunt who had laughed at my birthday dinner was apparently now being told that I was trying to steal my parents’ house.
Dad stayed in the conference room.
He kept looking at the payment summary.
Finally, he said, “I knew you helped. I didn’t know all of this.”
I felt something inside me harden.
“You signed the refinance papers, Dad.”
“I know.”
“You watched me pay the mortgage.”
“I know.”
“You asked me for the property-tax money two years ago because you said you were short.”
He rubbed both hands over his face.
“I know.”
That was the problem.
He knew.
Maybe not every dollar. Maybe not every date. But he had known enough to understand that the story they told everyone—that their thirty-year-old son lived at home and contributed almost nothing—was false.
Evan stared at the table.
I turned to him. “Did you know the mortgage was in my name too?”
He shook his head.
“Did you know I paid it?”
“Mom said you gave them some money because you didn’t pay rent.”
I nodded. “That’s what she told everybody.”
The conference-room door opened.
Mom walked back in with her chin raised.
“I spoke to Denise,” she announced. “She thinks this is disgusting.”
Rachel didn’t even look up from her notes. “Your sister is not a party to the deed.”
Mom ignored her and pointed at me.
“You embarrassed us.”
I almost smiled at the absurdity.
“You announced to a room full of people that I had been leeching off you for thirty years.”
“That was a joke.”
“Then why is it embarrassing for them to learn what I actually paid?”
Her mouth opened, then closed.
Rachel moved the conversation forward. She laid out three options. My parents could refinance the mortgage, remove me from the loan, and buy out my forty-percent ownership interest. We could jointly list the property for sale and split the net proceeds according to title after settling agreed expenses. Or, if they refused to cooperate, I could file a partition action.
Mom rejected all three.
“This is our home.”
“It is also Daniel’s property,” Rachel said.
That was the first time anyone in my family had said those words out loud.
My property.
Not my parents’ house that I happened to sleep in.
Not their mortgage that I happened to pay.
Property I legally owned because six years earlier, when everything was collapsing, I had stepped in.
Dad asked for a week.
Rachel looked at me.
I agreed.
That week changed the family faster than any argument ever had.
Mom began calling relatives before I could speak to them. Her version was dramatic: I had secretly put my name on the house, waited years, then threatened to sell it on my birthday because she teased me.
Fortunately, deeds are boring things.
They are also public records.
Aunt Denise called me on Tuesday afternoon with the stiff tone of someone preparing to lecture me.
“Daniel, your mother says—”
“Before you say anything,” I interrupted, “I’m emailing you the deed, the refinance settlement statement, and six years of mortgage payments.”
She went quiet.
“You don’t need to believe me,” I continued. “Just read them.”
She called back forty minutes later.
Her voice had changed.
“I didn’t know.”
“Neither did most people.”
“She always said you barely paid anything.”
“I know.”
Denise apologized for laughing at the party. I accepted the apology, but I didn’t comfort her. I was tired of making other people feel better about what they had done to me.
Then something unexpected happened.
Evan came to my apartment.
I nearly didn’t let him in.
He stood outside holding a cardboard box filled with mail.
“What is this?”
“Stuff that came for you.”
I took the box.
He didn’t leave.
Finally, he said, “Can I come in?”
I stepped aside.
My apartment was small but clean: one bedroom, a secondhand couch, a folding table I used as a desk, and boxes still stacked against one wall. Evan looked around as if he had expected to find me living in misery.
“You’re really staying here?”
“Yes.”
“What about home?”
“I don’t live there anymore.”
He sat on the edge of the couch.
For several seconds, neither of us spoke.
Then he said, “Mom told me you were trying to make money off them.”
“I’m trying to stop losing money because of them.”
He nodded slowly.
“I looked at the statements Dad left on the kitchen table.”
That surprised me.
“And?”
“I didn’t know you paid for my community-college tuition that semester.”
I looked away.
Three years earlier, Evan had nearly dropped out because Dad couldn’t cover a tuition balance. Mom told him she had “handled it.” In reality, she had called me at work crying. I paid the school directly.
“I thought they did,” he said.
“They asked me not to tell you.”
“Why?”
I gave him the answer I had finally understood.
“Because if everybody knew what I was paying for, they couldn’t keep calling me the dependent one.”
His eyes dropped.
At the birthday dinner, Evan had laughed louder than Dad.
Now he said, “I’m sorry.”
I believed him.
But I also told him, “Being sorry doesn’t mean I’m going back.”
“I know.”
For the first time in years, my brother and I spoke without Mom interpreting one of us to the other. He told me Dad’s business had never really recovered. Dad took small remodeling jobs but made nowhere near what he used to. Mom had been using credit cards again. They had assumed I would keep paying the mortgage indefinitely.
That explained why the bank call terrified them.
It wasn’t merely the house.
It was the end of a system.
The following Monday, we met again at Rachel’s office.
This time, only my parents came.
Dad looked older than he had the week before. Mom looked furious enough for both of them.
Dad spoke first.
“We can’t refinance.”
I had expected that.
Their income was too low, their debt too high, and interest rates made the payment difficult even if a lender approved them.
Rachel asked, “Are you prepared to discuss a sale?”
Mom crossed her arms.
“No.”
Dad said, “Linda.”
“No. My mother died in that house.”
“And our son owns forty percent of it,” Dad replied.
Mom turned toward him.
I had never seen Dad contradict her that quickly.
He continued, “We can’t afford it without him.”
Mom’s face tightened.
“We raised him.”
There it was again.
The invisible invoice for my existence.
Food when I was eight. Shoes when I was twelve. A bedroom when I was sixteen.
As if parenting had been a loan agreement I signed in the delivery room.
I leaned forward.
“You asked me on my birthday how I was going to pay you back for thirty years.”
Mom stared at me.
“So let’s answer that question.”
Rachel remained silent.
I opened the folder I had brought.
“I calculated everything I could reasonably identify that you paid for me after I turned eighteen. College help. My car insurance for two years. My phone bill. The months I lived at home before I started contributing. I even included an estimate for groceries.”
Mom’s expression shifted.
I slid the page toward her.
“The total is $31,460.”
Dad looked at it.
Mom did not.
I placed a second page beside it.
“My documented payments toward the house, family bills, emergency repairs, your debts, Evan’s tuition, and other expenses total more than four times that amount.”
“I never asked you to pay Evan’s tuition,” she said.
“You called me crying.”
“That was different.”
“No. It was exactly the same. Every time the family needed money, my contribution counted as love. Every time you wanted to humiliate me, it disappeared.”
The room went silent.
I pushed the first page closer to her.
“If you genuinely believe raising me created a debt, subtract $31,460 from what you owe me. I’ll accept that for purposes of this negotiation.”
Rachel glanced at me but didn’t interrupt.
Mom finally looked at the numbers.
I continued.
“But after today, nobody in this family gets to say I never paid you back.”
Dad’s eyes filled, though he blinked it away.
Mom stared at the spreadsheet for a long time.
Then she asked, very quietly, “What do you want?”
It was the first useful question she had asked me in years.
“I want out of the mortgage. I want my share of the equity. I want my finances separated from yours. And I want you to stop telling people I lived off you.”
“You want us to sell.”
“Yes.”
She looked wounded.
I didn’t enjoy that.
But I didn’t rescue her from it either.
The house went on the market eleven days later.
That did not mean the fighting stopped.
Mom objected to the listing price, then to the photographs, then to the showing schedule. She accused the agent of undervaluing the kitchen. She demanded that I pay for new countertops to increase the sale price.
I said no.
That one word saved me thousands of dollars.
No became easier after that.
No, I would not pay to repaint three bedrooms.
No, I would not cover their moving deposit.
No, I would not put Mom’s credit-card balance on one of my cards “temporarily.”
No, I would not move back in until the house sold.
No, I would not apologize to relatives for involving an attorney.
The house received an offer after five weeks.
It was less than Mom wanted and more than Rachel had told us to expect.
Dad accepted immediately.
Mom refused for two days.
Then the buyers threatened to walk, and Dad finally told her, “Daniel has carried us long enough.”
When he told me about that conversation, I didn’t know how to respond.
Part of me had waited years to hear him say something like that.
Another part knew it had arrived only after legal documents forced the truth into the open.
We closed on a rainy Thursday in November.
After the remaining mortgage, agent commissions, taxes, and closing costs were paid, the net proceeds were distributed according to the ownership shares listed on the deed, with a small adjustment everyone had negotiated for certain documented repairs.
My portion was a little over $96,000.
It wasn’t a fortune.
It wasn’t repayment for every dollar I had spent.
But when the wire landed in my account, I stared at the number for nearly a minute.
For six years, money had only moved one direction.
Away from me.
That afternoon, Dad asked if I wanted coffee.
We met at a diner off Interstate 71.
He apologized.
Not the vague kind.
He named things.
He apologized for letting Mom tell people I was lazy. He apologized for accepting mortgage payments without correcting relatives who thought he paid the bills. He apologized for laughing at the birthday dinner.
Then he said, “I think I laughed because it was easier than admitting how much we depended on you.”
I appreciated that he understood the difference.
I told him, “I’m not asking you to hate Mom.”
“I know.”
“I’m asking you never to help her rewrite this again.”
He nodded.
Mom did not apologize.
Not then.
She and Dad rented a smaller townhouse outside Columbus. Evan moved into an apartment with a coworker. I stayed where I was and used part of the sale proceeds to clear my remaining student loan and build an emergency fund.
Three months after closing, Mom sent me a long text.
She wrote that family should not treat relationships like business. She said she missed me. She said the house had been the center of the family and losing it had changed everything.
At the end, she wrote:
I hope someday you understand how much this hurt us.
I read the message twice.
Then I answered.
I understand.
That was all.
I did understand.
I understood that selling the house hurt her.
I understood that leaving frightened her.
I understood that boundaries felt cruel to someone who had benefited from my lack of them.
Understanding did not require surrender.
A week later, she texted again.
This time there was no accusation.
Can we have lunch?
I agreed.
We met in a crowded restaurant where neither of us could raise our voice without attracting attention.
Mom looked smaller somehow.
Not physically. Just less certain.
For the first twenty minutes, we talked about Dad, Evan, work, and the weather.
Then she set down her fork.
“That question you asked at your birthday,” she said.
I waited.
“Did you already plan all of this?”
“No.”
She looked surprised.
“I planned to keep paying,” I said. “I planned to keep living there. I planned to keep pretending it didn’t bother me.”
“Then why did you leave?”
“Because everybody laughed.”
She looked down.
“If it had only been you, maybe I would have argued. But when the whole table laughed, I realized you had told that story so many times that everyone believed it.”
She was silent.
I continued.
“And when I asked if you wanted me to stop paying for everything in my name, you said yes without even thinking about what that meant.”
“I said not to be dramatic.”
“You didn’t know what I paid.”
She looked at me then.
“No,” she said. “I knew more than I admitted.”
That was the closest thing to truth I had ever gotten from her.
She took a breath.
“I liked people thinking we were helping you.”
There it was.
No excuse.
No joke.
No misunderstanding.
Just the truth.
“Why?”
“Because after your father’s business failed, I was ashamed.”
I said nothing.
“And you were doing well,” she continued. “You had a good job. You were paying things. People would ask how Gary was doing, and I hated saying we needed help from our son.”
“So you made me look dependent.”
Her eyes filled with tears.
“Yes.”
I did not tell her it was okay.
It wasn’t.
But I appreciated that, finally, she had stopped arguing with reality.
We finished lunch.
Our relationship did not magically repair itself.
There were no dramatic hugs in the parking lot. No promise that everything would go back to normal.
I didn’t want normal back.
Normal was me paying.
Normal was them hiding it.
Normal was a room full of relatives laughing because the version of me they knew had been manufactured to protect my parents’ pride.
Over the next year, I saw Mom and Dad occasionally. Dad and I rebuilt something slowly. Evan and I became closer than we had been as teenagers. Mom learned that if she insulted me, I ended the conversation. If she asked for money, I said no. If she complained to relatives about me, I did not rush around defending myself.
The strangest part was how quickly the family adapted once I stopped volunteering to be the solution.
Dad took more consistent work with another contractor instead of trying to restart his old company. Mom picked up additional hours at the medical office where she worked. Evan paid his own bills.
The world did not end because Daniel Mercer stopped saving everyone.
It simply became more honest.
On my thirty-first birthday, I invited Dad, Evan, and two friends to dinner.
Mom was invited too.
She came carrying a small cake.
There were no speeches about debt.
No jokes about rent.
When the server brought the check, Dad reached for it.
I reached too.
He shook his head.
“Not this one.”
For a second, I almost argued out of habit.
Then I let go.
Dad paid.
Mom watched quietly.
Outside the restaurant, she handed me a card. Inside, beneath a simple birthday message, she had written one sentence by hand:
You never owed us for being our son.
I stood under the parking-lot lights reading it again.
It did not erase six years.
It did not restore the house.
It did not turn my thirtieth birthday into something that had never happened.
But I folded the card and put it in my coat pocket.
Some debts should be paid.
Some should be forgiven.
And some should never have existed in the first place.