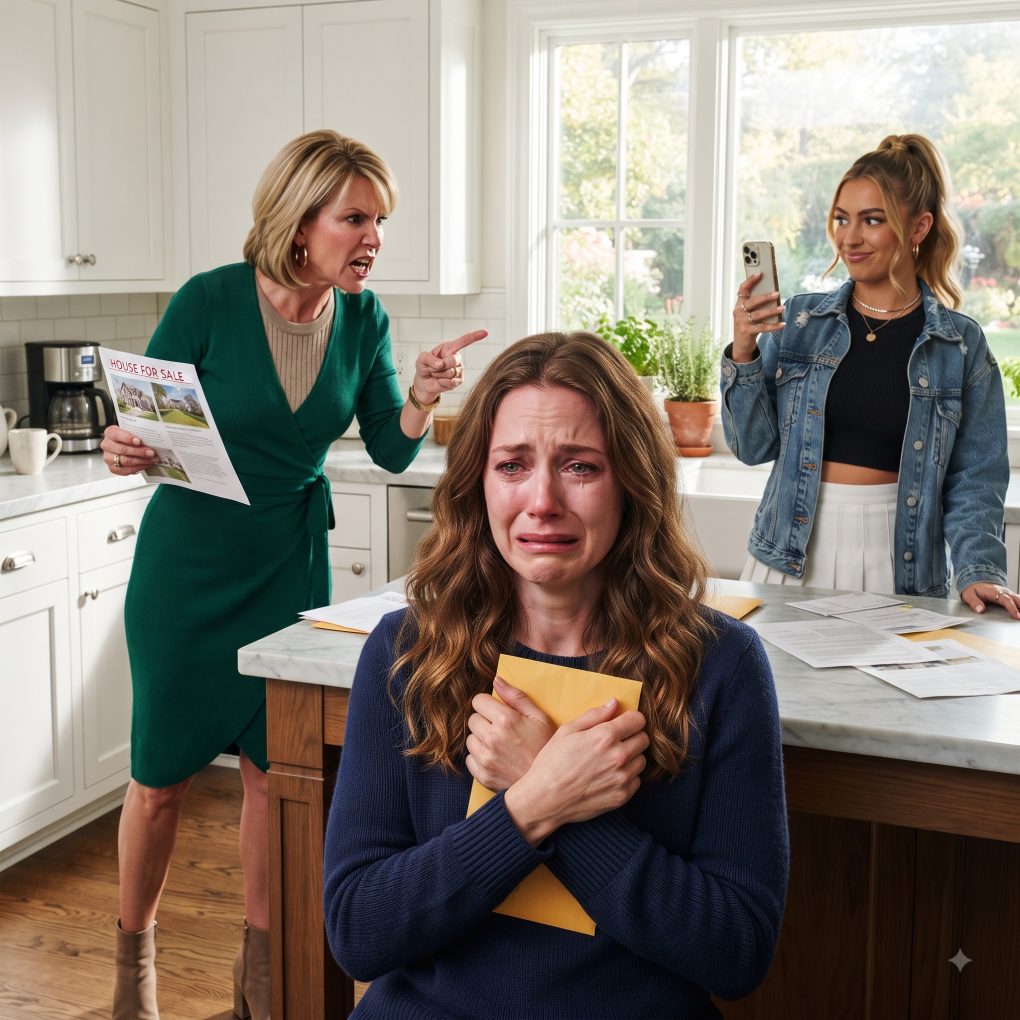
The listing sheet lay between my coffee mug and the bowl of oranges like a legal summons.
“We’re selling,” Mom said. “You have sixty days to leave.”
My younger sister, Brittany, already had her phone raised. The red recording dot glowed. “Finally,” she said, grinning. “Good luck, loser.”
I stared at the photo of our two-story house in Columbus, Ohio. Fresh lawn. White shutters. A bright red FOR SALE banner digitally stamped across the bottom.
“You listed the house?”
Mom folded her arms. “It’s my house. Your father is gone, Grandma is gone, and I’m done supporting a thirty-two-year-old who can’t get her life together.”
I had paid utilities for three years. I had covered the property taxes twice when Mom’s boutique failed. I had spent nine months caring for Grandma Evelyn through chemotherapy while Brittany posted beach photos from Florida.
But arguing would only feed the camera.
So I stood, walked upstairs, and pulled the yellow envelope from the back of my closet.
Grandma had handed it to me six days before she died.
“Only open this if they try to push you out,” she had whispered.
I had never opened it. Not until that morning.
Inside was a sealed copy of a deed, a letter, and a business card for Martin Hale, an estate attorney downtown.
An hour later, I sat across from Martin in a narrow office smelling of coffee and printer toner. He opened Grandma’s letter, read the first line, and stopped.
Then he rose, crossed the room, and locked the door.
“Ms. Somers,” he said, suddenly formal. “You need to sit down.”
“I am sitting.”
“Then stay that way.”
He turned the deed toward me.
The house had not belonged solely to my mother.
Four years earlier, after my grandfather’s death, Grandma Evelyn had purchased a fifty-one-percent ownership interest in the property when Mom refinanced to avoid foreclosure. The transaction had been recorded properly with Franklin County.
Then Grandma transferred that interest into a revocable trust.
I was the sole successor beneficiary.
My throat went dry. “So Mom can’t sell?”
Martin shook his head. “Not without your authorization. More importantly, according to this letter, your grandmother believed your mother planned to sell after her death and conceal your ownership.”
He tapped the next document.
It was a signed promissory note showing Mom owed the trust $186,000.
“If she lists the property as though she owns one hundred percent,” Martin said, “that creates a very serious problem.”
My phone buzzed.
Brittany had posted the video.
Caption: Kicked my freeloading sister out today. Best feeling ever.
Martin looked at the screen, then at me.
“Don’t respond,” he said. “Let them keep talking.”
Martin’s warning sounded strange until the next morning, when Mom texted me a screenshot of an offer.
CASH BUYER. $412,000. CLOSE IN 21 DAYS.
Underneath it she wrote: You need to be gone before inspection. Don’t embarrass me.
I forwarded everything to Martin.
Within two hours, he sent formal notice to Mom, her real-estate agent, the brokerage, and the title company handling the proposed closing. The letter stated that the property had multiple owners, that I held the controlling fifty-one-percent interest through the Evelyn Somers Trust, and that no sale could proceed without my written consent.
At 4:17 p.m., Mom called.
I answered on speaker while Martin sat beside me.
“What did you do?” she shouted.
“I told the truth.”
“You sabotaged my sale!”
“You listed property you don’t fully own.”
“That old paperwork means nothing. Your grandmother was confused.”
Martin silently shook his head.
“Grandma signed everything with her attorney and a notary,” I said. “It was recorded with the county.”
There was a pause.
Then Brittany’s voice came through in the background. “Tell her we’ll sue.”
Mom lowered her voice. “Listen to me, Claire. Withdraw whatever you filed. I’ll give you ten thousand dollars and help you find an apartment.”
I almost laughed.
“You offered me sixty days to disappear from a house I own more of than you do.”
“You don’t own this house. You stole it from me.”
“No. Grandma bought into it when the bank was ready to take it.”
Mom hung up.
That evening, Brittany uploaded another video. This one was less triumphant. She claimed I had manipulated a dying woman into changing her estate and was now “holding the family home hostage.”
The comments turned vicious.
Some called me greedy. Others called me a parasite. One former classmate messaged asking whether Grandma had even been mentally competent.
I wanted to defend myself publicly.
Martin told me not to.
“Documents beat internet arguments,” he said.
Three days later, Mom’s attorney finally contacted him.
That was when the story changed again.
During document exchange, we received copies of emails between Mom and the listing agent. In one, the agent had asked whether anyone else held an interest in the property.
Mom had replied: No. I am the sole owner.
Another email was worse.
Brittany had written to Mom: Once it closes, Claire can’t do anything. Just make sure the old trust stuff doesn’t show up.
I read that sentence twice.
“She knew,” I said.
Martin nodded. “They both knew enough to be concerned.”
The title company suspended the closing. The buyer withdrew his offer. The brokerage removed the listing and opened an internal review.
Mom blamed me for all of it.
Then she did something reckless.
While I was at work, she changed the locks.
My key no longer fit.
I stood on the porch at 7:30 that evening with my laptop bag hanging from my shoulder while rain soaked through my blouse.
Through the front window, I could see Brittany filming again.
Mom opened the door six inches.
“You were given notice,” she said.
“You can’t lock out a co-owner.”
“Call whoever you want.”
So I did.
I called Martin first.
Then I called the police non-emergency line.
The responding officer reviewed the recorded deed Martin emailed to my phone, spoke privately with Mom, and told her she could not simply exclude a documented co-owner from possession without a court order.
She unlocked the door.
Brittany stopped recording.
For the first time since this started, neither of them had anything clever to say.
But the next morning, Martin called me before eight.
“Claire,” he said, “we found something in your grandmother’s financial records.”
His tone was heavier than before.
“What?”
“The $186,000 loan wasn’t the only money your mother took.”
Martin asked me to come to his office before work.
When I arrived, he had three bank statements spread across the conference table and Grandma’s old check register beside them.
“At first I thought these were ordinary transfers,” he said. “They aren’t.”
Over the final eighteen months of Grandma’s life, nearly $94,000 had moved from one of her savings accounts into an account controlled by my mother. The transfers came in irregular amounts: $8,000, $12,500, $6,400, $15,000.
Every one of them had occurred after Grandma’s cancer returned.
My stomach tightened. “Are you saying Mom stole from her?”
“I’m saying we need to understand what these transfers were.”
He slid a photocopy toward me.
Grandma had kept meticulous handwritten notes beside most large withdrawals. Roof repair. Medical deductible. Property tax. Loan to Diane.
Beside three of the largest transfers, she had written the same thing:
Diane—temporary. Must repay.
Diane was my mother.
The records did not prove a crime by themselves. Martin was careful about that. Grandma might have authorized the transfers. Mom might have believed they were gifts. Family finances become messy quickly when people rely on conversations instead of contracts.
But the pattern mattered because the promissory note tied everything together.
The $186,000 debt was not one single loan. It consolidated years of money Grandma had advanced to Mom, including the amount used to rescue the house from foreclosure and several later transfers.
There was also an amendment.
If the debt remained unpaid when Grandma died, the trust could demand repayment from Mom’s share of the house or seek a court-ordered partition and sale.
“So she knew this could happen,” I said.
“Your grandmother planned for it,” Martin replied.
I leaned back.
All week, Mom had told anyone who would listen that I had stolen her inheritance.
The paperwork showed something very different.
Grandma had not given me a mansion free and clear. She had created a structure that protected the money she had repeatedly used to keep Mom afloat.
And she had put me in charge of enforcing it.
That afternoon, Martin sent Mom’s attorney a demand for a full accounting and proposed mediation before either side filed suit.
Mom refused.
Two days later, she filed first.
Her complaint alleged undue influence, lack of capacity, and fraud. She claimed I had isolated Grandma during treatment and manipulated her into transferring control of the house.
Reading it made my hands shake.
Not because it was true.
Because it rewrote the hardest year of my life into something ugly.
I had taken Grandma to chemotherapy because Mom said hospitals made her anxious. I had cooked meals Grandma could barely taste. I had slept on a recliner beside her bed after one emergency admission. I had washed her hair when she became too weak to stand in the shower.
Brittany had visited seven times.
Mom had visited more often, but rarely stayed longer than an hour.
Now those months were being described as a scheme.
Martin told me the case would turn on evidence, not family mythology.
Fortunately, Grandma had left plenty.
Her oncologist’s records described her as oriented and capable of making medical decisions throughout the period when the trust was amended.
Her financial adviser had notes from two meetings conducted without me present.
The attorney who drafted the trust had required Grandma to explain, in her own words, what she owned, what she wanted changed, and why.
His memorandum from that meeting was blunt:
Client states daughter Diane has poor financial judgment and has repeatedly failed to repay family loans. Client wishes controlling interest in residence to pass to granddaughter Claire, who has provided substantial caregiving assistance, and wishes existing debt obligations preserved.
I had never seen that sentence.
I cried in Martin’s office when I read it.
Not because of the house.
Because Grandma had known exactly what was happening.
She had seen everything.
The lawsuit moved into discovery.
That was when Brittany’s videos became useful.
Her first recording showed Mom clearly telling me the house was “hers” and ordering me out. Her second video, posted after the legal notice, accused me of blocking a sale they had already attempted despite knowing there was trust paperwork.
Then Martin subpoenaed their messages relating to the listing.
Mom’s attorney fought the request, but the judge ordered relevant communications produced.
There were dozens.
Most were ordinary conversations about staging, paint, furniture, and moving dates.
A few were devastating.
Six weeks before Mom confronted me at breakfast, Brittany had texted:
Did Claire ever find Evelyn’s envelope?
Mom replied:
No. She probably forgot about it.
Another exchange came three days before the listing went live.
Brittany: What if the title company finds Grandma’s share?
Mom: Let me handle it.
Brittany: Can we sell before Claire figures out what she has?
Mom: That is the plan.
I sat in silence while Martin read them.
He did not smile.
“This doesn’t decide the entire case,” he said, “but it makes their allegation that they knew nothing about the trust extremely difficult to maintain.”
Mediation was suddenly back on the table.
We met in a downtown conference center on a cold Thursday in November.
Mom sat across from me wearing a navy blazer I had given her for Christmas two years earlier.
Brittany sat beside her with no phone visible for once.
Their attorney did most of the talking.
He argued that a forced sale would consume money in fees and taxes. He argued that Mom had lived in the house for twenty-six years and should be allowed to remain. He suggested that I accept a cash payment and transfer my interest back to her.
The first offer was $35,000.
Martin did not even respond.
The second was $60,000.
Then $85,000.
The numbers sounded large until Martin placed the actual math on the table.
The house had been appraised at $438,000.
The mortgage balance was approximately $121,000.
After estimated selling costs, there would be substantial equity left.
My fifty-one-percent ownership interest was worth far more than what they were offering even before the trust’s debt claim was considered.
Mom finally looked directly at me.
“You really want to throw me out of my own home?”
The mediator glanced down at his notes.
I kept my voice steady.
“You tried to throw me out of a home you knew Grandma partly owned. You tried to sell it before I found the paperwork.”
“That’s not what happened.”
“I read the messages.”
Brittany interrupted. “Mom was panicking. She didn’t mean it literally.”
“Which part?”
Brittany’s mouth closed.
Mom leaned toward me.
“Your grandmother always favored you.”
There it was.
Not the deed.
Not the debt.
Not the listing.
The grievance underneath all of it.
Grandma had trusted me, and Mom had never forgiven either of us for it.
I did not argue about who Grandma loved more.
I simply said, “I’m following what she signed.”
The mediation lasted nine hours.
Near the end, Martin presented our final proposal.
Mom could choose one of two paths.
She could refinance the property within forty-five days, pay the trust an agreed amount satisfying my ownership interest and settling the debt claim, and keep the house.
Or the property would be sold through a mutually selected broker, with proceeds distributed according to the settlement formula.
Mom chose refinancing.
For ten days, she acted as if she had won.
Brittany posted that “certain greedy people” were about to be removed from the family home permanently.
Then the bank rejected Mom’s application.
Her income was too unstable. Her credit-card balances were too high. She could not qualify for a loan large enough to buy out the trust.
A second lender rejected her too.
The house had to be sold.
This time, my signature appeared on the listing agreement.
So did Mom’s.
The new agent priced it at $449,000.
We received four offers in the first week.
The accepted offer was $457,500 with conventional financing and no request for closing-cost assistance.
For the final month before closing, Mom and I lived in the same house like strangers.
She stayed downstairs.
I stayed upstairs.
Brittany stopped visiting after Martin sent a letter warning that further public statements falsely accusing me of criminal conduct could create additional legal issues.
Her videos quietly disappeared.
The morning before closing, I found Mom sitting alone at the kitchen table.
The same table where she had slid the original listing toward me.
There was no coffee.
No phone.
No audience.
“You could stop this,” she said.
“No.”
“You have money coming. You don’t need all of it.”
“This isn’t about taking everything.”
“It feels like it.”
I pulled out the chair across from her.
For a moment, I saw how tired she looked.
Then she said, “Your grandmother should have trusted me.”
I thought about Grandma’s checkbook.
Her loans.
The foreclosure notice she had paid.
The careful trust amendment.
“She did trust you,” I said. “More than once.”
Mom looked away.
Closing took forty-three minutes.
After the mortgage, commissions, taxes, settlement expenses, and negotiated trust repayment were handled, the remaining proceeds were distributed according to the settlement.
I received enough to put a substantial down payment on a townhouse fifteen minutes from my office and still keep an emergency fund.
Mom received enough to rent comfortably and pay down most of her high-interest debt.
Nobody became rich.
Nobody ended up homeless.
But the old arrangement—the one where Grandma rescued Mom, Mom blamed everyone else, and I quietly absorbed whatever was left—ended.
Three months later, Brittany texted me for the first time since the sale.
Mom needs help with her security deposit. Can you send $2,000? You owe her that much after what you did.
I stared at the message for a long time.
Then I typed:
No.
I did not explain.
I did not defend myself.
I did not send screenshots, legal documents, or calculations.
Just one word.
Brittany responded almost immediately.
Wow. Grandma would be ashamed of you.
That one almost worked.
Almost.
Then I remembered the line in Grandma’s attorney’s memorandum.
Client wishes controlling interest in residence to pass to granddaughter Claire.
Grandma had not left me a weapon.
She had left me a boundary she knew I would struggle to create for myself.
I blocked Brittany’s number.
A week later, I moved into my townhouse.
There was no dramatic celebration. No champagne. No speech.
I ordered pizza, assembled a cheap bookshelf badly, and sat on the floor because my couch had not been delivered yet.
Outside, rain tapped softly against the windows.
For the first time in years, every key in my pocket opened a door nobody could lock me out of.
I took Grandma’s yellow envelope from my moving box and placed it in the top drawer of my desk.
Not as proof.
Not as leverage.
Just as a reminder.
Sixty days earlier, my mother had slid a listing across the kitchen table and told me I had two months to disappear.
She thought the paper represented her control.
She had no idea another piece of paper had already changed everything.