“You’re not man enough to fight for the company you built.”
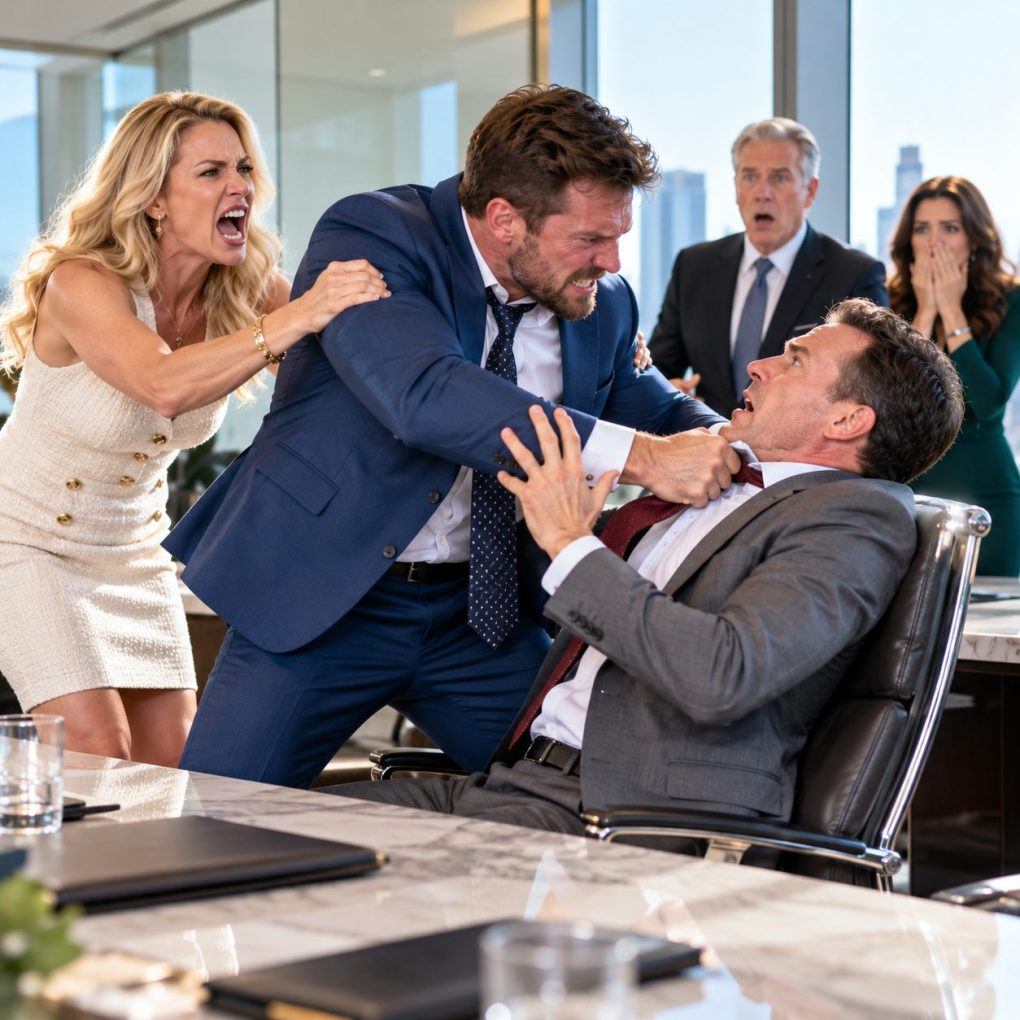
My wife, Vanessa, said it in front of twelve board members after her family voted to remove me as CEO.
Her father smiled.
Her brothers exchanged handshakes.
And the attorney at the end of the table quietly closed his eyes.
I did not argue.
I did not demand another vote.
I simply gathered my notebook, stood up, and said, “Then I assume everyone has read Article 11.”
Vanessa laughed.
“Go home, Daniel.”
So I did.
Fifteen years earlier, I had started Ashford Dynamics in a rented garage with one prototype, two maxed-out credit cards, and a patent my late father helped me file.
Vanessa’s family came in five years later when we needed capital to expand.
They invested heavily.
They also demanded board seats.
At the time, I was grateful.
Eventually, Vanessa and I married, and the company became a family empire worth nearly $180 million.
But success changed the room.
Her father began calling Ashford “our family business.”
Her brothers joined departments they barely understood.
Vanessa became chief strategy officer and slowly built a voting bloc around her relatives.
I saw it happening.
What they did not know was that I had seen it early enough to prepare.
When the investment agreement was rewritten seven years earlier, my father’s old attorney insisted on one unusual protection.
Article 11, Section B.
It was never designed to make me untouchable.
It was designed to stop any controlling family group from forcing out the founder and immediately taking possession of the intellectual property that made the company valuable.
Vanessa apparently remembered only the first page of the agreement.
At the board meeting, her father announced the vote.
Seven to five.
“Effective immediately,” he said, “Daniel Mercer is removed as chief executive.”
Vanessa leaned toward me with that satisfied smile.
“You should’ve fought harder.”
I nodded.
“Congratulations.”
That confused her.
But not enough.
I left the building, drove home, poured myself coffee, and turned off my phone.
At 7:18 the next morning, Vanessa’s phone rang.
It was Martin Shaw, the company’s outside counsel.
She answered on speaker because her parents were celebrating breakfast at our house.
According to Vanessa, his first words came out almost as a whisper.
“Tell me the resolution passed exactly as drafted.”
She said, “Of course it did.”
A long silence followed.
Then Martin said, “Vanessa… the vote didn’t remove Daniel the way you think.”
Her smile faded.
“What are you talking about?”
“It triggered Article 11, Section B.”
Her father stood up.
Martin’s voice shook.
“God help us all.”
By 8:00 a.m., Vanessa’s entire family was back in the boardroom.
I was not.
Martin projected the shareholder agreement and highlighted the clause they had ignored.
Article 11, Section B did not reverse the vote.
It did something worse for them.
If the founder was removed without cause by a coordinated shareholder bloc, the company automatically lost its exclusive license to the core patents unless an independent committee approved a new agreement within thirty days.
Those patents were mine.
Not the company’s.
My father and I had placed them in Mercer Innovation Trust years before Vanessa’s family invested.
Ashford Dynamics had grown rich because the trust licensed that technology to it for a nominal fee.
Vanessa’s father stared at Martin.
“You’re saying Daniel can take the patents?”
“No,” Martin replied. “I’m saying you voted to end the automatic license.”
The room went silent.
Without those patents, Ashford could still operate temporarily.
But its biggest contracts required guaranteed long-term access to the technology.
Three banks also had loan covenants tied to those contracts.
Vanessa called me twelve times.
I answered the thirteenth.
“You knew,” she said.
“I asked whether everyone had read Article 11.”
“You set us up!”
“No. Your lawyers negotiated that clause seven years ago.”
Then Martin interrupted from her side.
“There’s another provision.”
If the license terminated through a founder-removal event, the trust had first-refusal rights over any sale of the division built around its patents.
Vanessa’s father cursed.
Their plan had been simple: remove me, install her brother as CEO, then sell the technology division to a private-equity group already waiting.
But the vote they used to seize control activated the one clause that made that sale impossible without my trust.
Vanessa’s voice became quieter.
“What do you want?”
I looked at the agreement on my desk.
“An independent valuation. A clean board. And every related-party deal your family approved reviewed by outside auditors.”
She whispered, “And if we refuse?”
“Then thirty days becomes twenty-nine.”
They lasted six days.
Not because I threatened them.
Because the numbers did.
Two major customers asked for written confirmation that Ashford still controlled the patents supporting their contracts. The bank requested clarification on the licensing issue. The private-equity buyer suspended negotiations when its counsel read Article 11.
Vanessa’s family agreed to an independent review.
That review uncovered the real reason they had rushed the vote.
Her brothers had approved millions in consulting contracts to companies connected to relatives. None alone destroyed Ashford, but together they created enough exposure that an outside buyer would have demanded explanations.
Removing me before the sale was supposed to keep me from asking questions.
Instead, it guaranteed that everyone would.
The board reconvened.
This time, three independent directors voted to remove Vanessa’s father as chairman and suspend both brothers pending the audit.
Nobody reinstated me as CEO.
I did not ask them to.
Under a negotiated settlement, Mercer Innovation Trust granted Ashford a new long-term patent license at independently valued terms. In return, the company bought out most of Vanessa’s family’s voting shares and added rules preventing one family bloc from controlling the board again.
I remained the largest individual shareholder.
But I hired a professional CEO.
Vanessa and I separated soon afterward.
Our marriage had survived late nights, debt, expansion, and pressure.
It did not survive her deciding that humiliating me was part of a business strategy.
Months later, we met one final time to sign settlement papers.
She looked exhausted.
“You could have warned me about the clause.”
I closed my pen.
“I did.”
She stared at me.
“You asked if we’d read Article 11.”
“Yes.”
“That wasn’t a warning.”
“No,” I said. “That was due diligence.”
A year later, Ashford posted its strongest quarter.
I watched the announcement from my father’s workshop, where the first prototype still sat beneath a dusty cover.
Vanessa once said I was not man enough to fight for the company I built.
She misunderstood me.
I was never fighting for a chair.
I was protecting the foundation they forgot belonged to me.