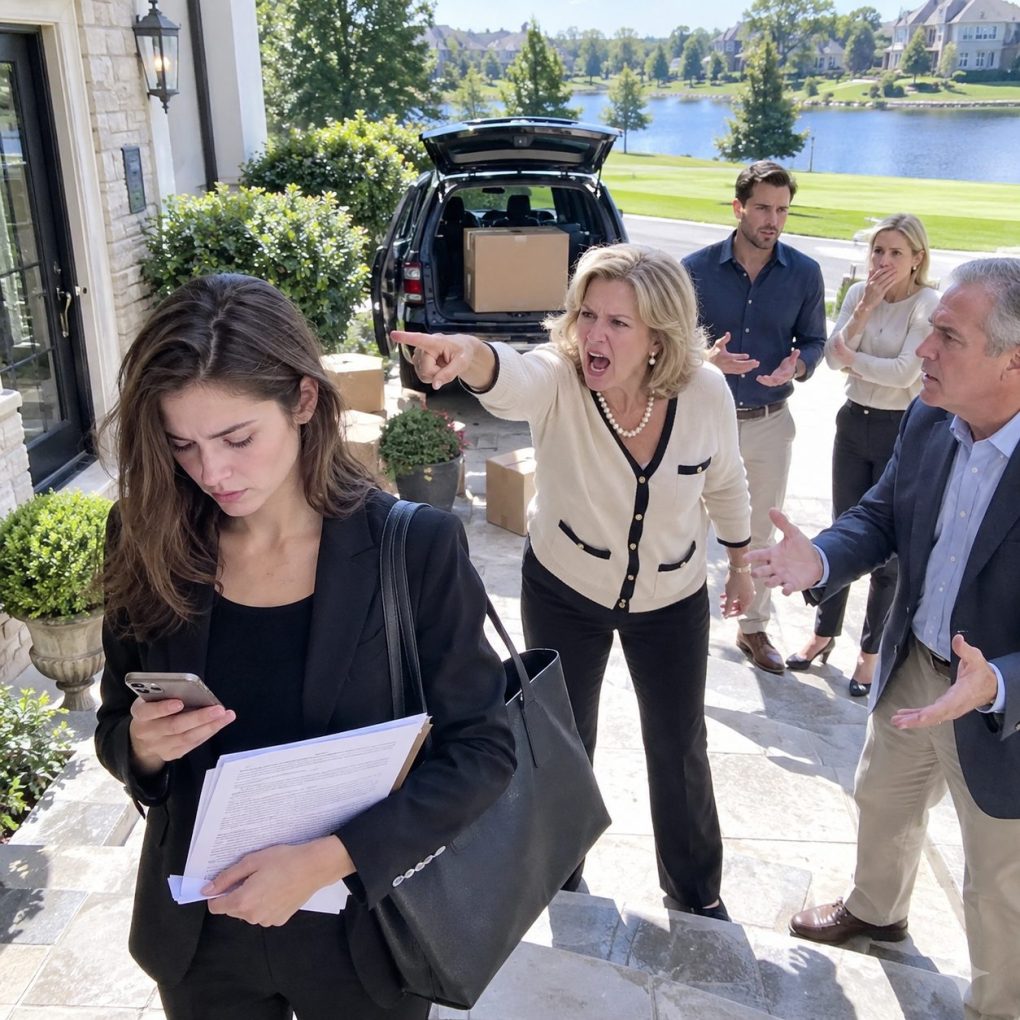
“You’re not part of this family anymore,” my mom texted. “Move on.”
I read the message twice in the parking lot outside the title company in Raleigh, North Carolina. My hands were steady. That surprised me.
For three years, I had been the invisible structure holding my family’s finances together. The lake house, the rental duplexes, the small strip mall my father had inherited from my grandfather—all of it had been placed into one family estate after Dad’s first heart scare. My parents liked to call it “our legacy.” What they never mentioned was that my income, credit, and signature were the reason the estate qualified for its most recent refinancing package.
Two weeks earlier, my younger brother, Ryan, had announced his engagement. At dinner, Mom told me I was “too controlling” because I questioned why the estate was paying for his $38,000 wedding deposit.
I asked one thing.
“Is that what Grandpa intended this money for?”
Mom’s face hardened.
Ryan laughed.
By the next morning, I had been removed from the family group chat.
Then came the text.
So I walked into the title office and sat across from a woman named Melissa Grant. She pulled up the refinancing file and confirmed what I already knew: the bank still needed my personal guarantee and my notarized consent because my name was tied to two of the properties being used as collateral.
“I want out,” I said.
Melissa blinked. “Completely?”
“Completely.”
She explained that withdrawing would likely delay or kill the refinance. Without the new loan, the estate couldn’t roll over a balloon payment due in nine days.
I signed anyway.
Then I met with an estate attorney and filed the paperwork to disclaim my management interest and remove myself from future guarantees.
I wasn’t taking their property.
I was simply refusing to secure it with my name.
At 4:17 p.m., my father called.
At 4:19, Ryan called.
At 4:21, Mom sent:
“What did you do?”
I stared at the screen until another message appeared.
“The bank froze everything. Call me NOW.”
I put my phone face down on the passenger seat.
For the first time in years, their emergency was not automatically mine.
I started the engine, but I didn’t drive away immediately. Through the windshield, afternoon traffic moved past as if nothing had happened. My phone buzzed again and again beside me.
I knew exactly what they wanted.
Not a daughter.
Not a sister.
Just the signature they had assumed would always be there.
By 7:00 that evening, I had seventeen missed calls.
Mom finally left a voicemail.
“Claire, this has gone too far. Whatever you think we did, you need to fix this tonight.”
Not I’m sorry.
Not we shouldn’t have cut you out.
Fix this.
I drove home, made coffee, and opened the folder my attorney had given me. Every page confirmed the same thing: I had not taken anything from them. I had simply stopped lending my credit, income, and legal liability to people who had just told me I was no longer family.
The next morning, Dad appeared at my apartment.
He looked ten years older than he had at Sunday dinner.
“The bank says the refinance can’t close without you,” he said.
“I know.”
“If the balloon payment hits, we’ll have to sell something fast.”
I nodded.
His jaw tightened.
“Your grandfather built this estate for all of us.”
“Then why was estate money paying for Ryan’s wedding?”
Dad looked away.
That silence answered more than an argument could.
He admitted there was more.
Ryan had borrowed against expected rental income to expand his landscaping company. Mom had approved it. Dad had signed off because he believed the refinance would cover everything.
“How much?” I asked.
“Two hundred and forty thousand.”
I almost laughed, but nothing about it was funny.
That afternoon, Mom came too.
She did not sit down.
“You’re punishing the entire family because your feelings got hurt.”
I looked at her for a long moment.
“You told me I wasn’t family.”
“You know I didn’t mean it literally.”
“But you meant it enough to send it.”
Her eyes flicked toward the paperwork on my table.
“Put your name back on.”
“No.”
Her face changed.
It was the first time I had ever told her no without explaining myself into exhaustion.
That night, Ryan sent me a message.
“You’re going to destroy Grandpa’s legacy over a text?”
I answered for the first time.
“No. I’m refusing to destroy my future to protect decisions I didn’t make.”
Three days later, the bank issued a formal notice: no refinance without additional collateral or a qualified guarantor.
And then my father called again.
This time, his voice was quiet.
“Claire, I found something in the old estate files. Your grandfather left instructions about what happens if the family starts borrowing against the properties.”
I sat upright.
“What instructions?”
Dad paused.
“The kind your mother never expected anyone to read—and the kind that could change who actually controlled the estate.”
Sometimes the deepest betrayal is not the insult itself. It is realizing how long your loyalty was being treated as a resource instead of a relationship.
The next morning, Dad brought over a faded accordion folder with my grandfather’s handwriting on the front.
Inside was a letter dated six months before he died.
It was not dramatic.
Grandpa had never been dramatic.
He wrote that the real estate was meant to produce income, not finance lifestyles, weddings, business experiments, or personal debt. More importantly, he had instructed the family attorney to require unanimous written approval from the designated managers before any property could be pledged beyond a certain percentage of its value.
At the time he wrote it, the managers were Dad, Mom, and me.
I stared at the page.
“Did the bank know about this?”
Dad shook his head.
“The old attorney retired. I don’t think anyone sent the letter with the later records.”
My attorney did.
Within forty-eight hours, the refinance was not merely delayed.
It was restructured from the beginning.
That changed everything.
The bank separated the legitimate property debt from Ryan’s business borrowing. The estate could still survive, but not by hiding personal obligations inside a larger loan.
One duplex had to be sold.
Ryan had to refinance his company debt separately.
The wedding venue deposit was treated as a personal family expense and repaid to the estate.
Mom blamed me for all of it.
For about a week.
Then the numbers became impossible to argue with.
The duplex sold quickly and covered the balloon payment with enough left to stabilize the remaining properties. Dad hired an independent property manager. Monthly statements went to all beneficiaries.
No one could move money without documentation.
Ryan downsized his wedding.
He also stopped speaking to me for four months.
I was surprisingly fine with that.
The harder part was Mom.
She called one Sunday evening and said, “I still think you could have handled it differently.”
I leaned against my kitchen counter.
“So could you.”
Silence.
Then, quietly, she said, “I was angry when I sent that message.”
“I know.”
“I didn’t expect you to actually leave.”
That sentence stayed with me.
Because that had been the family pattern for years.
They could exclude me, mock me, use my stability, then assume I would still be standing in the same place when they needed something.
“I didn’t leave because of one text,” I told her. “The text just made the arrangement honest.”
She cried.
I did not rush to comfort her.
That was new too.
Six months later, Dad and I met at the lake house. The place looked exactly the same: gray water, old dock, white porch chairs facing the trees.
But the paperwork was different.
My name was no longer attached to anyone else’s debt.
I still held the inheritance Grandpa had actually left me, but I was not a guarantor, manager, or emergency wallet.
Ryan eventually apologized.
Not elegantly.
He sent:
“I was an ass. I get it now.”
I replied:
“Thank you.”
Mom took longer.
At Christmas, she handed me a card before dinner.
Inside, she had written one sentence:
“I’m learning that family doesn’t mean someone owes you access to their life.”
I kept the card.
Not because everything was fixed.
Because for once, the apology did not ask me to sign anything.
The estate survived.
Ryan survived.
My parents survived.
And so did I.
The strangest part was realizing that boundaries did not destroy my family.
They simply forced everyone to stop pretending love and financial dependence were the same thing.