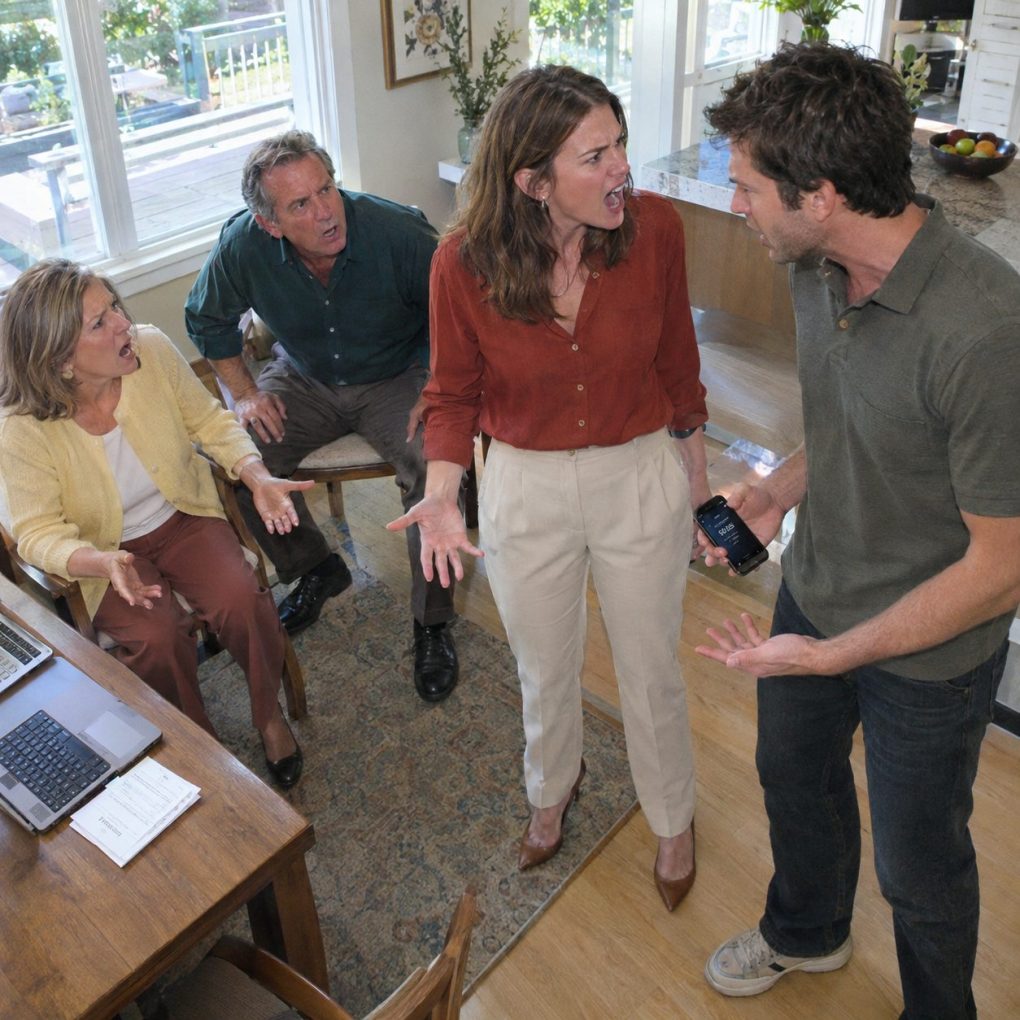
My mother called me on a Tuesday evening sounding strangely pleased with herself. “We added your brother to your bank account so he can access your $150,000 savings!” she announced, as if she had just solved a family problem for everyone. I stared at my phone in disbelief because the account was mine, funded entirely by years of overtime and disciplined saving. I had never given my parents permission to give Evan access to a single dollar.
I drove straight to my parents’ house, where Mom and Dad were sitting at the kitchen table with Evan. They acted as though I should be grateful for what they had done. Dad said Evan needed the money to restart his contracting business after his previous company failed, and Mom insisted that “family money” should go where it was most needed.
I asked how they had managed to add him without my signature. Dad reminded me that he had been listed as a joint owner on the account years ago when I was in college. He claimed that meant he still had authority to make changes, even though I had been depositing my own money into the account for more than a decade. Evan smiled and said, “I only need temporary access.”
I almost laughed because they had no idea what had happened the week before. After hearing my parents discuss Evan’s debts during Thanksgiving, I had quietly met with an attorney and my bank manager. I had moved almost all of my savings into a new account held solely in my name, leaving exactly five cents behind.
Mom proudly announced, “He can start using it tomorrow.” I looked at Evan and said, “Funny. I transferred it all.” His smile disappeared instantly, and Dad demanded to know what I had done with the money.
I told them the truth: the $150,000 was safely sitting in an account none of them could access. I had also documented the transfer carefully and confirmed with the bank that the new account belonged only to me. Dad slammed his palm against the table and accused me of deliberately sabotaging Evan’s future.
Evan opened his banking app and stared at the old account balance. The screen showed $0.05. He refreshed it twice, then looked at me as though I had somehow stolen something from him.
Mom called me selfish and said I should have trusted the family. I answered, “You trusted Evan with money that was never his.” She insisted that parents had the right to help their son, and I replied, “You have the right to help him with your money.”
Dad demanded that I transfer the savings back immediately. I refused and explained that I had spent years building that account because I wanted a home of my own, not because I was saving to finance Evan’s next business failure. For the first time, they realized there was nothing they could order me to do.
Evan stood up, furious, and accused me of humiliating him. I looked him directly in the eyes and said, “You tried to get access to my savings without asking me.” Then I walked out, leaving my parents staring at the five-cent balance they thought belonged to my brother.
The next morning, my father called before I had even finished breakfast. He demanded to know where the $150,000 had gone and warned me that moving the money after he had added Evan could create “legal consequences.” I told him the transfer had been completed before Evan was added, every transaction was documented, and I had already spoken with the bank.
Dad became louder and insisted that the money had been accumulated while I was still part of the family household. I reminded him that every dollar had come from my wages, my investment returns, and years of automatic deposits from my own paycheck. He had helped me open the original account when I was nineteen, but that did not give him ownership of the money forever.
Later that afternoon, a bank representative contacted me because Evan had attempted to move the remaining five cents and had also asked whether the institution could reverse my previous transfers. The representative confirmed that the new account was solely mine and that no one else had authorization to access it. I asked for written confirmation of the account history and saved every document.
When I told Mom what the bank had said, she accused me of turning a family disagreement into a legal battle. I answered that I had done nothing except protect my own savings. She then said Evan had already signed a lease on a workshop based on the assumption that I would provide the money.
That revelation made me furious. Evan had committed himself to a major business expense before he even had the money to pay for it. I asked Mom why nobody had discussed the plan with me, and she said, “Because we knew you’d say no.”
Those words finally explained everything. They had not added Evan to my account because they thought I would agree; they had done it because they knew I would refuse if they asked. I realized the real problem was not the money but the complete absence of respect for my decisions.
Evan came to my apartment that evening and tried a different approach. He said he would repay every dollar within eighteen months and offered me a handwritten agreement as proof. I told him that a promise to repay did not magically turn unauthorized access into a legitimate loan.
He became angry and said I was treating him like a criminal. I replied, “I’m treating my savings like mine.” He then admitted that he had already spent several thousand dollars on equipment deposits and needed the rest immediately or he would lose them.
I refused again. Instead, I suggested he speak to a bank, a legitimate investor, or a business partner who could evaluate his plan independently. He told me nobody trusted him because everyone remembered his last failure, and I quietly said, “Then prove them wrong without using me.”
That night, my parents sent me a long family group message accusing me of destroying Evan’s opportunity. I responded with one sentence: “You gave him access to my account without my consent, so I protected it.” After that, I muted the conversation because I knew the argument would continue only as long as I kept defending a decision that should never have required defending.
Two weeks later, Evan’s proposed business collapsed before it officially started. The investor he had been negotiating with reviewed his financial history and refused to provide funding after discovering that he had been depending on my savings without my authorization. Evan blamed me at first, but eventually he had to admit that the business plan had never been financially stable.
My parents remained angry for several months. Dad insisted that I had embarrassed the family by moving the money without telling him, while Mom kept saying she wished I had trusted them. I told them trust worked both ways, and adding someone to my bank account behind my back had destroyed far more trust than any transfer ever could.
I also closed the old account entirely. The five cents remained untouched until the bank processed the closure, and I watched with an odd sense of satisfaction as the account that had once held my entire savings disappeared from my financial profile. Then I updated every beneficiary, password, emergency contact, and account permission on my remaining finances.
My attorney also advised me to document exactly how the account had been handled. We kept copies of statements showing my deposits, records of the transfers, and the bank correspondence confirming that I had moved the funds before Evan was granted access. That paperwork gave me peace of mind because I no longer had to rely on anyone’s promises about what they believed they were entitled to.
Months later, Evan finally found a smaller business partner. Instead of buying expensive equipment immediately, he started with a single used truck and rented specialized tools when necessary. He complained constantly about having to start small, but for once, he was forced to build a company based on revenue rather than family money.
One afternoon, he called me and surprised me by apologizing. He admitted that he had assumed I would eventually rescue him because our parents had always taught him that I was the responsible one who could “handle it.” I told him I could forgive him, but forgiveness did not mean giving him access to my finances again.
Dad eventually apologized too, though it took much longer. He admitted that he had confused being Evan’s father with being entitled to control my money. Mom cried during that conversation and said she had been so focused on helping her favorite child that she had stopped noticing what her behavior was doing to the rest of the family.
I did not demand repayment for anything because the money had never left my control. Instead, I focused on what the experience taught me. I bought a house with part of the savings, continued investing the rest, and stopped discussing exact account balances with relatives.
The strangest part was how quickly the family dynamic changed once everyone understood that I could say no. There were no more surprise financial plans, no more assumptions about my savings, and no more conversations where Evan’s problems automatically became my responsibility. My parents finally learned that being family did not give them permission to spend money that belonged to someone else.
The account that once held $150,000 had ended with five cents, but that five-cent balance became a symbol of something much bigger. They thought they were giving Evan access to my money, but they had forgotten one important detail: the person who earned it still had the final say. I had not emptied the account to punish anyone; I had emptied it because I finally understood that protecting my future was not selfish—it was necessary.