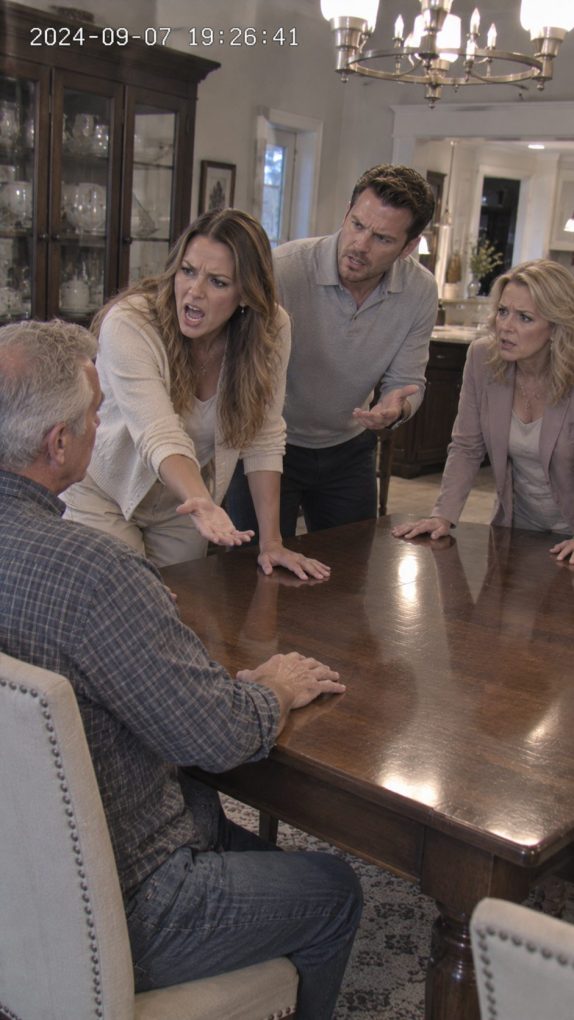
For fourteen months, my daughter Emily and her husband, Jason, lived in my mortgage-free house without paying a dollar of rent. Then one Sunday night, Emily slammed her fork against my dining table and said, “Dad, you seriously need to get a job.” Jason leaned back with a little smile, as if she had finally said what they had both been thinking.
I was sixty-six, retired, and widowed. The house outside Columbus, Ohio, had been paid off eight years earlier. Emily and Jason had moved in after their apartment lease ended, supposedly for three months while they saved for a down payment. Three months became fourteen.
I paid the property taxes, insurance, electricity, water, internet, and most groceries. Emily occasionally bought detergent. Jason once replaced a porch light and mentioned it for six weeks. Meanwhile, they ordered restaurant delivery four nights a week and took two vacations.
That evening, Emily looked around my kitchen and sighed. “You just sit around all day. Jason and I are trying to build a future. Watching you do nothing is depressing.”
I almost laughed. Instead, I asked, “Do you believe you’re supporting me?”
Jason answered before she could. “Well, we live here. We contribute. It’s basically a shared household.”
“Interesting,” I said.
I walked into my study and returned with a folder from the locked cabinet beside my desk. Inside was the recorded deed showing one owner: Richard Hayes. I placed it beside Emily’s dinner plate. Then I added fourteen months of utility statements, property-tax receipts, insurance bills, and grocery records.
Emily’s expression changed. Jason stopped smiling. I opened my banking app and showed them every transfer I had made covering expenses they had promised to repay. The total was $18,740.
“You told me to get a job,” I said calmly. “So starting tonight, I’m resigning from mine.”
Emily frowned. “What job?”
“Financing your lifestyle.”
I called my attorney, Susan Miller, from the kitchen. I had already discussed the possibility of formalizing their living arrangement months earlier. I told her I was ready. She said she would prepare written notice and a rental agreement in the morning.
Jason pushed his chair back. “You’d charge your own daughter rent?”
“No,” I said. “I’m giving two adults a choice. Pay fair rent under a written agreement, or find somewhere else to live.”
Emily stared at the deed beside her plate. For the first time in fourteen months, nobody complained that I wasn’t contributing.
The next morning, Susan emailed the documents. The proposed rent was $1,450 a month, below what similar houses in the neighborhood cost. Emily and Jason would also pay half the utilities. I wasn’t trying to profit from them. I wanted the free ride to end.
Emily came into the kitchen holding the printed agreement like it was an eviction order. “You actually did this?”
“You told me yesterday that adults should work and support themselves,” I said. “I agreed.”
She accused me of punishing her for one comment. That was when I opened my notebook. For fourteen months, I had recorded the money I spent because they were supposedly saving. Their contribution to household expenses averaged less than $120 a month.
Jason walked in and announced they had been saving aggressively. I asked how much. He refused to answer. Emily finally admitted they had about $6,000.
That made no sense. They both worked full-time. They had no rent, almost no utility expenses, and I had covered groceries. They should have saved several times that amount.
Then Emily admitted the truth. They had financed a newer SUV, taken a weeklong trip to California, upgraded their phones, and spent nearly $9,000 on furniture they planned to use “when we finally bought something nice.”
Something nice.
Those words landed harder than her dinner-table insult. My house had sheltered them for more than a year, but apparently it was only a temporary place beneath their standards.
I gave them thirty days to decide. If they stayed, the agreement started the following month. If they left, I would wish them well. But I immediately stopped paying their phone plan, streaming subscriptions, car insurance, and grocery delivery account.
Within forty-eight hours, the panic began. Jason discovered his insurance payment was much higher than he expected. Emily called from the supermarket asking why my card had disappeared from her grocery app. I reminded her that she had wanted me to become financially responsible.
Then Jason made his mistake. He called my younger brother, hoping to embarrass me. Instead, my brother asked him one question: “Do you know Richard paid for that house himself?”
That evening, Jason suddenly wanted to negotiate.
He offered $500 a month. I declined. He offered $700 including utilities. I slid the unsigned agreement back toward him.
“This isn’t a flea market,” I said.
Three days later, Emily told me they were moving. She expected me to panic.
I simply nodded and asked for their move-out date.
That was when she finally realized the house had never depended on them staying.
Emily and Jason found a two-bedroom apartment twenty minutes away. The rent was $2,180 before utilities, parking, internet, and insurance. Their first month required a security deposit and several fees. Suddenly, my $1,450 offer looked very different.
Emily called two days before moving and asked whether the rental agreement was still available. I told her it was, but Jason refused to live “under my rules.” She went quiet and said they would continue with the apartment.
Moving day was uncomfortable but peaceful. I helped carry boxes to the driveway. I didn’t lecture them. When Emily hugged me before leaving, she whispered, “I didn’t understand how much you were paying.”
“I know,” I said.
The real change came three weeks later. Without two additional adults in the house, my grocery and utility expenses dropped sharply. I canceled several subscriptions I never used and redirected the money into a travel account. For the first time since my wife died, the house felt completely mine again.
Meanwhile, reality hit Emily and Jason quickly. Their SUV payment, apartment rent, utilities, insurance, groceries, and credit cards consumed most of their income. The restaurant deliveries stopped. Their planned winter vacation disappeared. Jason sold some expensive electronics.
One Saturday, Emily came over alone. She brought groceries and cooked dinner in the same kitchen where she had told me to get a job. After we ate, she placed an envelope on the table.
Inside was a check for $1,000.
“What’s this?”
“Part of what we owe you,” she said. “I know it doesn’t cover everything.”
I pushed the check back once, but she insisted. She had created a monthly budget and finally calculated what I had quietly provided. She looked embarrassed when she admitted she had believed retirement meant I was doing nothing.
I told her something I should have said months earlier. I had worked forty-two years, invested carefully, paid off my home, and built enough savings to retire without depending on anyone. My quiet life wasn’t failure. It was the result of decades of work.
Emily apologized. Not dramatically. No tears, no excuses. Just a sincere apology that mattered because her behavior afterward changed.
Jason took longer. But eventually even he stopped making jokes about my retirement. Six months later, they moved into a cheaper apartment and began saving seriously.
I never collected the full $18,740. That stopped mattering. What mattered was that I stopped confusing generosity with obligation.
The deed is still locked inside my study.
But now, whenever Emily visits and places groceries on my counter, neither of us needs to open it.