“We got what we wanted,” my brother said after taking every cent from the account they believed was mine. My parents congratulated him and told me I was no longer useful to the family. I picked up my bag and left. Hours later, they learned the money was tied to an account none of them had legal authority to touch.
My name is Claire Bennett, and for most of my adult life, my family thought I was the reliable one.
Reliable meant I fixed problems.
I paid overdue bills.
I loaned my brother, Ryan, money when his contracting business stalled.
I covered Mom’s dental surgery and Dad’s property taxes when both hit in the same month.
So when I moved back to Columbus temporarily after ending a long relationship, everyone assumed the checking account they saw me using contained my personal savings.
It did not.
I worked as a court-appointed administrator for a small estate-management firm.
The account was a restricted disbursement account connected to a deceased client’s estate.
I was an authorized fiduciary signer.
I was not the owner.
The balance—$27,400—was waiting to cover final taxes, creditor settlements, and distributions to named beneficiaries.
My family knew none of that.
What they knew was that they had seen the bank card in my wallet.
Ryan had been asking me for $25,000 to rescue a failed renovation project.
I refused.
Three days later, my debit card disappeared.
So did an envelope containing an old PIN reminder I had stupidly kept in my desk.
By the time I noticed, the account had been emptied through multiple transfers and cash withdrawals.
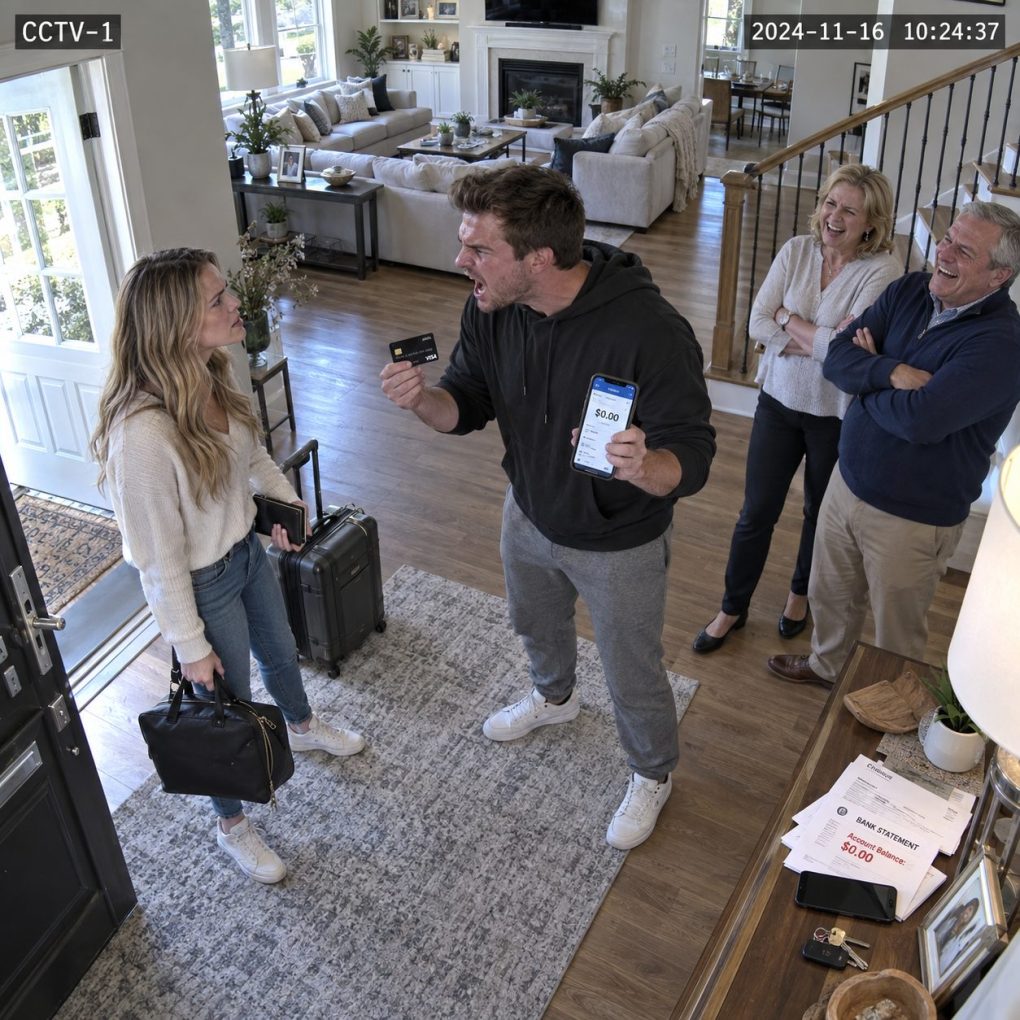
I confronted Ryan at my parents’ kitchen table.
He did not deny it.
He smiled.
“We got what we wanted.”
Mom actually said, “Good. Maybe now you’ll understand family comes first.”
Dad nodded.
Then Ryan pushed my suitcase toward me.
“You’re not useful anymore anyway.”
I stared at all three of them.
No screaming.
No threats.
I picked up my bag.
Then I called my supervisor from the driveway.
“Margaret, the Collins estate disbursement account has been compromised.”
Silence.
Then her voice changed.
“How much?”
“Everything.”
Within twenty minutes, our compliance attorney was on the call.
The bank froze the receiving accounts.
The estate’s counsel notified the probate court.
Because the money did not belong to me, I could not simply forgive the theft even if I wanted to.
At 8:14 that night, Ryan called.
He was no longer smiling.
“What did you do?”
“Reported an unauthorized withdrawal.”
“The bank says the money is estate property.”
“It is.”
Mom grabbed the phone from him.
“Claire, fix this.”
I looked at the suitcase beside me in my motel room.
“No.”
For years, they had treated my money like family property.
That night, they finally learned what happened when they took money that was never mine to give.
The next morning, I met with my employer’s compliance attorney, Susan Hale, and the estate’s probate lawyer. My first fear was that I would lose my job because the card and PIN had been accessible in my parents’ house. Susan did not minimize that mistake. I had violated internal security policy by failing to secure fiduciary access properly, and there would be consequences.
But poor safeguarding did not turn Ryan’s withdrawals into authorized transactions. The bank records showed the card being used at three ATMs near his construction site, followed by two electronic transfers into an account belonging to Bennett Renovations LLC, his company. Surveillance footage placed Ryan at one of the ATMs.
The money belonged to the estate of Harold Collins, a retired teacher whose will directed final distributions to his two nieces and a literacy charity after debts and taxes were paid. I had no personal claim to the funds. My name appeared on the account because I was acting for the estate under court-supervised authority.
That distinction transformed the family dispute completely. If Ryan had stolen from my personal savings, I could have chosen whether to pursue repayment privately. Here, I had fiduciary duties. The beneficiaries and court had rights independent of my feelings toward my brother.
Ryan called repeatedly. He said he could return most of the money once a client paid him. Susan told me not to negotiate. The bank’s fraud unit, probate counsel, and law enforcement were already involved. Every communication needed to be preserved.
My parents finally understood the seriousness when officers arrived asking about the missing card and how Ryan obtained the PIN. Mom initially said I had “given family access before.” That was true only for my personal accounts years earlier. It had nothing to do with a restricted estate account.
Then investigators uncovered something I had not known. Ryan had photographed several documents in my room before taking the card. One photo on his phone showed the estate account statement. The heading clearly read Estate of Harold Collins — Fiduciary Disbursement Account.
That destroyed his claim that he believed it was simply my savings.
Dad asked me privately whether I could tell police it had been a misunderstanding. I said no. He responded, “He has a family, Claire.” I answered, “So do the people this money belongs to.” He had no reply.
The bank recovered approximately $18,000 before Ryan could spend it. Another $6,000 had gone toward supplier payments for his company. The remainder had been withdrawn in cash. The estate was temporarily made whole through my employer’s fidelity coverage while recovery efforts continued, so the beneficiaries did not have to wait indefinitely because of my family.
I was formally disciplined at work. I received a final written warning, mandatory retraining, and temporary removal from direct control of estate debit cards. That part embarrassed me deeply because my family’s wrongdoing did not erase my own carelessness.
Susan said something I needed to hear: “Accountability can belong to more than one person at the same time.”
Ryan was responsible for taking the money.
I was responsible for safeguarding access better.
Both facts could exist together.
Then the police found an older problem. Two years earlier, Ryan had opened a store credit account using my Social Security number and made several payments before closing it. I had never noticed because the balance had been paid.
That discovery changed the case again.
The estate account had not been the first time he treated my identity as another family resource.
It was simply the first time the consequences were impossible for everyone else to smooth over.
Ryan eventually accepted a plea agreement involving theft-related and identity-fraud offenses. Because most of the estate funds were recovered quickly, no beneficiary suffered permanent loss, and he had no serious prior criminal record, the outcome was less dramatic than my parents feared. He received probation, restitution obligations, community service, and strict financial conditions.
His construction company did not survive.
Several clients left after learning about the case, and suppliers tightened credit. Ryan blamed me for that at first. Through his attorney, he accused me of “destroying his livelihood over money that came back anyway.” I stopped reading messages after the third one.
The money returning did not erase what he chose to do.
My employer’s insurer recovered part of its payout through restitution and bank reversals. Harold Collins’s estate was completed seven months later. His nieces received their distributions, and the literacy charity received the gift specified in his will.
That mattered to me more than Ryan understood.
The account had never been abstract money.
It represented promises a dead man had made to people he cared about.
My own professional consequences lasted longer than the case. For nearly a year, I worked under enhanced supervision. I carried no physical debit cards for fiduciary accounts and used dual-approval systems for larger transfers. At first, I experienced that as humiliation.
Later, I recognized it as protection.
I had spent years treating family access as harmless because saying no created conflict.
That habit had followed me into a professional environment where access had to mean something precise.
I changed.
My parents changed more slowly.
Mom continued insisting Ryan had “made one desperate mistake.” Dad avoided discussing the identity-theft account entirely. Eventually, I told them I would not attend family gatherings where the case was rewritten as something I caused by reporting it.
For six months, we barely spoke.
Then Dad came to my apartment alone.
He brought an envelope.
Inside were copies of old texts between him and Ryan.
In one, Ryan wrote, Claire always has money somewhere. She’ll complain, then fix it.
Dad had replied with a laughing emoji.
Seeing that hurt almost more than the theft.
Dad said, “I think we trained him to believe that.”
I looked at him.
“We all did.”
Including me.
Every time I covered a problem without requiring repayment.
Every time I stayed quiet after someone used my information.
Every time I confused being helpful with being available without limits.
That did not make me responsible for Ryan’s crime.
But it helped explain the family system around it.
Mom apologized later.
Not perfectly.
She said, “I thought because you were the capable one, losing money wouldn’t hurt you the same way.”
I told her the account had not been mine.
She nodded.
“I know. I mean before that too.”
That was the first conversation we had ever had about what competence had cost me.
Ryan completed probation and eventually found work as a project supervisor for another contractor. He was no longer allowed to handle company finances. From what Dad told me, he became more careful.
We did not become close again.
Years later, we reached the point where we could sit at the same table without reopening the case.
That was enough.
The lesson I carried forward was not that family should never help one another.
I still help people I love.
But now help has boundaries.
Loans are documented.
Accounts are separate.
Passwords are private.
And nobody gets access simply because refusing would make dinner uncomfortable.
My family once believed my usefulness came from how much I could provide.
When the estate account emptied, they told me I was no longer useful.
Ironically, leaving that house was when I finally became useful to myself.
I rebuilt my finances, repaired my professional reputation, and eventually became a senior fiduciary officer at the same firm.
The job taught me something my family never had.
Ownership matters.
Authority matters.
Consent matters.
Money sitting near you does not become yours because you need it.
And a person’s ability to solve problems does not make them responsible for every problem you create.
Ryan thought he had taken my savings.
What he actually took was money protected by law, court supervision, beneficiaries, bank records, and an audit trail.
The consequences arrived fast.
But the deeper consequence was slower.
My family finally learned that access is not ownership.
And I finally learned the same thing about myself.
Being family did not give them access to everything I had.
Not my accounts.
Not my identity.
Not my labor.
And not the rest of my life.