“Cheers—we’re divorcing!”
Lauren said it into her phone with a champagne glass raised high, smiling at hundreds of people watching her livestream.
Then she turned the camera toward me.
“Say goodbye, Mark.”
I was standing in our kitchen holding the envelope from my attorney.
I did not argue.
I did not ask her to reconsider.
I set the envelope on the counter, removed the keys from my pocket, and placed them beside her glass.
“Good luck tomorrow,” I said.
She laughed.
“With what?”
“You’ll find out.”
That made her smile even wider.
For months, Lauren had been telling friends that she was finally “escaping a boring marriage.” She posted vague quotes about independence, fresh starts, and choosing herself.
What she never posted was who had paid for the lifestyle she was celebrating.
The house.
The lake cabin.
The cars.
The investment account she called “our retirement.”
Most of it had come from a family business I had inherited with my older sister, Rebecca.
Years earlier, when Lauren wanted to manage household finances, my sister insisted on one condition.
Any account tied to family-company distributions required two authorized signatories.
Me.
And Rebecca.
Lauren could use the household spending card, but she had no authority to alter ownership, close accounts, or move principal without approval.
She hated that arrangement.
I thought she had accepted it.
I was wrong.
The night before her livestream, my bank’s fraud department had called.
Lauren had submitted documents requesting immediate control of three accounts, claiming our separation agreement gave her sole authority.
There was only one problem.
We did not have a signed separation agreement.
The document she uploaded contained my name.
Not my signature.
My attorney advised me to say nothing until the bank completed its review.
So when Lauren announced our divorce online and demanded the house keys, I gave them to her.
The house was legally hers to occupy during the temporary separation anyway.
What she did not know was that the bank had frozen online access to every disputed account pending in-person verification.
The next morning, her phone stopped receiving banking notifications.
Then her cards linked to the disputed accounts were temporarily suspended.
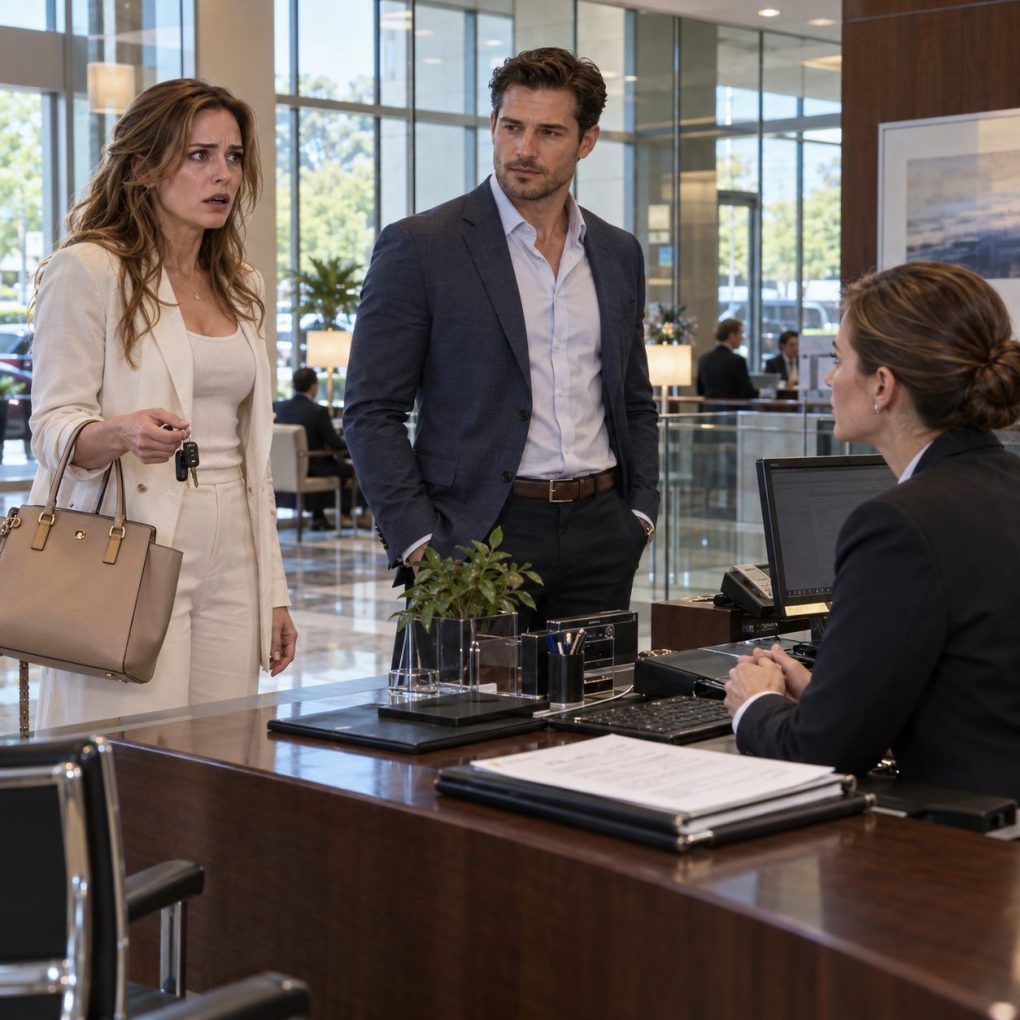
At 9:06 a.m., she stormed into the downtown branch.
The manager refused to discuss any ownership changes until “the primary signatory” arrived.
Lauren called me seventeen times.
I did not answer.
At 9:41, the glass doors opened.
Lauren looked up, expecting me.
Instead, my sister Rebecca walked in carrying the original account agreement and a folder from our attorney.
Lauren’s face went completely still.
Rebecca sat across from her and said, “Before we talk about money, perhaps you should explain why my brother’s signature appears on a document he never signed.”
Lauren stopped smiling.
The manager closed the door and placed the disputed form between them.
“I thought Mark signed it,” Lauren said.
Rebecca opened her folder.
“He didn’t.”
“This is a marital matter.”
The manager shook his head.
“It became a banking matter when this document was submitted.”
Then Rebecca showed her the second page.
Lauren had requested transfer authority over an investment account containing money from the family company.
That account was governed by the dual-signature agreement.
Even if the divorce became final, Lauren could not simply take control of it.
She would receive whatever the divorce settlement legally awarded her.
Nothing more.
Nothing less.
Lauren reached for her phone.
“My lawyer said I was entitled to half.”
Rebecca stayed calm.
“Half of what is marital property. Not half of every account with Mark’s name on it.”
Lauren called her attorney on speaker.
Then Rebecca emailed him the account agreement.
There was a long silence.
Finally he asked, “Lauren, who prepared the authorization form you submitted?”
She looked at the table.
“I did.”
“And Mark signed it?”
Another silence.
“No.”
The attorney’s tone changed immediately.
“Do not submit another document. Do not contact the bank without me. We need to correct this.”
Lauren’s face flushed.
“I was only protecting myself.”
Rebecca replied, “Then why did you try to move money the night before announcing the divorce?”
The manager added that the bank had preserved the upload logs and timestamps.
Lauren looked as if the room had become too small.
Then the manager turned toward Rebecca.
“There is one more issue.”
A second transfer request had been scheduled for that morning.
The destination account was not Lauren’s personal account.
It belonged to a newly registered company.
Lauren’s company.
And according to the filing, her new business partner was the man she had been calling her “financial advisor” for six months.
Rebecca looked at her.
“So this wasn’t just about divorce.”
Lauren whispered, “It was supposed to be my fresh start.”
The bank canceled the scheduled transfer and kept the disputed accounts frozen until the documentation review was complete.
Lauren’s attorney corrected the false authorization.
He made sure the divorce stayed focused on real property, real income, and real records.
Not social-media announcements.
Not assumptions.
Not revenge.
Lauren’s new company became part of financial disclosure because she had tried to fund it with money from a restricted account.
Her so-called advisor disappeared after learning the transfer had failed.
Three months later, mediation began.
The house was valued.
The joint savings were divided.
Lauren received her lawful share of marital assets.
The family-company investment account remained separate except for the portion my attorney and hers agreed was legally marital.
No one “took everything.”
But Lauren did lose something she had counted on.
Control.
She had assumed announcing the divorce first meant controlling the story.
She had assumed having passwords meant owning the money.
She had assumed confidence could replace paperwork.
It could not.
On the day we signed the final settlement, she looked at me across the conference table.
“Why did you say good luck tomorrow?”
“Because I knew the bank meeting was scheduled.”
“You could have warned me.”
“I did warn you. For years. Every time I told you those accounts had rules.”
She looked down.
Then she asked, “Did Rebecca hate me?”
“No.”
“She hated what you tried to do.”
Lauren nodded slowly.
The divorce became final two months later.
I moved into the lake cabin.
She kept the house after refinancing it in her own name.
Her online celebration disappeared.
So did most of the friends who had treated the divorce like entertainment.
The last time we spoke, she said, “I thought freedom meant not needing anyone’s permission.”
I answered, “Freedom still comes with signatures.”
She almost smiled.
Then we walked away in opposite directions.
Lauren wanted the divorce to begin with a toast.
Instead, it began with a bank manager, one missing signature, and the realization that money does not belong to whoever celebrates first.