Eight months after I won $5.4 million in the Ohio lottery, my CEO fired me in front of nearly sixty employees and told security to walk me out of the building. What Grant Halpern did not know was that the quiet procurement analyst he had just humiliated owned thirty-two percent of the company he was running.
I was thirty-six when I bought the winning ticket at a gas station outside Columbus, and I told almost nobody after the numbers matched. After taxes, accountants, and attorneys had finished turning the fantasy into actual money, I had a little over three million dollars available, but I kept driving my six-year-old Honda, kept my apartment, and returned to work at Ridgeway Industrial Systems on Monday morning as if nothing had happened.
Three months later, one of Ridgeway’s original investors decided to retire and sell most of his private shares after a difficult financial year had pushed the company’s valuation down. Through an LLC created by my attorney, I spent $2.46 million acquiring a thirty-two-percent voting stake, and although the board approved the transaction, my identity as the beneficial owner remained known only to company counsel, the retiring shareholder, and two directors who were legally required to know.
I stayed in my $71,000-a-year procurement job because I wanted to understand what I had purchased from the inside before making a single decision as an owner. That choice became more important when Grant arrived as CEO and immediately began talking about “discipline,” “efficiency,” and “cutting emotional attachments to legacy employees.”
Within four months, twenty-three people were gone, overtime disappeared, and annual raises were frozen, yet Ridgeway somehow found $940,000 for a consulting firm called Northline Advisory. I discovered that several Northline invoices contained duplicated services, vague descriptions, and rates nearly three times what comparable vendors charged, so I took my concerns to my supervisor, Melissa Crane.
She stared at the documents for ten seconds before pushing them back across her desk. “Daniel, you were hired to process contracts, not investigate executives.”
Two days later, Grant summoned the entire operations department into the cafeteria.
He stood beside Melissa with HR director Paul Keating holding an envelope, then announced that Ridgeway was “removing employees who resisted necessary transformation.” Grant looked straight at me and added, “Some people become dangerous when they mistake access to information for authority.”
Then Paul handed me the termination letter.
“You’re done here,” Grant said. “Security will escort you out.”
The room became completely silent as I folded the letter and slipped it into my jacket.
“Before security comes,” I said, “did the board approve this decision?”
Grant actually laughed.
“The board doesn’t approve the termination of ordinary employees.”
I looked toward the glass doors, where company attorney Rebecca Sloan had just entered with two directors behind her.
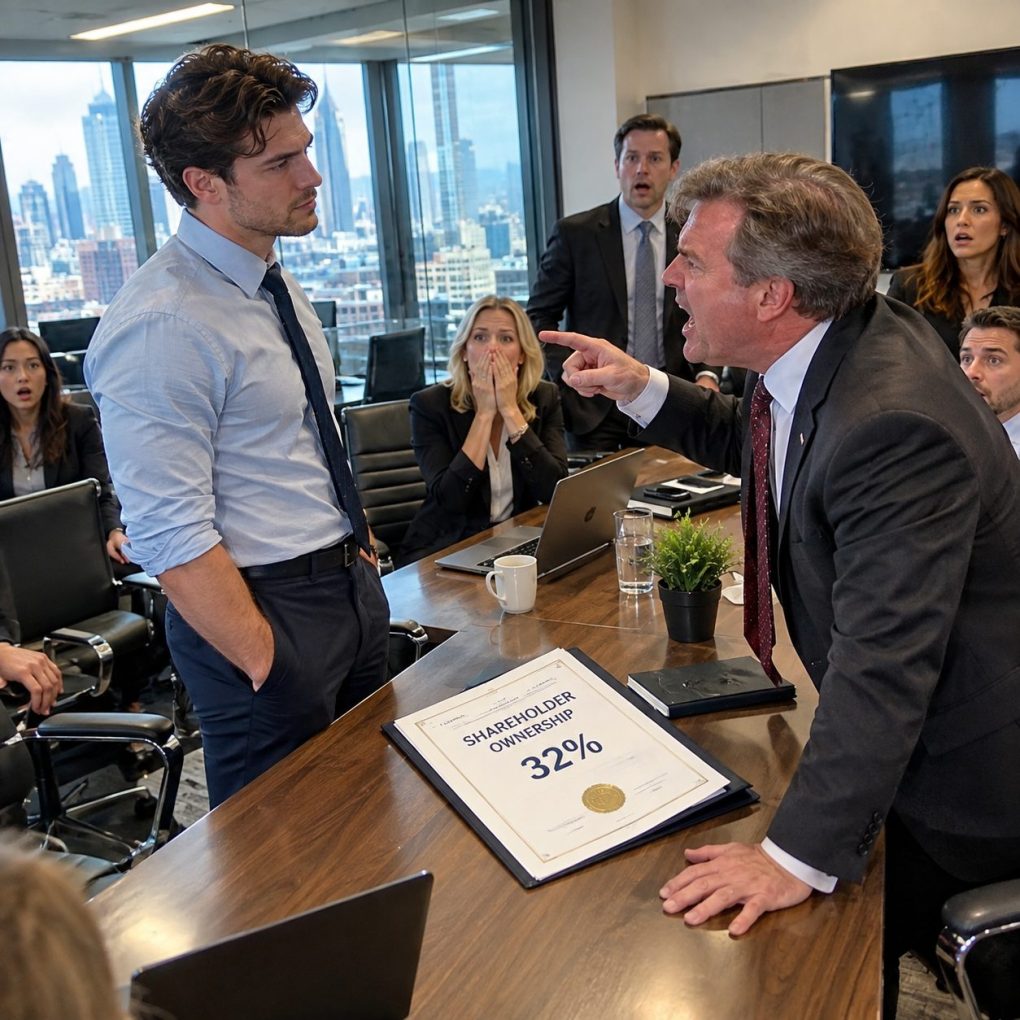
“No,” I said. “But they usually care when you fire someone who owns thirty-two percent of the company.”
Grant’s smile disappeared.
Rebecca placed a thick folder on the nearest table.
“Mr. Halpern,” she said quietly, “I strongly suggest you stop talking.”
“That’s impossible,” Grant finally said. “I know our shareholders.”
“You know the names on the capitalization table,” Rebecca replied. “Mercer Holdings LLC owns thirty-two percent of Ridgeway’s voting shares, and Daniel Mercer is its sole member.”
Grant’s face changed before he could control it.
I had imagined that moment more than once since purchasing the shares, but I felt surprisingly little satisfaction. Twenty-three people had already lost their jobs, families had reorganized their lives around frozen paychecks, and the documents I had collected suggested the problem was much bigger than one arrogant CEO embarrassing me in a cafeteria.
I told everyone I was not reversing my termination on the spot because ownership did not give me the right to ignore normal corporate governance. Instead, I formally requested that Rebecca preserve all Northline contracts, emails, invoices, executive expense records, and board communications, while Director Elaine Porter announced that an emergency board meeting would take place the following morning.
Grant tried to regain control. “This is retaliation by a disgruntled employee.”
“No,” I said. “Yesterday I was an employee reporting suspicious invoices. Today I’m a shareholder requesting an independent review of where my company’s money went.”
That distinction mattered.
Over the next twenty-four hours, things moved faster than Grant expected because I was not the only shareholder who had become uncomfortable with his leadership. Elaine controlled eleven percent of Ridgeway, the founding family still held twenty-one percent, and several smaller investors had been furious about falling margins despite aggressive layoffs.
The emergency meeting began at nine the next morning in a law office downtown. I attended as a shareholder, not as an employee, while Grant arrived with his own attorney and spent the first twenty minutes insisting that Northline had been hired because Ridgeway needed “specialized restructuring expertise.”
Then Rebecca displayed the ownership records.
Northline Advisory was majority-owned by Grant’s brother-in-law, Marcus Bell.
Grant had disclosed that Marcus was a relative, but he had represented Northline as an independently selected vendor whose pricing had been compared against competitors. The procurement files told a different story: two competing proposals had been created after Northline had already begun work, and metadata showed that one document originated from an account belonging to Grant’s executive assistant.
I had found something even worse during my final week as an employee.
Northline had billed Ridgeway $186,000 for a “regional supply-chain optimization study,” yet most of the material inside its report appeared to have been copied from an internal analysis produced by Ridgeway employees the previous year. The company had essentially paid an outside vendor to repackage work its own employees had already completed.
Grant stopped calling me disgruntled.
He started calling the documents “misinterpreted.”
The board voted to place him on paid administrative leave while outside counsel and a forensic accounting firm conducted an investigation. Melissa, who had approved several questionable purchase orders, was also suspended, while Paul from HR was instructed to preserve every record connected to the recent layoffs.
When the meeting ended, Elaine asked me whether I wanted my old job back.
“No,” I said. “Not yet.”
She looked surprised.
I explained that walking back into procurement the next morning would send exactly the wrong message. I had bought shares because I believed Ridgeway could become valuable again, and if I used my ownership simply to punish people who had insulted me, I would be no better than the executives who treated the company like their personal property.
Instead, I wanted three things.
An independent investigation, a review of every layoff made during Grant’s tenure, and a temporary freeze on executive bonuses until the board knew where the money had gone.
Elaine agreed to put all three proposals to a vote.
That afternoon, they passed.
Then my phone began filling with messages from coworkers who had watched me leave twenty-four hours earlier.
Most wanted to know why I had never told them I was rich.
One message came from my closest friend at Ridgeway, software engineer Nathan Brooks.
You really own a third of this place?
I smiled before answering.
Almost.
His next message came immediately.
Then please don’t become one of them.
I stared at those words longer than anything Grant had said to me.
Because that had always been the real danger.
The forensic investigation lasted seven weeks, and by the end of it, the story was less dramatic than some employees expected but much more damaging to Grant. Investigators found no secret offshore accounts or cinematic suitcase full of stolen cash, but they documented undisclosed conflicts, manipulated vendor comparisons, excessive consulting charges, and a pattern of steering work toward Northline without meaningful competition.
The board concluded that Grant had violated Ridgeway’s conflict-of-interest policy and repeatedly failed to provide directors with accurate information about the selection process. Northline agreed to repay $312,000 in disputed fees rather than face litigation, and Grant resigned before the board could vote on terminating him for cause.
Melissa resigned three days later.
I never celebrated either departure.
What mattered more was what happened to the people who had been treated as numbers on Grant’s spreadsheets, so the board reviewed all twenty-three layoffs individually. Eleven positions had genuinely become unnecessary because Ridgeway had automated or consolidated the work, but seven employees had been removed despite strong performance records, while five had been dismissed from departments that were already dangerously understaffed.
We offered those twelve people reinstatement with restored seniority.
Nine accepted.
The others had already found new jobs, so Ridgeway paid the severance amounts they should have received under the company’s previous restructuring policy. It cost money in the short term, but employee turnover immediately slowed, production delays dropped, and the angry conversations that had filled the building for months gradually became normal workplace complaints again.
The board asked me twice whether I wanted to become CEO.
I refused twice.
Winning the lottery had made me wealthy enough to buy influence, but it had not magically taught me how to run a 140-person industrial technology company. Instead, we hired Rachel Donovan, a former division president from a larger manufacturing firm who had spent twenty years managing operations, engineering teams, and corporate turnarounds.
Rachel’s first meeting with employees lasted almost two hours.
She did not promise there would never be another layoff, because serious leaders should not make promises they cannot guarantee. She promised that if cuts ever became necessary, management would explain the financial reasons honestly, executives would sacrifice compensation before asking hourly employees to carry the entire burden, and related-party contracts would require independent board approval.
I supported all three policies.
My own role became more complicated.
I joined the board but declined the chairman position, and I never returned to my old procurement desk. Instead, I served on Ridgeway’s audit and compensation committees, where my experience as an ordinary employee turned out to be unexpectedly useful because I knew how decisions that looked clean in board presentations actually affected people on the warehouse floor.
Nathan never stopped teasing me.
At the first company picnic under Rachel’s leadership, he handed me a paper plate and said, “You know, when someone secretly becomes a millionaire and buys thirty-two percent of his employer, normal people usually quit.”
“I considered it.”
“And?”
“I liked knowing whether the company was worth owning.”
He laughed. “So was it?”
I looked across the park at employees eating with their families, including several people who had been rehired after Grant’s departure.
“Ask me in five years.”
Three years later, Ridgeway was producing the answer.
Revenue had grown by forty-one percent, employee turnover had fallen by more than half, and the company had paid down most of the debt accumulated before I became a shareholder. My thirty-two-percent stake was worth considerably more than I had paid for it, even though I had never collected the enormous dividend some investors initially wanted because I kept voting to reinvest much of the profit.
I also never told most people how much lottery money remained in my personal accounts.
The jackpot changed my life, but the strangest thing it gave me was not a house, a car, or the ability to stop working. It gave me the chance to discover what people would say and do when they thought I had no power at all.
Grant thought I was disposable because my employee badge said “Procurement Analyst.”
Melissa thought my questions did not matter because my office was smaller than hers.
Neither understood that authority printed on a business card and ownership written into legal documents are two completely different things.
I eventually bought a modest house outside Columbus, replaced the old Honda, and helped my parents pay off their mortgage, but I never became interested in looking wealthy. The most expensive thing I owned was still the piece of Ridgeway I had purchased quietly when almost everyone else thought the company was struggling.
Sometimes new employees heard the story and asked whether it was true that the largest individual shareholder had once been fired from procurement.
I always corrected them.
“I wasn’t fired because I owned thirty-two percent,” I told them. “I was fired because I asked where the money was going.”
Then I usually added the part that mattered most.
“Buying the shares only made sure somebody eventually had to answer me.”