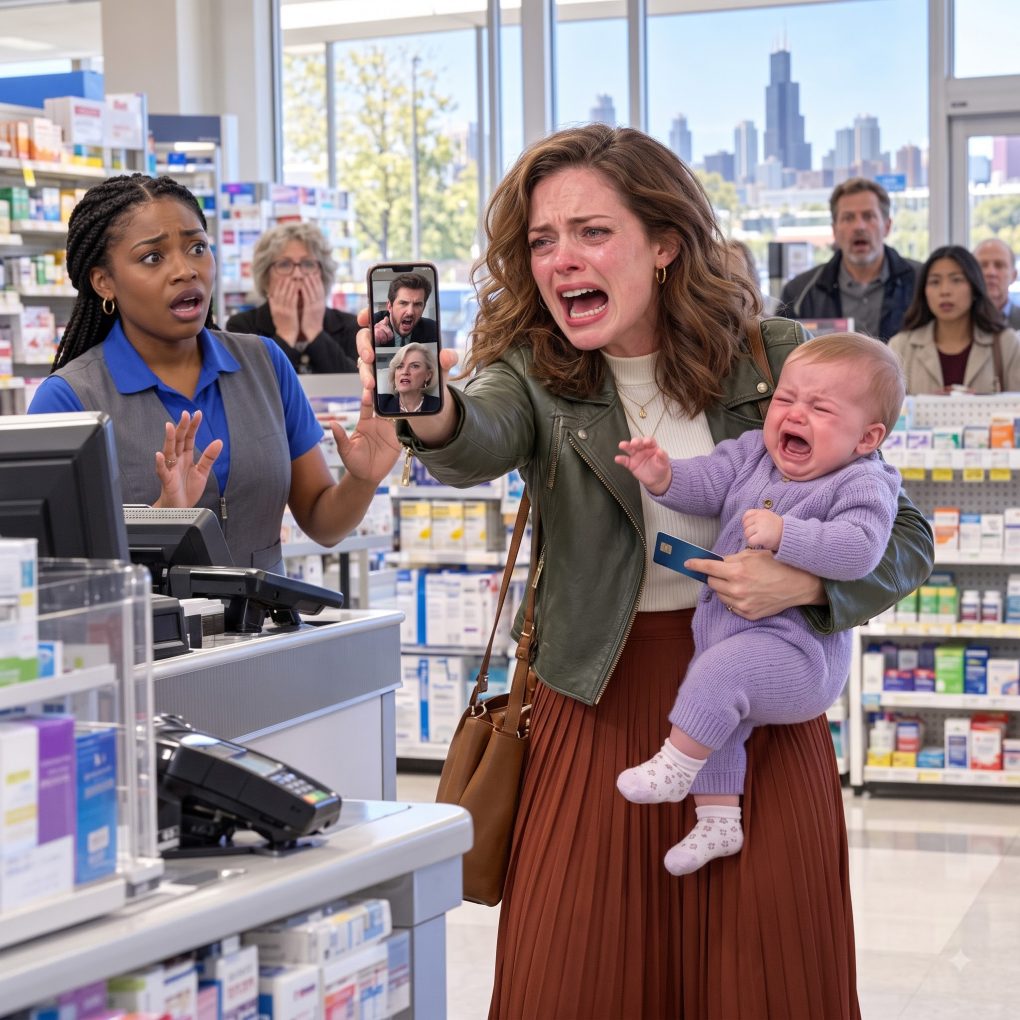
The card declined at a Walgreens in suburban Chicago while Claire Bennett stood at the register with a crying eight-month-old on her hip and two boxes of diapers on the counter.
“Try it again,” she said, forcing a smile.
The cashier did. Declined.
A man waiting behind her shifted impatiently. Claire could feel people looking without actually looking, that careful public embarrassment strangers pretended not to notice. Emma tugged at her coat and whimpered, tired and hungry.
Claire stepped aside, cheeks burning, and called her husband, Ryan.
His answer came after four rings. “What?”
“My card’s not working. I’m buying diapers for Emma.”
A pause. Then, flatly, “Not my problem. Figure it out yourself.”
Before Claire could answer, she heard his mother, Diane, in the background.
“Tell her to stop pretending she contributes,” Diane said loudly. “You useless leech.”
Claire went still.
For eleven months, since leaving her marketing job after a complicated pregnancy, she had tolerated the comments. Ryan controlled their shared checking account “for budgeting.” He gave Claire a credit card for groceries and baby expenses. Every time she asked about money, he said she was being dramatic.
She didn’t argue.
She hung up, opened her contacts, and called Martin Hale, a private banker at Lakeshore Trust.
“Claire?” he answered warmly. “Everything okay?”
“Yes,” she said. “Release the funds.”
Silence.
“All of them?”
“All of them. Move the liquidity account into my personal checking. Freeze outgoing transfers from the family trust pending review. And revoke Ryan’s authorized-user access.”
Martin’s tone changed instantly. “Understood. I’ll need your verbal security code.”
Claire gave it.
What Ryan and Diane had never bothered to learn was that Claire had not quit working because she had no money.
Her late father, a commercial-real-estate developer in Wisconsin, had left her a tightly managed inheritance worth just over $4.8 million. Claire had kept most of it separate on her attorney’s advice. During the marriage, she allowed Ryan limited access to one household account, believing transparency would eventually create trust.
Instead, Ryan had gradually rerouted bills, pushed Claire out of financial decisions, and convinced his mother that Claire was dependent on him.
Martin continued, “There’s something else. We flagged several unusual transfers from the household account into an LLC connected to Ryan’s consulting business. We were preparing to contact you.”
Claire looked through the Walgreens window at cold rain streaking the parking lot.
“How much?”
“Approximately eighty-seven thousand dollars over nine months.”
Claire’s grip tightened around her phone.
“Send everything to my attorney,” she said. “Every statement. Every transfer.”
Then she returned to the register.
Her debit card worked immediately.
Across town, Ryan’s phone began vibrating with bank alerts.
And for the first time in months, Claire smiled.
Ryan called before Claire had even buckled Emma into the car seat.
“What did you do?” he demanded.
Claire put the phone on speaker and started the engine.
“I bought diapers.”
“Don’t play games. My business card stopped working. The household account is restricted. Mom’s transfer got rejected.”
That last sentence sharpened everything.
“What transfer?”
Ryan hesitated.
Claire pulled out of the parking lot slowly.
“Ryan, what transfer?”
“It’s not what you think.”
“Then explain it.”
He began with irritation, not apology. He said Diane had needed help with a down payment on a condo in Arizona. He said his consulting company had a temporary cash-flow problem. He said married people helped each other. He said Claire had money sitting around “doing nothing” while he was trying to build something.
“You took eighty-seven thousand dollars,” Claire said.
“I moved money. I didn’t take it.”
“From an account funded almost entirely by my inheritance.”
“We’re married.”
“That doesn’t make every account yours.”
Ryan’s voice rose.
“You’ve been sitting at home for almost a year while I’ve been carrying this family.”
Claire nearly laughed.
She had paid the mortgage in full before Emma was born. She paid the property taxes. Her investments covered the insurance, utilities, childcare help, and nearly every major household expense.
Ryan paid for his truck, restaurants, and whatever he told people counted as “providing.”
But she didn’t argue the history over the phone.
“Where are you?” she asked.
“At Mom’s.”
“Stay there.”
“What does that mean?”
“It means don’t come home until my attorney contacts you.”
The silence on the line lasted three full seconds.
Then Diane grabbed the phone.
“You spoiled little brat,” she snapped. “You think money makes you powerful? Ryan married you when you were an emotional wreck after your father died. We took care of you.”
Claire stopped at a red light.
“No,” she said. “You mistook my silence for dependence.”
Diane scoffed.
“You’ll regret humiliating my son.”
Claire ended the call.
By the time she reached home, her attorney, Rachel Kim, had already received the bank records.
Rachel called from her office downtown and told Claire not to delete a single text, voicemail, email, or account alert.
“Some of these transfers concern me,” Rachel said. “Especially because several appear to have been authorized using credentials assigned to you.”
Claire’s stomach dropped.
“I never authorized them.”
“I suspected that. Do you know whether Ryan had access to your passwords?”
“He knew the passcode to an old tablet. I changed my banking password months ago.”
“Did the tablet remain logged in?”
Claire remembered it immediately: an iPad in the kitchen drawer, mostly used for recipes and streaming cartoons. Ryan had once complained that the facial recognition never worked for him.
“I don’t know.”
“Don’t touch it,” Rachel said. “I’m sending someone to collect it properly.”
Claire carried Emma upstairs, changed her diaper, and sat in the nursery while rain tapped against the windows. The room was quiet except for Emma babbling at a stuffed rabbit.
For months, Claire had wondered whether she was imagining the change in Ryan.
The small humiliations.
The missing statements.
The way he answered financial questions with jokes, then anger.
The way Diane suddenly seemed to know private details about Claire’s accounts.
Now the pattern was no longer emotional.
It was documented.
At 6:14 p.m., Ryan sent a text.
If you do this, you’re destroying our family.
Claire stared at it, then forwarded it to Rachel.
A minute later another message appeared.
Mom says we can fix this privately. Unfreeze the accounts and I’ll come home so we can talk.
Claire typed three words, then deleted them.
She did not need to win an argument.
She needed to understand how far he had gone.
At 7:03 p.m., Rachel called again.
Her voice was controlled.
“Claire, we found something bigger than the transfers.”
Claire stood beside Emma’s crib.
“What?”
“Ryan opened a line of credit using documents that list your trust distributions as household income. There’s also a signature that appears to be yours.”
Claire closed her eyes.
“How much?”
“One hundred and fifty thousand dollars.”
“And the balance?”
“Almost all of it.”
Outside, headlights swept across the front windows.
A car door slammed.
Then another.
Claire looked through the curtain.
Ryan had arrived.
And Diane was with him.
Claire did not open the door.
Ryan knocked once, then harder.
“Claire!”
Emma stirred in the crib.
Claire stepped into the hallway and checked the security camera on her phone. Ryan stood on the porch in a dark jacket, jaw clenched. Diane was beside him holding her purse under one arm as if she had arrived for a meeting she intended to control.
Claire called Rachel.
“They’re here.”
“Do not let them in,” Rachel said. “Is the house solely in your name?”
“Yes. I bought it before the wedding. Ryan has lived here since we married.”
“Then we still need to handle occupancy carefully. Don’t create a confrontation. If you feel threatened, call the police. Otherwise, communicate in writing.”
Ryan pounded again.
“You can’t lock me out of my own house!”
Claire opened the security app and pressed the microphone button.
“Ryan, I’m not discussing finances tonight. Rachel Kim will contact you in the morning. Please leave.”
Diane leaned toward the camera.
“This is ridiculous. Open the door.”
Claire released the button.
For several minutes they stayed on the porch. Ryan called six times. Diane called twice.
Claire answered none of them.
Then Ryan did something that made the last remaining part of her uncertainty disappear.
He tried his key.
The deadbolt turned halfway, stopped by the interior latch Claire had fastened after coming home, and rattled violently.
Emma began crying.
Claire called 911.
She did not dramatize. She did not claim Ryan had threatened to hurt her. She simply told the dispatcher that her estranged husband and his mother were outside, that she had asked them to leave, and that he was trying to force entry after she refused to open the door.
Two patrol cars arrived eleven minutes later.
By then Ryan had backed away from the door and was standing near the driveway, telling Diane something through clenched teeth.
Claire spoke to an officer from inside first, then opened the door while holding Emma.
Ryan immediately started explaining.
“This is a marital dispute. She froze our money and locked me out because she’s angry.”
The officer looked at Claire.
“Ma’am, do you want him removed from the property tonight?”
“Yes.”
Ryan stared at her.
That answer, more than the bank freeze, seemed to shock him.
Diane stepped forward.
“She’s unstable. She had postpartum anxiety. My son has been taking care of her.”
Claire felt the old reflex rise—the urge to defend herself, to explain every appointment, every sleepless night, every time Diane had converted a vulnerable moment into evidence against her.
Instead, Claire said, “Officer, I have asked both of them to leave.”
The officer nodded toward Ryan and Diane.
“You heard her.”
There was no dramatic arrest.
No shouting match worth filming.
Ryan and Diane walked back to the car furious and humiliated, while one officer remained until they drove away.
The next morning, Rachel filed for an emergency financial restraining order connected to the disputed marital assets and prepared Claire’s divorce petition.
The forensic review took three weeks.
What it uncovered was worse than Claire expected and, in another way, simpler.
Ryan’s consulting company had been failing for more than a year.
He had concealed tax debt, unpaid vendor invoices, and two business loans. Rather than admit the company was collapsing, he had maintained appearances.
He leased a newer truck.
He paid for client dinners at expensive restaurants.
He joined a private golf club because he believed wealthy contacts would rescue the business.
They did not.
When his own credit tightened, he began using the household account.
At first the withdrawals were small enough to blend into normal expenses: $1,800, then $2,400, then $3,100.
He labeled some as home repairs or estimated taxes.
Later, he transferred larger sums to his LLC.
Diane had received $24,000.
There was no Arizona condo.
She had used the money to pay off credit-card debt and renovate her kitchen.
When Rachel showed Claire the documentation, Claire read the invoices twice.
Custom cabinets.
Quartz countertops.
New appliances.
All while Diane had been calling her a leech.
The $150,000 credit line was the most serious issue.
The application included copies of Claire’s trust distribution statements, a digital version of her signature, and financial representations Claire said she had never approved.
The lender opened an internal fraud investigation.
Ryan’s attorney suddenly became much more interested in settlement.
Ryan, however, remained convinced that he could talk Claire out of proceeding.
He sent long emails.
He said he had panicked.
He said he intended to repay everything after landing a major client.
He said he never considered the money “hers” because marriage meant building a life together.
Then he switched approaches.
He accused Claire of hiding wealth from him.
He claimed her separate accounts proved she had never trusted him.
He said Diane had only insulted her because she was protective of her son.
One email ended with:
You’re really going to blow up Emma’s family over money?
Claire forwarded every message to Rachel without replying.
Six weeks after the Walgreens incident, mediation began in a conference suite overlooking downtown Chicago.
Ryan arrived in a navy suit Claire had bought him for their fifth anniversary.
Diane was not permitted in the mediation room, though she waited in the lobby anyway.
Claire sat beside Rachel with a binder of statements in front of her.
Ryan’s lawyer spoke first. He proposed that both parties waive certain claims, divide the marital property, establish a parenting schedule, and resolve the disputed transfers without litigation.
Rachel asked one question.
“Does your client acknowledge that the $87,000 transferred from the household account included Claire Bennett’s separate inherited funds?”
Ryan’s attorney answered carefully.
“He acknowledges the source of some deposits.”
Rachel turned a page.
“And does he acknowledge that approximately $24,000 went directly to his mother?”
Ryan shifted in his chair.
“It was a loan.”
“Where is the loan agreement?”
“There wasn’t one.”
“What were the repayment terms?”
“We hadn’t worked that out.”
Rachel looked at him.
“Because it wasn’t a loan.”
Ryan’s attorney raised a hand.
“We’re here to settle, not argue labels.”
Claire said nothing.
That had become her most effective habit.
Silence made Ryan fill the room.
He lasted less than five minutes.
“I was trying to keep everything afloat,” he said. “Claire had millions. Millions. And I was supposed to ask permission for every dollar while she sat at home?”
Rachel leaned back.
Claire finally spoke.
“I sat at home because our daughter was born six weeks early.”
Ryan looked away.
“I paid off the house before we married,” Claire continued. “I covered our health insurance. I funded the account you used for household expenses. I paid your business accountant twice when you said cash flow was tight. You told your mother I contributed nothing.”
“That’s not what I said.”
Claire opened her phone.
She played a voicemail Diane had left three months earlier.
Ryan needs a wife, not another dependent. If you had any pride, you’d earn your own money instead of living off him.
The room went quiet.
Ryan’s face reddened.
Claire stopped the recording.
“I’m not interested in correcting what your mother thinks of me. I’m interested in separating my finances from yours and establishing a stable parenting arrangement for Emma.”
Ryan stared at her as though he had expected tears, rage, or some visible sign that he still had access to the part of her he used to manipulate.
He got none.
The mediation did not finish that day.
But the balance had changed.
Over the next two months, Ryan agreed to repay a substantial portion of the diverted funds through the sale of business equipment and his share of marital assets.
Diane returned $18,000 after Rachel’s office sent a formal demand and made clear that the transfer history would be examined in any litigation concerning dissipation of assets.
The bank investigation into the credit line continued separately.
Claire cooperated, provided handwriting samples, device access logs, and sworn statements.
The lender eventually removed the debt from her responsibility while pursuing its own remedies against Ryan.
The divorce itself was less cinematic than people imagine.
There were spreadsheets.
Parenting proposals.
Disclosure forms.
Arguments about furniture.
There were days when Claire felt strong and days when she sat on the nursery floor after Emma fell asleep and wondered how she had failed to notice the marriage changing around her.
But each new document answered that question.
Ryan had not taken control overnight.
He had done it gradually.
First he offered to handle the bills because Claire was exhausted during pregnancy.
Then he changed passwords because he was “organizing things.”
Then he criticized her whenever she asked questions.
Then he treated access to money as proof of whether she deserved his approval.
Diane reinforced every step by framing Claire’s discomfort as ingratitude.
The declined card at Walgreens had not created the crisis.
It had exposed it.
Four months after that night, Claire returned to the same store.
Emma, now a sturdy one-year-old, sat in the cart chewing on a soft toy while Claire bought diapers, wipes, formula, and a birthday card for a friend.
At the register, Claire noticed a woman two lanes over quietly removing items from her basket after a card declined.
For a moment Claire was back in the rain, hearing Ryan say:
Not my problem.
She did not approach the woman or turn the moment into a speech.
She simply finished paying and walked outside.
Her phone buzzed.
A message from Rachel.
Final agreement signed. Judge enters the decree Friday.
Claire read it twice.
The settlement left the house with her.
Her inheritance remained separate.
Ryan received structured parenting time that expanded if he complied consistently with the schedule.
The financial settlement required repayment of additional diverted funds, though Claire accepted less than the theoretical maximum in exchange for ending the litigation without another year of legal fees and uncertainty.
It was not revenge.
It was an exit.
Ryan called that evening.
Claire almost let it go to voicemail, then answered because they still had to co-parent.
“I heard the agreement is done,” he said.
“Yes.”
Another pause.
“Do you ever think we could’ve fixed this?”
Claire looked across the living room. Emma was asleep against the shoulder of Claire’s sister, Natalie, who had come over with takeout.
“We could have fixed financial stress,” Claire said. “We could have fixed a failed business. We could have fixed debt.”
Ryan said nothing.
“But you needed me to believe I was powerless so you wouldn’t have to admit what you were doing.”
“That’s not fair.”
“It’s accurate.”
“You always think you’re the smartest person in the room.”
Claire glanced at the diaper bag beside the couch.
“No. For a long time, I thought I was the stupidest.”
Ryan exhaled.
“Mom says you’ve turned everyone against us.”
“I haven’t spoken to your mother in four months.”
“She lost money because of you.”
“No. She returned money that belonged to me.”
He was quiet again.
Claire waited.
Finally he said, “I have to go.”
“Okay. Your pickup with Emma is Saturday at ten. Please be on time.”
She ended the call.
On Friday morning, the judge entered the divorce decree.
There was no applause.
No dramatic final confrontation.
Claire walked down the courthouse steps with Rachel carrying a slim folder containing the signed order.
Traffic moved along the street.
A delivery truck honked.
People hurried past with coffee and briefcases, living ordinary lives.
Rachel stopped beside the curb.
“You okay?”
Claire considered the question.
“Yes,” she said. “I think I am.”
That afternoon, Claire met Martin at Lakeshore Trust.
He reviewed the new safeguards on her accounts: hardware authentication, separate devices, transaction alerts, and written restrictions preventing any future authorized user from moving trust funds without additional verification.
At the end of the meeting, Martin hesitated.
“I’m sorry we didn’t catch the pattern earlier.”
“You caught enough.”
“And the card decline?”
Claire smiled faintly.
“That wasn’t your bank.”
Martin frowned.
Claire explained that Ryan had lowered the spending limit on her household card that morning.
He had admitted it during discovery.
He wanted to force her to call him after an argument the night before.
Martin stared at her.
“So the declined diaper purchase was deliberate?”
“Yes.”
Ryan had wanted a small demonstration of control.
Something petty.
Something humiliating.
Something that would remind Claire who he believed had authority.
Instead, it made her call the one person who could see the accounts Ryan thought she knew nothing about.
Claire stood and slipped the updated documents into her bag.
Outside, the October air was sharp and bright.
She walked two blocks to a café where Natalie was waiting with Emma.
As soon as Emma saw her, she bounced in the high chair and reached both arms out.
Claire lifted her daughter and kissed the top of her head.
Natalie slid a coffee across the table.
“All done?”
Claire looked at the courthouse papers in her bag, then at the banking folder beside them.
“All done.”
Natalie smiled.
“So what happens now?”
Claire looked through the café window at people crossing the street beneath red and gold trees.
For nearly a year, every financial choice had felt like a request she needed permission to make.
Now there was no one to ask.
“I go back to work in January,” Claire said. “Three days a week at first. I talked to my old firm. They want me to lead the Midwest accounts.”
Natalie’s eyes widened.
“You didn’t tell me.”
“I wanted to make the decision before I announced it.”
“And the house?”
“I’m keeping it for now.”
“And Ryan?”
“He’s Emma’s father. I’ll deal with him as Emma’s father.”
Natalie nodded.
No grand declarations were necessary.
Claire had spent months collecting records, signing forms, meeting attorneys, changing passwords, rebuilding routines, and learning to distinguish compromise from surrender.
The result was not a perfect life.
It was a life she could account for.
Every dollar.
Every boundary.
Every choice.
A year later, on Emma’s second birthday, Claire found the old Walgreens receipt tucked into a side pocket of the diaper bag she was finally ready to donate.
Two boxes of diapers.
One pack of wipes.
Declined.
Then, minutes later, approved on a different card.
Claire held the faded paper for a moment.
Ryan had once believed that declining a purchase would remind her that she depended on him.
Instead, it became the receipt for the exact moment she stopped believing him.