My daughter-in-law told the bank I was too old to manage my own money. My son, Andrew, stood beside her and agreed. I was seventy-two, widowed, and perfectly capable of understanding every dollar I owned. I did not argue with either of them.
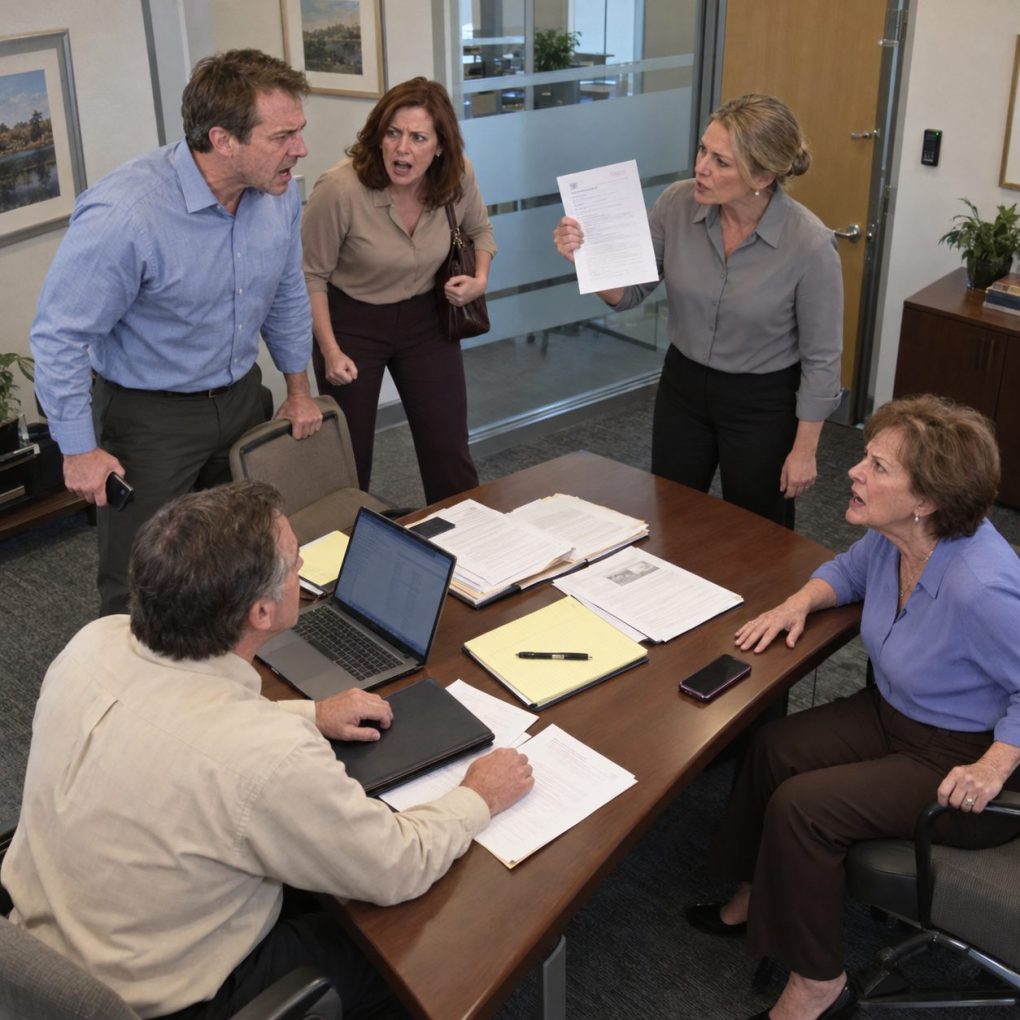
We were sitting inside a private office at a community bank in suburban Chicago. Melissa had arrived carrying a folder and speaking as if the decision had already been made. She told the branch manager that I had become forgetful and financially vulnerable. Andrew kept nodding.
Melissa wanted the bank to restrict my access until Andrew could be added as a joint owner. She said it was for my protection. I asked what evidence she had that I could not manage my accounts. She answered that people my age often did not realize when they were declining.
The branch manager looked uncomfortable. He explained that the bank could not simply hand control of my accounts to relatives because they requested it. Melissa immediately produced paperwork showing Andrew held an old financial power of attorney. I recognized the document.
I had signed it twelve years earlier during cancer treatment. It was meant to let Andrew pay bills if I became incapacitated. I had recovered years ago and never needed him to use it. What Andrew apparently did not know was that I had revoked it eighteen months earlier.
I looked at my son and asked whether he had discussed this visit with me beforehand. He avoided my eyes. Melissa answered for him, saying families sometimes had to make hard decisions. That was when I understood the meeting was not about concern.
I excused myself and walked into the lobby. Then I called Samuel Reed, the private banker who had handled my accounts for twenty-seven years. I told him exactly where I was and what Andrew and Melissa were trying to do. Samuel listened without interrupting.
He asked one question. “Did you authorize any changes?” I said no. He told me to remain at the branch and not sign anything. Then he hung up.
Ten minutes later, Andrew’s phone rang.
He answered with irritation, then suddenly went silent. His face changed while Melissa watched him. Samuel said only four words.
“You need to come here.”
Andrew asked who was calling, although I could tell he already knew. He listened for several seconds and then said, “We’re already at the bank.” Samuel told him the meeting needed to continue at his downtown office with the bank’s legal department present. Melissa immediately demanded to know why.
I returned to the conference room without raising my voice. The branch manager quietly informed them that no restrictions would be placed on my accounts that day. He also said the power of attorney they presented was no longer valid according to the bank’s records. Andrew stared at me.
Melissa accused me of secretly changing documents behind their backs. I reminded her that my finances did not require her permission. Andrew asked when I had revoked his authority. I told him I had done it after discovering two withdrawals I never approved.
Those withdrawals were why Samuel reacted so quickly.
Six months earlier, I noticed two electronic transfers totaling $38,500 from a savings account I rarely touched. The destination was an account connected to Andrew’s home renovation company. Andrew claimed at the time that I had verbally agreed to lend him the money.
I had not.
Because I loved my son, I did not report him immediately. I required him to repay the money and quietly met with Samuel and an estate attorney. We revoked the old power of attorney, created new account controls, and documented that Andrew had no authority unless I became legally incapacitated.
He repaid only $12,000.
Samuel had also noticed several recent inquiries about my certificates of deposit and investment accounts. Someone using information tied to Andrew had asked what documentation would be required to change account access. None of those inquiries had resulted in a transaction, but the pattern concerned the bank.
Melissa turned pale when she heard that.
At Samuel’s office later that afternoon, the bank’s attorney asked Andrew whether he had instructed anyone to represent me as mentally incapable. Andrew admitted he and Melissa had discussed obtaining control because they believed I might refuse to help with their debts. That sentence changed everything.
Their renovation business was struggling.
They owed vendors, carried heavy credit-card balances, and faced a loan payment due within three weeks. Melissa had calculated that my liquid savings could keep the company alive. Calling me incompetent had been their shortcut to reaching it.
I sat across from my son and felt more disappointed than angry.
He had not come to protect me from financial exploitation. He had brought the exploitation into the bank himself. Samuel closed the folder in front of him and said the bank would treat any further unauthorized access attempt as a serious matter.
The following week, I met alone with my estate attorney. We reviewed every account, beneficiary designation, and authorization I had in place. I did not disinherit Andrew in a burst of anger. I made measured changes instead.
My daughter, Claire, became my primary emergency financial agent. A professional fiduciary became the backup. Andrew remained a beneficiary of part of my estate, but he would never again have direct authority over my accounts while I was alive.
I also demanded a formal repayment agreement for the remaining $26,500.
Andrew resisted at first. He said forcing repayment would push his company closer to failure. I told him that was a business consequence, not evidence that I owed him more money. Eventually, his attorney helped negotiate a payment schedule.
Melissa stopped calling me for several months.
When she finally did, she said they had panicked because the company was collapsing. I told her panic did not justify telling a bank I was mentally incompetent. She apologized, but I could hear that she still believed desperation explained everything.
The business survived, barely.
Andrew sold a recreational boat, canceled a planned kitchen remodel, and let two employees go. He also sold one investment property he had insisted was “too important” to touch. Within eight months, he had repaid most of what he owed me.
Our relationship did not recover as quickly.
For years, Andrew had been the child I trusted most with practical matters. After the bank incident, I checked every document twice before signing anything involving him. Trust became something he had to rebuild rather than something he automatically received.
One afternoon, he came to my house alone.
He admitted Melissa had first suggested using the old power of attorney, but he had agreed because he convinced himself I would eventually forgive him. He said seeing Samuel and the bank attorney treat the situation seriously had frightened him. I told him it should have.
Then he said something I had waited months to hear.
“I knew you could manage your money.”
That mattered more than the apology.
He finally admitted the lie had never been about my age, memory, or ability. It had been about access. Once he said that aloud, there was nothing left to disguise as family concern.
Samuel retired the following year after almost three decades at the bank.
At his retirement lunch, I thanked him for protecting my independence when my own family tried to take it away. He shook his head and said he had only followed the instructions I had put in place. That was exactly why I trusted him.
I still manage my own accounts.
I still pay my bills, review my statements, and make my own investment decisions. Andrew now asks before offering advice. Melissa no longer speaks for me in financial meetings.
They thought age made me easy to control.
What they forgot was that I had spent decades building both the money and the safeguards around it.
And the four words that terrified my son were never a threat.
They were simply the moment he realized the bank knew exactly who owned the money.