“My money is mine, your money is yours, and your parents are not my responsibility. If they can’t afford their medical bills, that’s their problem.”
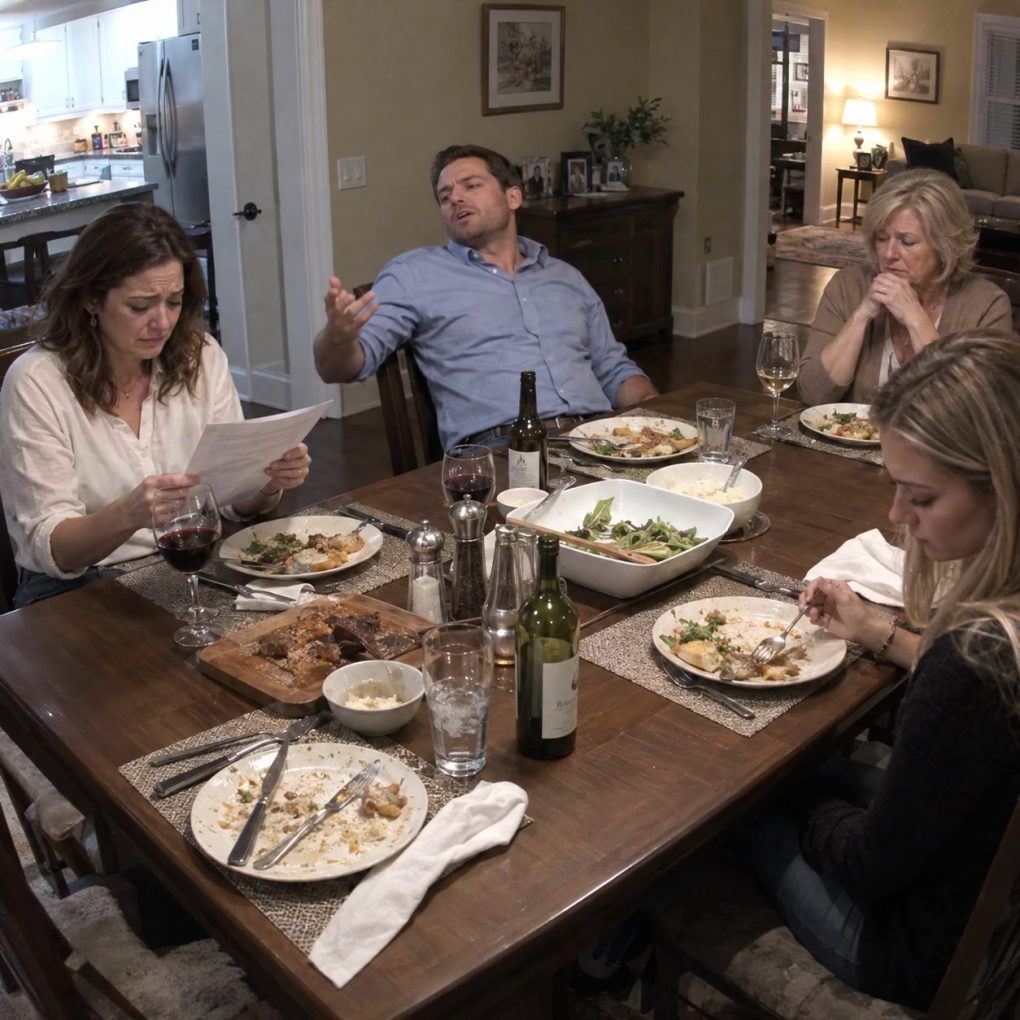
My husband, Daniel, announced this at Sunday dinner, right in front of his mother and younger sister, while I sat there holding the estimate for my father’s home care. He sounded so proud of himself that I almost laughed, because the man lecturing me about financial independence had spent three years letting me quietly support his entire family.
My father had recently undergone emergency heart surgery, and my mother needed $4,800 to hire temporary in-home assistance that their insurance wouldn’t cover. I had planned to pay the expense from my personal savings, but Daniel insisted that helping my parents would interfere with our future plans.
“Your father should have prepared for emergencies,” he said, pouring himself another glass of wine. “I’m not going to sacrifice my financial security because your family made poor decisions.”
His mother, Evelyn, remained silent, while his sister, Claire, nodded as though Daniel had delivered some brilliant financial advice. Neither woman seemed particularly uncomfortable with his words, which was remarkable considering how much money I had spent making their lives easier.
Three years earlier, after Daniel’s father died, I began paying $1,450 toward Evelyn’s monthly mortgage. Eighteen months later, when Claire fell behind on her car payments, I started sending another $400 each month, bringing my total assistance to nearly sixty thousand dollars.
Daniel knew about every payment because he had personally requested my help, promising that his family would eventually become financially independent. What I hadn’t realized was that he had been presenting my generosity as his own while building a substantial private savings account.
I folded the estimate for my father’s care, placed it beside my plate, and smiled.
“Fair enough, Daniel. From now on, your family is your responsibility, and mine is mine.”
He gave me a satisfied nod. “I’m glad you’re finally understanding how things should work.”
“Wonderful. Then I’ll cancel the monthly transfers to your mother’s mortgage and Claire’s car loan, effective after next month’s payments.”
Evelyn’s face immediately lost its color, and Claire nearly knocked over her glass.
“What transfers?” Evelyn whispered.
“The $1,450 I’ve been paying toward your mortgage every month for the past three years,” I answered. “And the $400 I’ve been sending Claire.”
Claire turned toward her brother. “Daniel, you said that money came from you!”
He gripped the edge of the table, his confident expression disappearing.
“Maggie, stop talking.”
But Evelyn was already staring at him with tears gathering in her eyes.
“Daniel,” she whispered, “you told me your wife had never contributed a penny to this family.”
And suddenly, the man who had been lecturing everyone about money couldn’t even look his own mother in the face.
Daniel didn’t speak during the drive home, but the moment we entered the kitchen, he threw his car keys onto the counter and demanded to know why I had humiliated him. I reminded him that he had publicly insulted my parents first, but he dismissed that detail as though my father’s illness were nothing more than an inconvenience.
“You embarrassed me in front of my mother!” he shouted. “She thinks I’ve been lying to her for years!”
“Because you have been, Daniel. And the worst part is that you let her believe I was selfish while I was helping keep a roof over her head.”
He insisted that supporting his mother was different because she was a widow, while my parents were still married and supposedly capable of managing their own problems. When I asked why my father’s heart surgery was less important than his mother’s mortgage, he simply repeated that every family should handle its own financial obligations.
The following morning, I reviewed three years of bank statements and calculated exactly how much I had contributed. Evelyn’s mortgage payments totaled $52,200, while Claire’s car payments added another $7,200, meaning I had spent $59,400 supporting people who believed Daniel had been paying their bills.
That afternoon, Evelyn called me crying, apologizing for the way she had treated me and admitting that Daniel had repeatedly described me as someone who cared only about money. She promised to work out a more sustainable arrangement with Claire, although she asked whether I could allow one final month before ending my support.
I agreed, because punishing Evelyn had never been my intention, and I wanted her to have time to adjust. Daniel, however, interpreted that kindness as permission to demand something else.
Two days later, he announced that his mother needed $7,600 for roof repairs and expected me to contribute half. When I refused and suggested using some of the $46,000 he had saved toward a vacation cabin, his expression hardened immediately.
“That money is for our future, Maggie.”
“So was the money I spent on your family. Funny how only your savings deserve protection.”
The next morning, a banking notification appeared on my phone while I was sitting beside my father’s hospital bed during a follow-up appointment. Daniel had transferred $7,600 from our joint emergency savings into his personal checking account without discussing it with me.
When I confronted him, he admitted that he intended to pay his mother’s contractor, then accused me of being heartless for questioning his decision. He even claimed that my parents had never done anything for us, so I had no right to compare their situation with his mother’s.
That evening, I went to my parents’ house, determined to ask whether they would accept the money I had originally offered. But when my mother heard what Daniel had said, she became unusually quiet and disappeared into their bedroom.
She returned holding a yellowed envelope, which she placed in front of me with trembling hands.
“Your father made me promise never to show you this,” she whispered. “But after what Daniel said, I can’t keep protecting him.”
Inside was a signed loan agreement dated five years earlier, when Daniel had lost his job and our mortgage was nearly overdue.
My father had secretly lent my husband $18,000.
And Daniel had never paid back a single dollar.
I read the agreement three times, struggling to understand how the same man who had insulted my parents for failing to prepare financially could have accepted eighteen thousand dollars from them. My father’s signature appeared beneath Daniel’s, along with a repayment deadline that had passed four years earlier.
When I asked why he had kept the loan secret, my father looked down at his hands, still weak from surgery. He explained that Daniel had come to him during a difficult period, embarrassed about losing his job and terrified that I would worry about our mortgage.
“He asked me not to tell you, sweetheart,” Dad said quietly. “I thought I was helping him protect his dignity, and I believed he’d repay us when things improved.”
I sat beside him and cried, not because of the money, but because my parents had protected my husband from humiliation while he publicly shamed them for needing help. My mother admitted they had never demanded repayment, even when their retirement savings became strained, because my father didn’t want money to damage our marriage.
That night, I waited for Daniel in our living room with the agreement, our joint bank statement, and the records of every payment I had made toward his family’s expenses. He came home carrying takeout, smiling as though the argument had already been forgotten, until he noticed the papers arranged on the coffee table.
“What’s all this?” he asked.
“Your definition of financial responsibility,” I answered, sliding the loan agreement toward him. “You told me my parents had never helped us, so would you like to explain why you still owe my father eighteen thousand dollars?”
Daniel stared at the document, and for several seconds, his mouth opened without producing a sound. Finally, he claimed the money had been a gift, but the signed agreement clearly identified it as a loan and included repayment terms.
“I was going to pay him back,” he muttered.
“Five years ago, Daniel. You found forty-six thousand dollars for your dream cabin, but you couldn’t find eighteen thousand to repay the man who helped save our home.”
He accused my parents of manipulating me, then demanded to know why they had waited until now to bring up the debt. When I reminded him that my father needed only $4,800 for temporary care, his face tightened, and I saw the exact moment he realized how indefensible his position had become.
The following morning, I consulted a family-law attorney about our shared finances and the money Daniel had moved from our emergency account. With advice about our legal options, I told Daniel that I wanted the $7,600 restored, a realistic repayment arrangement with my father, and a complete accounting of our household savings.
He resisted until Evelyn came to our house and confronted him herself, having learned about the loan from my mother. Standing in our kitchen, she told her son that she was ashamed he had allowed two families to sacrifice for him while pretending he owed neither of them anything.
“Your wife helped me keep my home,” she said through tears. “And her father helped you keep yours. When did you become a man who thinks gratitude is a weakness?”
Daniel eventually restored the joint emergency funds from his personal savings and repaid my father the $18,000 he owed. Evelyn and Claire also changed their arrangements: Claire moved into her mother’s spare bedroom, contributed toward household expenses, and resumed making her own car payments.
I had hoped those changes might save our marriage, so I agreed to attend counseling with Daniel for several weeks. But during our fifth session, he told the counselor that his biggest mistake had been allowing me to embarrass him in front of his family, and that he was still waiting for my apology.
That was when I understood that repayment wasn’t the same as remorse.
I moved into an apartment near my parents and filed for divorce, leaving our attorney-assisted property negotiations to determine how the remaining marital assets would be divided. Daniel begged me to reconsider, insisting that we had survived worse arguments, but I couldn’t return to a marriage where my kindness had been treated as a resource he could spend without respect.
Several months later, after our divorce was finalized, my father was recovering well enough to take short walks around his neighborhood. One afternoon, as we sat on his porch watching my mother tend her flowers, he apologized for keeping the loan secret and said he worried that telling me had destroyed my marriage.
I took his hand and shook my head.
“You didn’t destroy my marriage, Dad. You just helped me see what kind of marriage I was already living in.”
A few weeks afterward, Daniel called and quietly admitted that he finally understood why I had been so hurt. He said he had spent years protecting his own savings while allowing everyone around him to carry responsibilities he considered beneath him.
For the first time, I believed he might actually be telling the truth, but understanding something after losing it doesn’t automatically give you the right to have it back.
I wished him well and ended the call.
I never regretted helping Evelyn, and I never believed that married couples had to combine every dollar they earned. What broke us was never the idea of separate finances; it was Daniel’s belief that my money should be available for his family, while his money and compassion were unavailable to mine.
My husband said my parents were none of his concern, even though my father had once saved him from financial ruin. He wanted me to follow his rules, so I did—and he discovered that the most expensive thing he had ever taken for granted was the wife who kept paying the price for his selfishness.