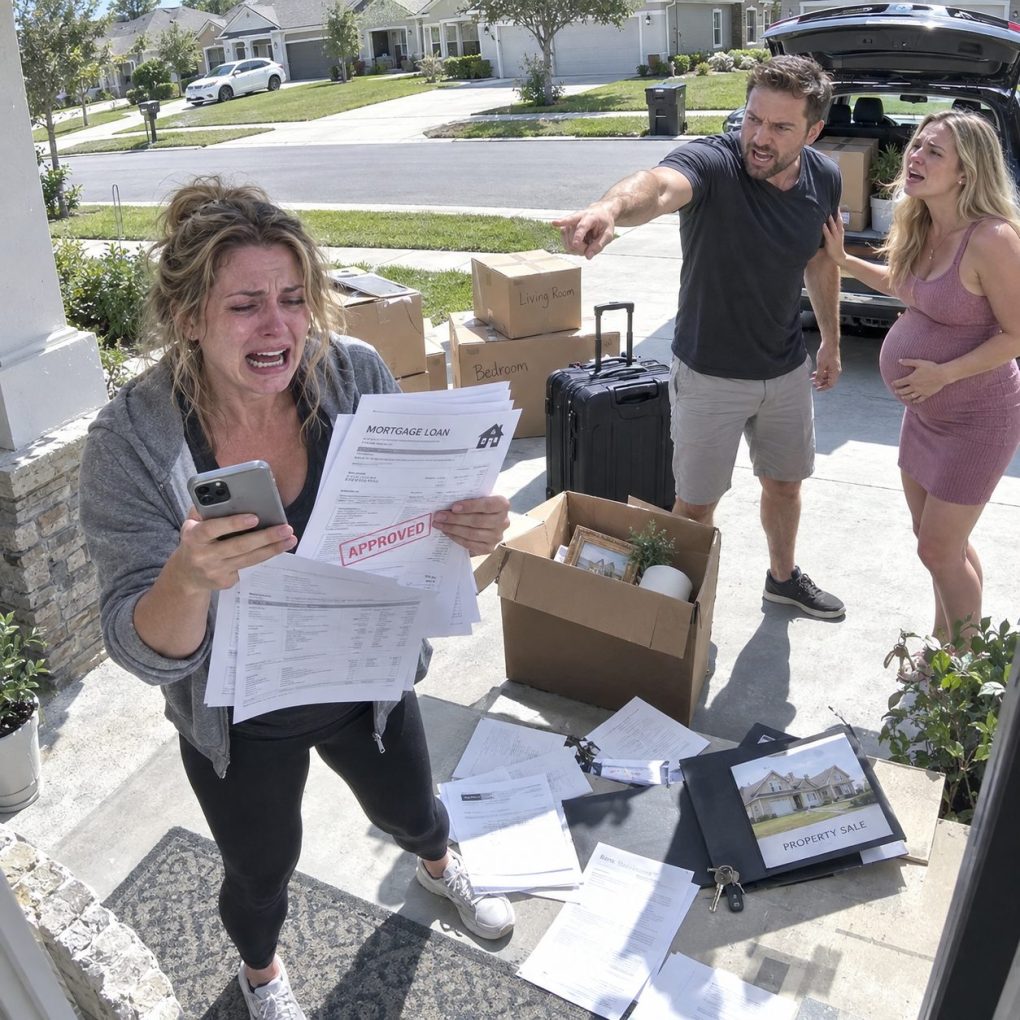
“Forty-eight hours,” my husband said, throwing an empty cardboard box at my feet. “That’s how long you have to get out of this house.”
I stared at Caleb Ford, the man I’d married eight years earlier.
“Why would I leave my own home?”
He smiled.
“Because Elise is pregnant. We’re starting a family, and I’ve already bought us a beautiful house.”
My stomach dropped.
“You’re having a baby with another woman?”
“Don’t make this dramatic, Marissa. Our marriage has been over for months.”
Apparently, he’d forgotten to inform me.
But the worst part came when I checked my phone.
A bank notification showed a transfer of $152,000 from my personal savings account.
Every dollar I’d saved before and during our marriage was gone.
“Caleb,” I whispered, “where’s my money?”
He looked away.
“Consider it a contribution to our future.”
“What future?”
He tossed a folder onto the kitchen counter.
Inside was a mortgage agreement for $480,000, financing a $620,000 house in an upscale Columbus, Ohio, neighborhood.
My name appeared as a co-borrower.
My signature appeared on seventeen pages.
Except I hadn’t signed a single one.
The settlement statement showed that my $152,000 had paid the down payment and closing costs.
And the property’s listed owners?
Caleb Ford and Elise Dalton.
Not me.
“You forged my signature?” I screamed.
He shrugged.
“You would’ve refused if I’d asked. The loan needed your income to qualify.”
I grabbed the documents.
“This is fraud!”
“Prove it,” he replied coldly.
Then he leaned closer.
“And don’t bother fighting over this place. I want you out in two days.”
He walked outside, leaving me trembling beside the kitchen counter.
I nearly collapsed.
But while examining the closing documents, I noticed something unusual.
The mortgage had been arranged through a company called Redwood Mortgage Partners.
A handwritten note beside the loan officer’s name said:
“Second file approved. Both transactions cleared.”
Second file?
What second file?
Before I could investigate further, my phone rang.
An unfamiliar man spoke urgently.
“Is this Marissa Ford?”
“Yes.”
“My name is Simon Dalton. I’m Elise’s husband.”
My breath caught.
“Her husband?”
“We’ve been married eleven years,” he said. “And I think your husband and my wife have been stealing from both of us.”
Then his voice dropped.
“Marissa, I found Redwood Mortgage Partners on a loan I never applied for.”
I gripped the counter.
“How much?”
“Sixty-eight thousand dollars.”
Then he added:
“And the signature on that loan isn’t mine either.”
Simon arrived at a coffee shop the next morning carrying a folder thick with documents.
He looked exhausted.
“Elise told me she was staying with her sister,” he said. “I found out about Caleb when a lender’s letter arrived at our house.”
He showed me a $68,000 home-equity loan taken against the property he and Elise jointly owned.
His signature had been forged.
The money had already been withdrawn.
“Look at the broker,” Simon said.
Redwood Mortgage Partners.
The same loan officer.
The same notary.
And both transactions had closed within forty-eight hours of each other.
I felt sick.
“They planned this together.”
Simon nodded.
“I think they used my home equity to furnish their new house.”
Then he showed me photographs from Elise’s social media account.
There she stood beside Caleb in a luxurious kitchen, smiling beneath a caption:
“Our forever home. Everything we’ve dreamed of.”
I recognized the address from my stolen mortgage documents.
Simon stared at the photograph.
“She told me the baby was mine.”
His voice cracked.
“I was painting the nursery while she was buying another house with your husband.”
Neither of us spoke for a moment.
Then Simon straightened.
“We need lawyers. And we need to report this.”
That afternoon, we contacted our lenders’ fraud departments and filed police reports.
My attorney helped me dispute the unauthorized transfer and the forged mortgage, while Simon began challenging the fraudulent loan against his property.
She also explained something Caleb hadn’t considered.
Because both our names were on the lease, he couldn’t legally force me out simply by declaring a forty-eight-hour deadline.
I wasn’t leaving on his terms.
Three days later, Caleb called me, furious.
“You reported the mortgage? Do you understand what you’ve done?”
“Yes,” I answered. “I’ve told the truth.”
“You’re destroying my future!”
I looked at the empty cardboard boxes he’d left in our hallway.
“No, Caleb. You mortgaged mine without permission.”
Then he said something that confirmed our suspicions.
“Elise told me her husband would never notice the second loan.”
I switched the call to speakerphone so my attorney, sitting beside me, could hear.
And suddenly, Caleb went silent.
“Caleb, I need you to understand something,” my attorney said into the phone. “My client will not discuss these transactions with you directly anymore.”
He hung up.
For the first time since our marriage began, I wasn’t afraid of his anger.
Over the following months, investigators obtained the mortgage applications, closing records, bank transfers, and communications connected to Redwood Mortgage Partners.
The evidence uncovered a disturbing pattern.
Caleb and Elise had worked with the same loan officer, who had helped process both applications using false identity-verification records.
The notarial acknowledgments were fraudulent.
Records also showed that Caleb had accessed my online banking credentials to authorize the $152,000 transfer.
He had used my financial identity to secure the mortgage because his income alone wasn’t enough.
Elise had done something similar to Simon.
The $68,000 home-equity loan had helped pay for renovations, furniture, and other expenses associated with their new home.
They hadn’t simply fallen in love with each other.
They had built an entirely new life using money and credit that belonged to their spouses.
When the evidence became public through the court proceedings, Caleb called me from his attorney’s office.
His voice sounded different.
Small.
“Marissa, please. If this becomes a criminal case, I could lose everything.”
I stared at the small scar on my hand from the afternoon I’d dropped a glass after discovering the theft.
“You gave me forty-eight hours to leave my home,” I reminded him. “You didn’t care whether I had somewhere to go.”
“I made a mistake.”
“No. You made a plan. You signed my name, emptied my account, and told me to prove it.”
He began crying.
“Can’t you forgive me?”
“I can eventually let go of the anger,” I replied. “But forgiveness doesn’t mean protecting you from the consequences.”
I ended the call.
Fourteen months after that first confrontation, Caleb and Elise entered guilty pleas to criminal charges connected to the forged loan documents and stolen funds. The loan officer also faced prosecution for his role.
The lender accepted the fraud findings and released me from liability for the unauthorized mortgage. My credit records were corrected.
The house was sold under court supervision as part of resolving the financial claims.
I recovered $126,000 through the sale and related civil proceedings. Caleb was ordered to repay the remaining $26,000, although collection would take time.
Simon also obtained a resolution removing the fraudulent home-equity debt from his responsibility.
Neither of us recovered the time we’d lost.
But we recovered our freedom.
My divorce was finalized that autumn.
I moved into a modest two-bedroom apartment with large windows and a balcony overlooking a quiet street.
For the first time in eight years, every dollar in my bank account was under my control.
One afternoon, Simon called.
“Elise had the baby,” he said.
I hesitated.
“Is the child healthy?”
“Yes. A little girl.”
There was a long silence.
Then Simon added, “I don’t know who she’ll grow up believing her parents are. But I hope nobody ever makes her feel responsible for what they did.”
His words stayed with me.
That little girl hadn’t forged signatures.
She hadn’t stolen money.
She hadn’t destroyed two marriages.
She was innocent.
And whatever happened to Caleb and Elise, I hoped their daughter would grow up surrounded by people who understood the difference between love and possession.
A few weeks later, I received a letter from Caleb.
He wrote that losing his marriage, reputation, and freedom had forced him to confront the person he’d become.
He said he was sorry.
This time, he didn’t ask me to come back.
I folded the letter and placed it in a drawer.
I didn’t need another conversation.
I didn’t need revenge.
I needed peace.
On the first anniversary of the day Caleb ordered me out, I took myself to dinner at a small Italian restaurant downtown.
I ordered the expensive pasta I used to avoid because Caleb called it wasteful.
I bought flowers on the way home.
Then I stood on my balcony watching the sunset, knowing I had finally built a life no one else could secretly mortgage away.
Caleb had tried to steal my savings, my home, and my future. But the one thing he couldn’t steal was my ability to begin again.
A house can be bought with stolen money. A signature can be forged. But a loving home can only be built with honesty, respect, and trust.