I received a $3.8 million retirement package and decided to leave work early to surprise my husband and daughter. But when I walked into the house, I overheard something in the kitchen that shattered everything I believed about my family. They had no idea I was listening. What I did next…
The day I received my $3.8 million retirement package should have been the happiest day of my life. Instead, it became the day I discovered that my husband and daughter had been planning to betray me.
After thirty-six years working for a major healthcare company in Chicago, I was finally retiring at sixty-two. My compensation package included retirement savings, deferred bonuses, and company stock worth approximately $3.8 million.
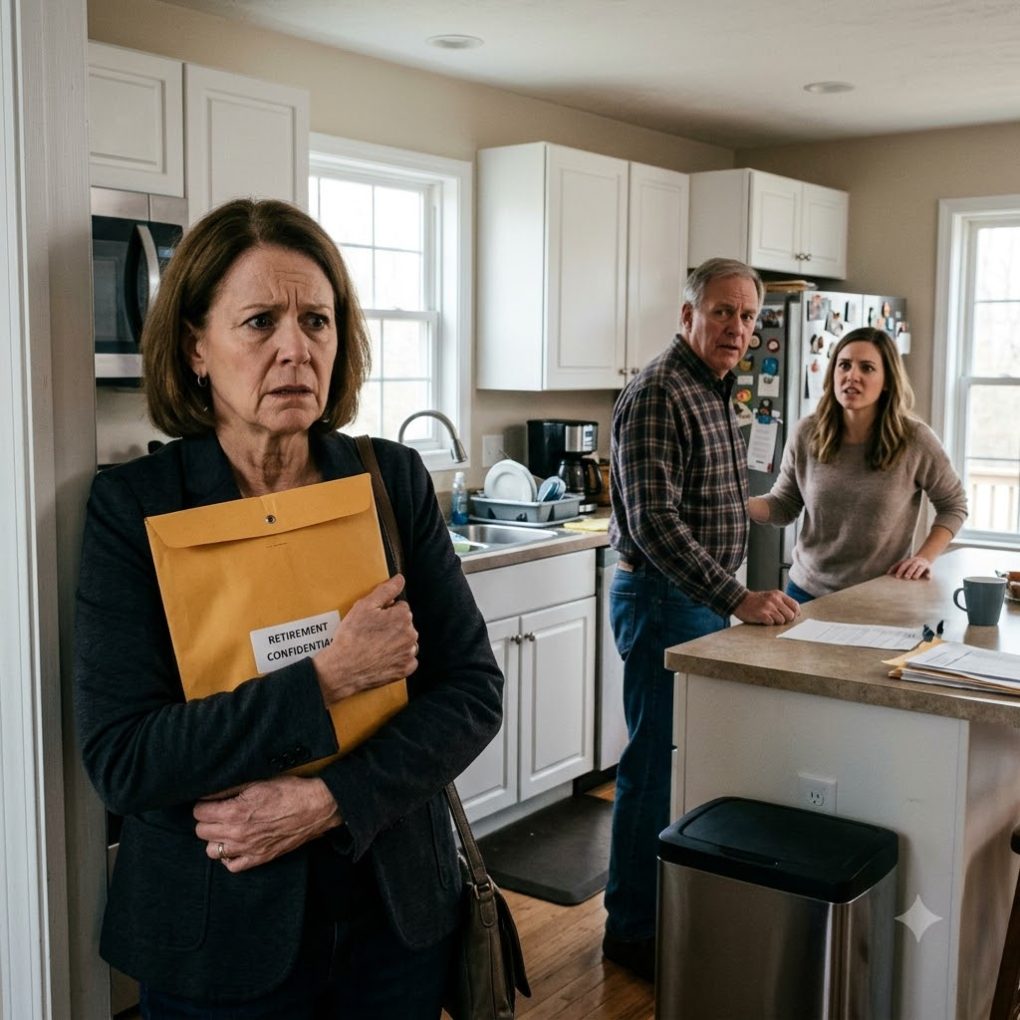
I left work three hours early, carrying a bottle of champagne and a folder containing my retirement documents. I wanted to surprise my husband, Martin, and our thirty-three-year-old daughter, Chloe.
But when I entered the house, I heard their voices coming from the kitchen.
“She’ll sign it if you tell her it’s standard retirement paperwork,” Chloe whispered.
Martin laughed. “Your mother trusts me. She won’t even read it.”
I stopped walking.
“What about the six hundred thousand?” Chloe asked.
“Once she gives me financial authority, I’ll transfer enough to cover the investment. She’ll never notice until everything is finalized.”
My heart began pounding.
Chloe sounded nervous. “Dad, that money belongs to Mom. What if she refuses?”
“Then we’ll convince her she’s too overwhelmed to manage everything herself. She’s getting older. People will understand.”
I gripped the champagne bottle so tightly my fingers hurt.
For thirty-four years, I’d trusted Martin with my life. I’d paid our mortgage, helped fund Chloe’s education, and supported his struggling investment ventures.
Now they were discussing how to take control of my retirement money.
I quietly stepped backward and looked through the partially open kitchen door.
On the table lay a document titled Durable Financial Power of Attorney.
My name was printed across the top.
Beside it was a transfer authorization for $600,000.
Then I heard Chloe say something that shattered me completely.
“Just make sure Mom doesn’t find out about the money you already took from the joint account.”
Martin answered, “She won’t. Not if you keep your mouth shut.”
I felt the blood drain from my face.
There was already missing money.
And both of them knew.
I returned to my car without making a sound. I photographed my retirement paperwork, called my financial advisor, and scheduled an emergency appointment with an attorney.
Then I sent Martin a message.
“Wonderful news. My retirement package was approved. Let’s celebrate tonight.”
His response arrived immediately.
“That’s amazing, sweetheart! Chloe and I have a little paperwork for you to sign.”
I stared at the screen.
They thought I was walking straight into their trap.
But they had no idea that, this time, I was bringing one of my own.
The first person I called was my financial advisor, Susan Parker, who had helped me prepare for retirement over the previous decade. When I told her what I’d overheard, she went silent.
“Helen, please tell me you haven’t signed anything.”
“Nothing.”
“Good. Don’t sign any documents your husband gives you until an independent attorney reviews them.”
She explained that my retirement package wasn’t a single bank account containing $3.8 million. It included several types of assets, each with different rules for withdrawals, ownership, and taxes. Giving Martin broad financial authority could expose me to serious risks.
My attorney, Rebecca Collins, was equally concerned. She advised me to secure my personal accounts, preserve financial records, and avoid confronting Martin until I understood exactly what had happened.
That afternoon, I logged into our joint checking and savings accounts.
What I discovered made my hands shake.
Three weeks earlier, Martin had transferred $118,000 from our joint savings account to a company called Brookfield Ventures LLC.
I’d never heard of it.
The transaction had been authorized through Martin’s access to our joint account, so the bank hadn’t flagged it as suspicious.
But the money represented nearly half our liquid savings outside my retirement accounts.
I immediately downloaded the statement.
Then I searched the company’s name.
Brookfield Ventures was registered to my daughter.
Chloe.
I stared at the screen, remembering every time she’d told me her business was doing wonderfully.
At seven that evening, I returned home.
Martin had prepared dinner. Chloe was already sitting at the kitchen table with two glasses of wine.
“There’s our millionaire!” Martin announced, rushing forward to kiss my cheek.
I stepped away.
Chloe smiled nervously. “Mom, we’re so proud of you!”
“Thank you,” I replied. “What’s the paperwork?”
Martin blinked. “What?”
“You mentioned paperwork in your text. Let’s see it.”
He exchanged a quick glance with Chloe.
Then he retrieved a blue folder.
“It’s just something to simplify your finances now that you’re retiring,” he explained. “You know how complicated these investments can be.”
I opened the folder.
The financial power of attorney would give Martin extensive authority to act on my behalf if I signed it.
I placed it on the table.
“Why do you need control of my retirement accounts?”
Martin’s expression tightened.
“Helen, don’t start making accusations.”
“Then answer the question.”
Chloe interrupted. “Mom, Dad is trying to protect you.”
I looked directly at her.
“Is that why your company received $118,000 from our savings account?”
Her wineglass slipped from her hand.
It shattered against the floor.
Martin jumped to his feet.
“You’ve been snooping through our finances?”
“Our finances?” I repeated. “I’ve worked thirty-six years to build those savings. Of course I’m entitled to review them!”
Chloe began crying.
“Dad said you agreed!”
I turned toward Martin.
He shook his head furiously. “She’s confused. The money was an investment!”
“What investment?”
He hesitated.
Then he admitted he’d committed funds to a proposed luxury vacation development through Chloe’s company. The original payment was supposed to secure their participation before additional financing arrived.
The project was now short of money.
And he wanted another $600,000 from my retirement assets to keep it alive.
“That investment could make us rich,” he argued.
“We already had enough to retire comfortably!” I shouted.
He slammed his fist against the table.
“You’ve always been afraid to take risks! That’s why I’ve never been able to build anything of my own!”
For a moment, I couldn’t speak.
I’d paid our mortgage when his first business failed. I’d covered Chloe’s college tuition. I’d worked overtime while Martin pursued one unsuccessful investment after another.
And somehow, I was the selfish one.
“I’m not signing anything,” I said.
Martin stepped closer.
“Then you’re destroying our family’s future.”
“No,” I answered. “I’m protecting what’s left of it.”
I packed an overnight bag and drove to my sister’s house.
The next morning, Rebecca called after reviewing the documents I’d sent her.
“Helen, there’s something else.”
My stomach tightened.
“What?”
“Your husband contacted a financial planning firm last week. He told them you were becoming forgetful and wanted him to take over your financial decisions.”
I stared at the wall.
Rebecca continued.
“He asked them to prepare the power of attorney for your signature. Fortunately, the firm hasn’t received an executed document.”
I thought about Martin’s words in the kitchen.
She’s getting older. People will understand.
He hadn’t merely planned to take my money.
He’d already begun building a story that I couldn’t be trusted to manage it myself.
I looked at my attorney’s number on the screen.
“Rebecca,” I said, “I want to know exactly how far he’s gone.”
And this time, I wasn’t going to protect him from the consequences.
Over the following week, Rebecca and I carefully reconstructed everything Martin had done. We contacted the financial planning firm, reviewed our joint account statements, and obtained copies of the documents Martin had prepared for me to sign. The more we uncovered, the more I realized that my husband’s betrayal hadn’t been a moment of desperation. It had been a deliberate plan.
Martin knew the retirement package was coming. He’d known about my compensation arrangements for months because I’d shared everything with him. But instead of celebrating the security we’d finally achieved, he’d been calculating how much money he could redirect toward his investment.
Rebecca explained that some retirement assets accumulated during our marriage could be subject to division if we divorced. However, Martin couldn’t simply take control of my accounts because we were married. Any legitimate division would need to follow the law, not his personal demands.
I immediately updated my account security, changed my passwords, and contacted the institutions responsible for administering my retirement benefits. I also requested additional verification procedures for significant transactions.
Then I made a decision Martin never expected.
I filed for divorce.
When the papers reached him, he called seventeen times in one afternoon. I ignored every call until Rebecca advised me to keep future financial discussions between our attorneys.
That evening, Chloe appeared at my sister Louise’s house. She looked exhausted, her eyes swollen from crying.
“Mom, please don’t destroy our family,” she whispered.
I stared at her.
“Did you say those words to your father when he decided to take my retirement money?”
She lowered her head.
“I thought the investment would work. Dad told me we’d make enough to repay the savings and give you even more.”
“Then why didn’t either of you ask me?”
She began crying harder.
“Because we knew you’d say no.”
I nodded slowly.
“Exactly.”
For the first time, Chloe stopped trying to defend herself. She admitted she’d known about the $118,000 transfer and helped prepare financial information for the proposed $600,000 investment. She had also allowed Martin to use her company to receive the earlier payment.
But she insisted she hadn’t understood how far Martin intended to go with the claims about my memory.
“Mom, I never wanted people to think you were incapable.”
“Then why didn’t you stop him when you heard what he said in the kitchen?”
She covered her face.
“I was scared we’d lose the money.”
I felt tears rising, but I refused to look away.
“You were scared of losing money, Chloe. I was about to lose control of my own life.”
She had no answer.
Before leaving, she gave me copies of the company’s financial records and agreed to provide them to Rebecca. It was the first genuinely helpful thing she’d done since the betrayal began.
Two months later, the proposed vacation development collapsed when its organizers failed to secure sufficient financing. Much of the original $118,000 was tied up in project expenses, and recovering it became a complicated financial dispute.
Martin was devastated.
He called Louise and begged her to convince me to return home.
“Tell Helen I’ve made a terrible mistake,” he said. “I’ll do whatever she wants.”
Louise’s response was simple.
“Martin, she trusted you for thirty-four years. You can’t fix what you did with one apology.”
Meanwhile, my retirement arrangements remained secure. I worked with Susan to develop a sensible withdrawal plan that accounted for taxes, healthcare costs, and my long-term living expenses.
For the first time in decades, I wasn’t making financial decisions around Martin’s ambitions.
I was making them for myself.
The divorce negotiations took months. Our attorneys reviewed marital assets, debts, retirement accounts, and the disputed investment. I didn’t receive everything I’d accumulated during the marriage, and Martin didn’t walk away with nothing. We negotiated a settlement that accounted for our shared finances and the money he’d already transferred from joint savings.
It wasn’t a magical courtroom victory.
It was a difficult, expensive process.
But it gave me something more valuable than revenge.
Freedom.
Nine months after that terrible afternoon in the kitchen, the divorce was finalized.
I moved into a beautiful two-bedroom condominium near Lake Michigan. It wasn’t enormous or extravagant. But it had large windows, a balcony overlooking the water, and enough space for the books and photographs I’d collected throughout my life.
My first morning there, I sat outside with a cup of coffee and watched the sunrise.
No arguments.
No financial demands.
No one telling me I was too old to make my own decisions.
Just peace.
Chloe continued reaching out. At first, I kept our conversations brief. I wasn’t ready to pretend everything was normal.
Eventually, she began taking responsibility without making excuses. She found work outside her struggling company and started addressing its remaining obligations.
One afternoon, she visited my condo carrying a small box.
Inside was a framed photograph of the three of us taken at her college graduation.
“I miss when we were happy,” she whispered.
I looked at the photograph.
“So do I.”
She began crying.
“Will you ever forgive me?”
I thought carefully before answering.
“I hope so, Chloe. But forgiveness doesn’t mean I can trust you with everything again.”
She nodded.
“I understand.”
We sat together for nearly two hours, talking about ordinary things for the first time in months. It wasn’t a complete reconciliation, but it was a beginning.
Martin sent me one final letter shortly after the divorce. He admitted that envy had influenced his decisions. He’d spent years watching my career succeed while his own business ventures repeatedly failed.
When the retirement package arrived, he saw an opportunity to prove he could finally achieve something impressive.
Instead, he’d destroyed the marriage that had supported him through every failure.
I read his letter twice.
Then I placed it in a drawer.
I didn’t respond.
Some apologies deserve acknowledgment, but not every apology requires reopening a relationship.
On the first anniversary of my retirement, Susan invited me to lunch. She asked whether I regretted leaving work early that afternoon.
I smiled.
“Not for a second.”
She looked surprised.
“Even after everything that happened?”
“Especially after everything that happened.”
Had I arrived home at my usual time, I might have signed those documents without questioning them. I might have accepted Martin’s assurances and allowed him to control financial decisions that should have remained mine.
Instead, I heard the truth.
And although it broke my heart, it also gave me the chance to protect myself before more damage was done.
That evening, I opened the folder containing my original retirement announcement.
At the top were the words I’d once believed would guarantee my happiness.
Retirement package: $3,800,000.
I smiled at the number.
But I understood now that financial security meant very little without personal freedom.
I had worked thirty-six years to earn that retirement.
I had spent thirty-four years trusting my husband.
And in one afternoon, I’d discovered how easily the people closest to me could confuse my success with their entitlement.
My husband thought my retirement money belonged to him.
My daughter believed my love meant I would always sacrifice for her.
They were both wrong.
Because the greatest reward of my retirement wasn’t the $3.8 million.
It was finally learning that I could love my family without surrendering my dignity, my independence, or my future.
And the woman who walked out of that kitchen heartbroken was not the same woman watching the sunset from her balcony one year later.
That woman had finally learned to choose herself.