My daughter threatened me, “Either put my name on the property deed, or I’m calling the police!” I looked at her calmly and replied, “Go ahead.” She was convinced the officers would force me to sign over part of my property. But when the police arrived, her plan backfired in a way she never expected…
“Either put my name on the property deed, or I’m calling the police!” my daughter Lauren screamed, slamming a folder onto my kitchen table. I was seventy years old, standing inside the home my late husband and I had spent thirty years paying for. “Go ahead,” I replied. She snatched up her phone and dialed 911. “My elderly mother is refusing to cooperate,” she told the dispatcher. “I’m afraid she’s no longer capable of making decisions about her property.” I stared at her, hardly believing what I was hearing.
My name is Evelyn Reed, and I live in a quiet neighborhood outside Columbus, Ohio. My husband Robert passed away five years ago, leaving me our fully paid-off house. Lauren was my only child. I’d helped her through college, supported her after her divorce, and even paid several bills when she lost her job. But apparently, none of that was enough. She wanted her name on my deed, and she was determined to get it.
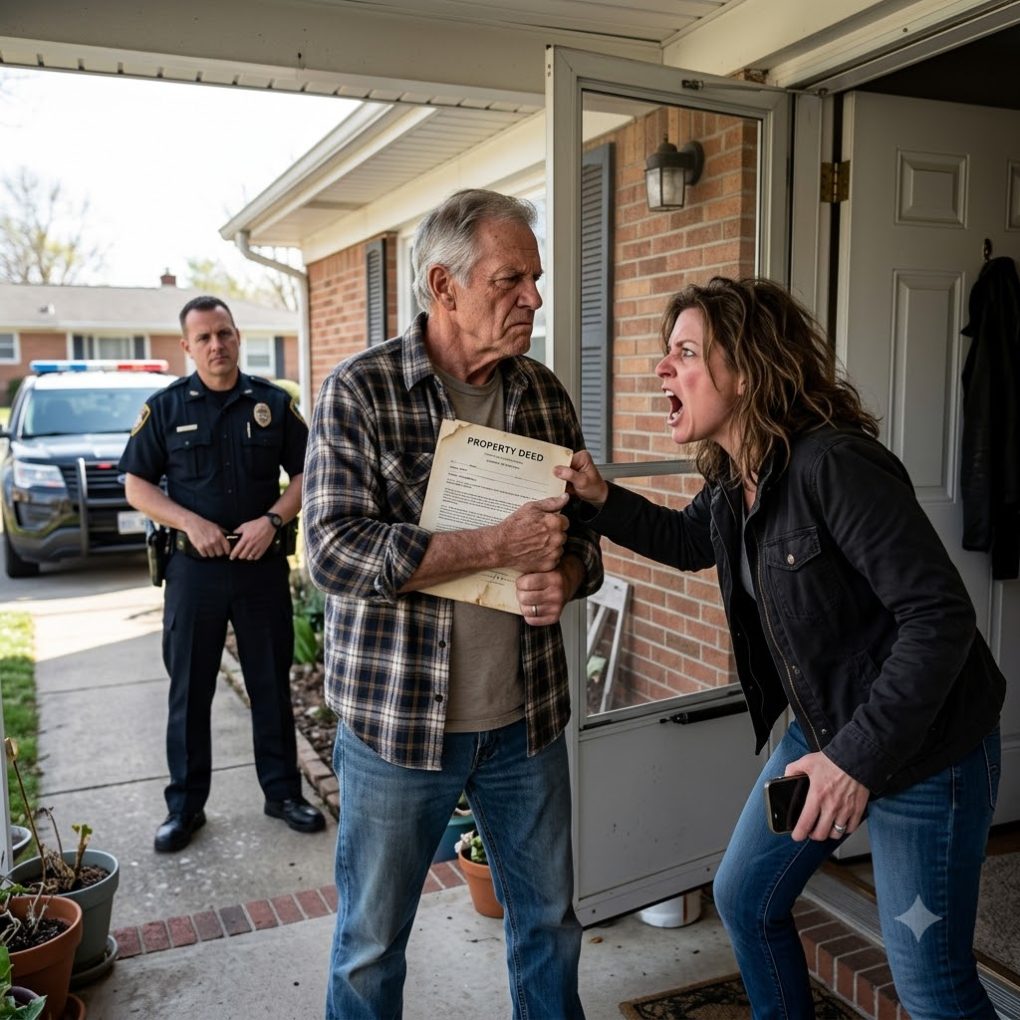
Twenty minutes later, two officers arrived. Lauren rushed to meet them. “Thank goodness! My mother is becoming irrational. I’m trying to protect her property, but she refuses to sign the paperwork.” Officer Maya Torres looked directly at me. “Ma’am, do you understand what your daughter is asking?” “Perfectly,” I answered. “She wants ownership of a house she didn’t pay for.” Lauren shouted, “She’s twisting everything!” The officer raised her hand. “Please let your mother finish.”
Then Lauren made a terrible mistake. She opened her folder and handed Officer Torres several documents. “I’ve already arranged everything with the bank,” she insisted. “She just needs to cooperate.” I glanced at the papers and froze. There was an application for a $92,000 home-equity loan, along with an authorization letter bearing my name. “I never signed that,” I whispered.
Officer Torres examined the signature. “Lauren, who completed this application?” My daughter’s expression changed instantly. “I was helping Mom.” “Did she authorize you to sign for her?” Lauren hesitated. “She was supposed to agree.” The second officer stepped closer. “That’s not what she asked.” Suddenly, my daughter lunged toward the folder, trying to snatch it away. “Give me those papers!” Officer Torres pulled them back. “Step away from the table, ma’am.”
I looked at my daughter, whose face had turned pale. She had called the police expecting them to force me to surrender my property. Instead, she’d handed them evidence of something far more serious. And when Officer Torres asked whether I’d ever approved that loan, my answer changed everything.
“Absolutely not.”
Officer Torres asked Lauren to sit down while her partner took my statement. My daughter folded her arms and stared at the wall, refusing to look at me. “Mrs. Reed, has anyone had access to your financial documents recently?” the officer asked. I thought for a moment. Six weeks earlier, Lauren had offered to organize my paperwork after I complained about being overwhelmed by insurance statements and property-tax notices. She’d spent an entire afternoon in my study. At the time, I’d been grateful. Now I remembered how she’d insisted on taking several documents home to make copies.
“She had access to everything,” I admitted. Lauren immediately interrupted. “Because you asked me to help!” Officer Torres turned toward her. “Helping someone organize paperwork doesn’t authorize you to sign their name.” The room fell silent. Lauren’s hands began trembling. When the officer asked whether she’d copied my signature, she whispered, “I was going to explain everything afterward.” I felt sick. My own daughter had planned to borrow against my home without my knowledge, then use the police to pressure me into cooperating when I refused to add her name to the deed.
The officers documented the disputed paperwork and advised me to contact the lender and an attorney immediately. They explained that the suspected forgery would require further investigation. Before leaving, Officer Torres looked directly at Lauren. “Your mother cannot be forced to transfer her property simply because you want her to. Any concerns about her legal capacity must be addressed through the proper legal process, not threats.” Lauren grabbed her purse and stormed toward the door. “You’ll regret humiliating me like this!” she shouted. I watched her leave without answering. For the first time in my life, I was afraid of what my daughter might do next.
The following morning, I called the bank’s fraud department. A representative confirmed that a home-equity loan application had been submitted using my personal information. Fortunately, the loan had not been approved. Additional verification was still required. I disputed the application, requested written confirmation, and immediately scheduled an appointment with my attorney, Helen Grant. She checked the county property records and confirmed that my name remained the only one on the deed. We prepared notices explaining that Lauren had no authority to act on my behalf. I also changed my locks and secured every financial document in the house.
Three days later, Lauren called from an unfamiliar number. Her voice sounded completely different. “Mom, please don’t let this ruin my life.” I asked her why she needed $92,000. After a long silence, she admitted that her failed online business had left her drowning in debt. Creditors were demanding payment, and she was terrified of losing everything. “I thought I could borrow the money against your house and pay it back,” she cried. “You would never have known.” Those words hurt more than her threats. She wasn’t sorry she’d tried to deceive me. She was frightened because she’d been caught. “Lauren,” I said quietly, “you were willing to put my home at risk to save yourself.” Then I ended the call. But the investigation was only beginning.
Over the next several weeks, I learned things about my daughter’s financial situation that she’d hidden from everyone. Her business had closed nearly a year earlier, but she’d continued pretending it was successful. She’d borrowed from friends, accumulated credit-card debt, and ignored letters from creditors. When the bank refused to approve the loan without speaking directly to me, she became desperate. That was why she’d suddenly demanded her name on my deed. She believed becoming a co-owner would give her greater control over the property and improve her chances of obtaining financing. And when I refused, she tried to use the police to intimidate me.
A detective contacted me about the disputed authorization letter. I gave him copies of the messages Lauren had sent, along with the bank’s confirmation that I had never approved the application. My attorney explained that the authorities would decide whether criminal charges were appropriate. I couldn’t control the investigation, and I refused to lie to protect my daughter. That decision broke my heart. I remembered holding Lauren as a newborn, teaching her to ride a bicycle, and watching her graduate from college. I’d spent decades trying to give her every opportunity. Now I had to accept that loving her didn’t mean protecting her from the consequences of her choices.
Two months after the police visit, Lauren asked to meet me at a small café. She looked exhausted, with dark circles beneath her eyes. “I’ve started working with a debt counselor,” she said. “I’m selling what I can and negotiating with my creditors.” Then she pulled an envelope from her handbag. Inside was a handwritten apology. She admitted that she’d copied my signature from an old check and submitted the application without permission. She also acknowledged that she’d called the police hoping they would frighten me into signing. “I told myself I was desperate,” she whispered. “But the truth is, I decided my problems mattered more than your safety.” I read the letter twice before speaking.
“I love you, Lauren,” I told her. “That will never change. But you tried to take control of the home your father and I worked our entire lives to own.” Tears rolled down her cheeks. “Can you ever forgive me?” I looked at her for a long moment. “I hope so. But forgiveness doesn’t mean pretending nothing happened. You need to take responsibility, cooperate with the investigation, and rebuild your life without using mine as collateral.” She nodded without arguing. It was the first conversation we’d had in months that didn’t involve her demanding something from me.
I never added Lauren’s name to the deed. With Helen’s help, I reviewed my estate documents and made sure my wishes were clearly recorded. The house remained mine, and I finally stopped feeling guilty about protecting it. Eventually, Lauren began visiting again, but only when invited. We talked about ordinary things, and slowly, some of the warmth returned. One evening, as I watched the sunset from the porch Robert had built, I thought about the day my daughter threatened to call the police. She’d expected two officers to arrive and force me to surrender what I’d earned. Instead, they uncovered the paperwork she’d tried to hide. Her own phone call had exposed the deception, protected my property, and taught us both a painful lesson: being family does not give anyone the right to take what belongs to someone else.