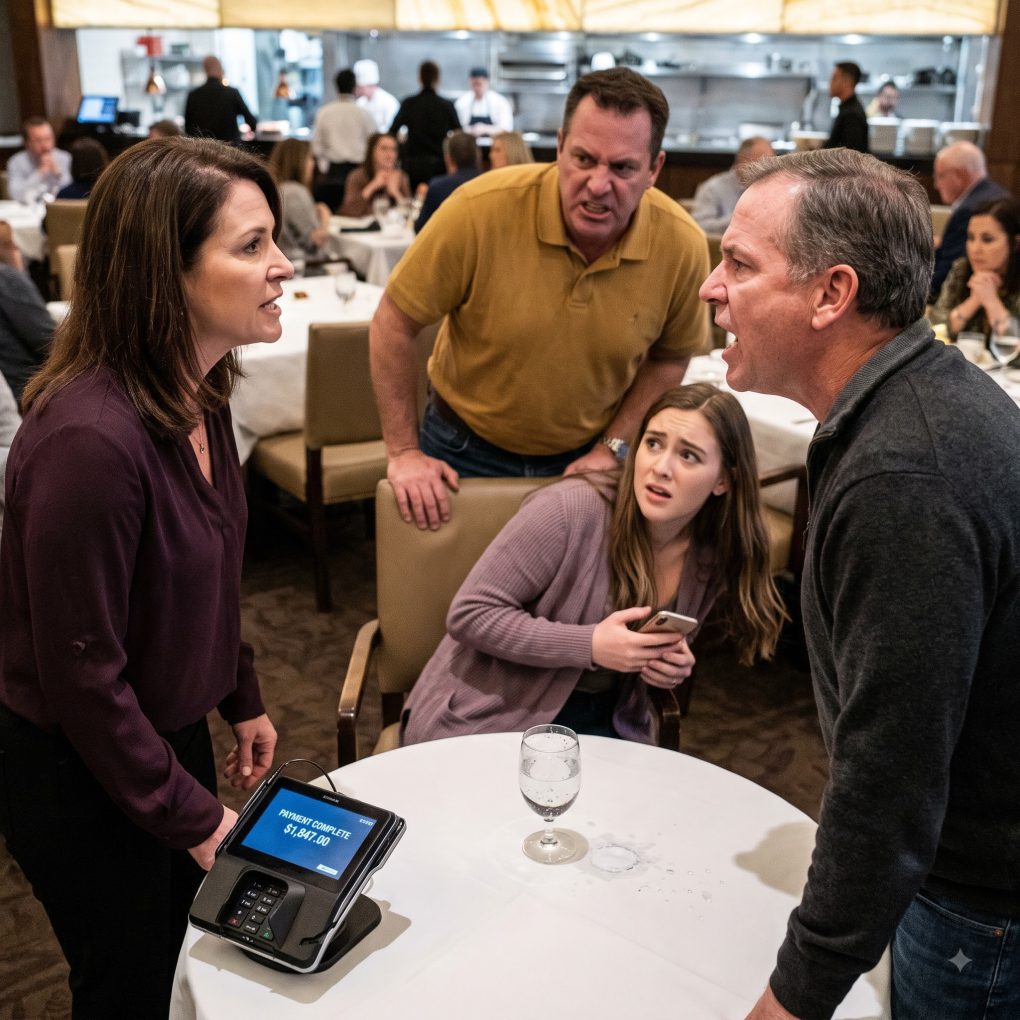
“You’re paying for everyone tonight. You earn more,” Dad said as the waiter set a $1,847 bill in front of fourteen relatives. My brother-in-law, Kyle, leaned toward my sister and whispered, “Finally, useful for something.” He said it quietly, but not quietly enough. I looked around the table and realized nobody seemed embarrassed except me.
I was thirty-nine and worked as a cybersecurity director in Dallas. Yes, I earned more than most of my family, but that had somehow become a standing invitation to spend my money. For five years, I had quietly covered Dad’s property taxes, my sister Megan’s daycare shortfalls, and several emergency bills. No one mentioned any of that while ordering steaks, cocktails, and desserts.
I took out my card and paid the entire check. Dad smiled as though he had won an argument. Kyle lifted his glass toward me without saying thank you. I signed the receipt, stood, and put on my coat.
“This was lovely,” I said. “Also, tonight was the last family expense I’m covering.” Megan’s smile disappeared immediately. Dad asked what I meant.
I told them the automatic transfers totaling $4,250 a month would end at midnight. Dad’s property-tax contribution, Megan’s daycare help, Kyle’s truck-insurance reimbursement, and the family phone plan were all included. I had already removed my card from the shared grocery account. The table went silent.
Kyle stood halfway out of his chair. “You can’t just do that,” he said. I asked why not. He had just called me useful only when I was paying.
Dad accused me of punishing everyone over one joke. I reminded him that the joke came after he volunteered my money without asking. Megan said the daycare payment was different because it affected her children. I told her I would never let the kids go without necessities, but adult convenience was over.
I left before dessert plates were cleared. In the parking lot, my hands shook from anger and relief. I had expected someone to follow and apologize. Nobody did.
By 7:04 the next morning, Dad had called eight times. Megan sent seventeen messages, and Kyle demanded that I restore the truck-insurance payment before renewal. Their panic told me something I should have understood years earlier. They had built parts of their monthly budgets around money they never earned.
Then Dad left a voicemail that changed the argument completely. He said, “If you stop those transfers, Megan may lose the house.” I stared at my phone because Megan had never told me her house was in danger. Suddenly, the dinner bill was the smallest problem in the family.
I drove to Megan’s house that afternoon, but only after telling her I was coming to understand the situation, not write another check. Kyle immediately disappeared into the garage. Megan sat at the kitchen counter with a stack of account statements. Dad arrived ten minutes later looking as though he had not slept.
The truth came out slowly. Megan and Kyle were almost four months behind on their mortgage after Kyle’s landscaping business lost two commercial contracts. Instead of cutting expenses, they had used credit cards to maintain the same lifestyle. My monthly help had been hiding how serious the problem had become.
They owed roughly $31,000 across credit cards. Their mortgage arrears were another $14,600, and Kyle had a substantial balance on his truck. They were also paying for a boat stored at a lake they had visited twice that year. I asked why nobody had mentioned any of this before dinner.
Kyle finally came inside and said their finances were none of my business. I reminded him that he had made them my business every month when my money paid expenses he could not cover. He called me arrogant. Dad told him to stop.
Then I discovered why Dad had been panicking. Three months earlier, he had given Megan $18,000 from his retirement savings without telling me. Most of it had gone toward overdue bills, but the underlying spending had not changed. Dad was now worried he would be asked for more.
I asked Megan to show me the household budget. There was no real budget. They had streaming packages, expensive memberships, restaurant charges, two newer vehicles, and nearly $900 a month in discretionary spending. The numbers were painful because the problem was fixable, just not comfortably.
I offered one form of help. I would pay for a certified financial counselor and a consultation with a housing attorney so they could understand their options. I would not pay the mortgage arrears, credit cards, truck, or boat. Megan started crying.
Kyle became furious. He said family should help family when they had the means. I asked why that rule required me to sacrifice while he kept recreational property and a truck costing more than my first car. He had no answer that did not sound ridiculous.
The counselor met with them two days later. She recommended selling the boat immediately, replacing one vehicle, suspending memberships, contacting the mortgage servicer, and restructuring their debt. None of the recommendations involved my salary.
For the first time, Dad saw the full picture too. He apologized for demanding that I pay dinner simply because I earned more. He admitted that everyone had grown accustomed to treating my income like a family emergency fund. I told him that emergency fund was officially closed.
Megan and Kyle did not lose the house. Their mortgage servicer approved a repayment arrangement after they submitted updated income records and proof of reduced expenses. They sold the boat within three weeks. The proceeds covered a meaningful portion of the arrears.
Kyle sold his expensive truck next. He bought a used work vehicle that was less impressive but perfectly functional. Megan canceled her premium gym membership, meal deliveries, and several subscriptions. Their monthly budget finally began resembling their actual income.
It was not painless. They stopped eating out, postponed a planned vacation, and moved their younger child from a costly private activity program to a community option. Nobody enjoyed those decisions. Nobody became homeless either.
I kept one boundary flexible for the children. When Megan needed help with an unexpected pediatric dental bill, I paid the dentist directly. I made it clear that emergencies involving the kids were different from subsidizing adult lifestyle choices. She understood the distinction by then.
Kyle took much longer.
For several months, he barely spoke to me at family gatherings. Then his business picked up another commercial maintenance contract, and something in his attitude changed. One afternoon, he called and asked if he could come by.
He apologized for the restaurant comment. He said he had been embarrassed about his finances and had turned that embarrassment into contempt toward me. Calling me “useful” had been his way of pretending he was not dependent on my help.
I accepted the apology but did not restore the payments. Kyle said he was not asking me to. That mattered more than anything else he could have said. For once, we understood each other clearly.
Dad changed too. He stopped announcing what I should pay at family events. When fourteen of us met again for his birthday, he asked the restaurant for separate checks before anyone ordered. Nobody died from the inconvenience.
Megan and Kyle spent almost two years paying down the remaining consumer debt. They eventually refinanced the house after their finances improved and rebuilt a modest emergency fund. Dad slowly replaced part of the retirement money he had withdrawn.
As for me, I never regretted the $1,847 dinner. It was expensive, but it purchased something I had failed to establish for years. It drew a visible line between generosity and obligation.
My family used to believe earning more meant owing more. Now they understand that my paycheck belongs to me before it belongs to anyone else. I still buy dinner sometimes, but only when I choose to. And nobody at the table calls me useful anymore.